Uzbekistan is launching 12 investment projects in critical metals this year with combined investment of $166 million, marking the first domestic production of high-purity selenium, tellurium and rhenium in the country’s history alongside 21 new categories of import-substituting products, according to the press service of President Shavkat Mirziyoyev.
The 2026 initiatives are part of a broader industrial programme targeting 120 projects by 2030 with combined investment of $4.2 billion. Production volumes in monetary terms are projected to reach $1 billion by 2028 and $2 billion by 2030, according to a presentation delivered to the President this week. The plan foresees developing up to 28 critical minerals at industrial scale through the exploitation of promising deposits and the creation of modern processing infrastructure.
The Uzbek Technological Metals Complex currently produces primarily tungsten and molybdenum. A central objective of the expanded programme is moving beyond raw material exports to downstream products — metal powders, alloys, rods, wire and industrial components — capturing significantly more value per tonne of ore extracted.
The city of Chirchik will serve as the transformation hub for the sector. A Metals of the Future technopark and a dedicated research and development centre will be established there, with measures to facilitate the commercialisation of scientific advances, a startup support programme, and production of high-purity metals and innovative materials. A scientific and technology centre for critical minerals will also be established within the cluster, housing a laboratory capable of conducting nanoanalysis on up to 1,000 samples per day and providing analytical support to geological, mining and metallurgical projects across the country.
Kazakhstan’s state geological company Qazgeology will continue its joint venture with Turkish-Dutch holding CoreX — formerly known as Yildirim — at the Mailyshat licence area within the Bakanas exploration block in East Kazakhstan Region, while four other CoreX joint ventures with Qazgeology are being wound up after failing to identify commercially significant mineral resources.
Tau-Ken Samruk, the state mining holding that owns Qazgeology, confirmed in a response to Qazba.kz that the contract extension for Mailyshat Resources LLP is currently under consideration by the Ministry of Industry and Construction. Work at the 152 square kilometre gold exploration area continues in accordance with subsoil use legislation pending a decision. Qazgeology holds a 25% stake in Mailyshat Resources LLP, with the remaining interest held by CoreX subsidiary DTK Metals and Mining B.V. Exploration investment at the Mailyshat licence from 2016 to 2021 totalled 481 million tenge.
The four joint ventures being closed are Surovsky Resources LLP (platinum group elements and gold), Tekturmas Resources LLP (chrome), Charsky Resources LLP (chrome) and Shiderty-Ekibastuz Resources LLP (chrome). Tau-Ken Samruk confirmed that all contractual geological exploration work at these four sites was completed but did not result in the identification of mineral reserves of industrial or economic significance. The licence areas have been returned to the state in accordance with Kazakhstani legislation and the joint ventures are now undergoing statutory liquidation procedures.
Importantly, all exploration at the four closed projects was financed by the Turkish partner on a free-carry basis, meaning Qazgeology bore no costs and suffered no financial losses from the closures.
Something significant has shifted. In the span of eighteen months, Central Asia has moved from a footnote in Washington and Brussels policy documents to a headline. The Caspian Policy Center’s new report — ‘Central Asia and the New Critical Minerals Frontier: Progress in Reshaping Global Supply Chains’ — is the latest in a wave of think-tank, government, and investor analyses arriving at the same conclusion: the region’s critical mineral resources are strategically indispensable.
This analysis cuts through the optimism to ask the harder questions. What has actually changed on the ground? Which players are genuinely committed versus which are signing MoUs for photo opportunities? And by 2030, what will Central Asia’s real role be in the global supply of critical raw materials?
This analysis draws on the CPC report, the EU Institute for Security Studies’ Chaillot Paper on China’s critical raw material weapon, the C5+1 Critical Minerals Dialogue in Astana on 10 June 2026, the Carnegie Endowment’s analysis of the Middle Corridor, the CFR’s report on leapfrogging China’s dominance, and the Forum’s accumulated perspective from running MINEX Asia, MINEX Europe, and MINEX Eurasia.
1. The Geopolitical Wake-Up: Real, But Overdue
The CPC report is unambiguous: critical mineral supply chains are no longer an economic issue — they are a national security and geopolitical issue. China controls approximately 90% of global rare earth refining, 60% of lithium processing, and over 70% of cobalt refining. By 2022, China controlled 100% of global graphite processing. These are not numbers that have crept up on policymakers. They have been visible for years. What has changed is the willingness to act — and the nature of Beijing’s own use of this leverage.
The EUISS Chaillot Paper published in May 2026 makes for sober reading. Beijing’s sharp reduction of critical raw material exports in 2025 — covering germanium, gallium, antimony, bismuth, and rare earths — was not a one-off retaliation against US semiconductor restrictions. It evolved into a systematic geo-economic weapon. The paper documents how China used its export licensing regime to extract information about Western defence-industrial networks, coerce EU trade policy on electric vehicle tariffs, and deter Japan from strengthening its defence posture on Taiwan.
What is less widely understood is how the apparent ‘détente’ of late 2025 conceals a structural tightening. The October 2025 rare earth export controls were suspended for one year as part of the Xi–Trump Busan summit deal — they are due to re-activate in November 2026. Critically, the April 2025 controls remain fully in force; only the October tranche was suspended. More consequentially, China’s export licensing architecture now includes extraterritorial provisions that allow Beijing to restrict re-exports of products containing Chinese-origin rare earth content even between third countries. The détente is not a resolution. It is a one-year suppression of symptoms while the structural disease remains untreated.
China does not merely hold rocks in the ground. It holds the refinery, the processing plant, the magnet manufacturer, and the pricing mechanism. Owning a deposit in Central Asia without access to non-Chinese processing is like owning an oil field with no pipeline.
This is the fundamental reality that too many Western policy documents still dance around. The CPC report is admirably direct about the midstream gap — the fact that even where Western investors enter Central Asian mining, the ore typically still travels east for processing. Closing that gap requires not just exploration investment but decades of patient capital in refining and processing infrastructure. That capital has not yet materialised at the required scale.
2. The MoU Inflation Problem
What should concern anyone serious about this sector is the following. The United States, the EU, Japan, South Korea, and Türkiye are all engaged in what the Forum terms ‘MoU inflation’ with Central Asian governments. The CPC report catalogues a remarkable number of bilateral frameworks, memoranda of understanding, and strategic partnerships signed since 2025. The C5+1 Critical Minerals Dialogue in Astana on 10 June produced more of the same.
These instruments are not worthless — they establish political will and create frameworks for future action. Kazakhstan’s Minister of Industry, Yersayin Nagaspayev, rightly highlighted that Kazakhstan has adopted a new Subsoil and Subsoil Use Code, implemented a ‘first come, first served’ licensing principle, launched a unified digital subsoil platform, and fully adopted CRIRSCO international reporting standards since 2024. Investment in geological exploration has tripled since 2018, exceeding one billion dollars. Western majors including BHP (via its Xplor programme), First Quantum Minerals, Ivanhoe Mines, Teck Resources, Fortescue, and US-based Cove Capital have entered the Kazakh market. Chinese companies are moving faster and at greater scale: Zijin Mining completed a $1.2 billion acquisition of Kazakhstan’s Raygorodok gold mine in October 2025, adding to its existing operations at the Taldybulak Levoberezhny mine in Kyrgyzstan and the Jilau and Taror gold mines in Tajikistan — a three-country “Gold Triangle” across Central Asia. East Hope Group — one of China’s largest private industrial conglomerates and a top-ten global aluminium producer — is advancing a $12.6 billion fully integrated aluminium cluster in Kazakhstan’s Kostanay and Aktobe regions: bauxite mining, a two million tonne per year alumina refinery, a one million tonne per year primary aluminium smelter, and a captive one-gigawatt power plant. The project framework was signed with the Kazakh government in February 2025 and geological exploration of eleven deposits is already under way. If delivered, it would be one of the largest single foreign direct investment projects in Kazakhstan’s industrial history. China National Gold Group has signed an MoU with Uzbekistan covering geological exploration and technology transfer. These are real signals of intent — though the Western and Chinese signals point in very different directions.
But the gap between MoU and mine is measured not in months but in decades. The CPC report states this plainly: developing a major mining project from inception to production can take twenty or more years. Processing and refining require additional capital beyond the mine gate. Political cycles — in Washington, in Brussels, and in Central Asian capitals — run on four-to-five-year horizons. China’s BRI financing runs on twenty-year horizons. This asymmetry is not a detail. It is the central challenge of Western engagement with Central Asia’s mineral sector.
The question is not whether Kazakhstan, Uzbekistan, Kyrgyzstan, or Tajikistan have the minerals. They do. The question is whether Western partners have the institutional patience, the risk appetite, and the financing instruments to compete with a counterparty that thinks in decades, not electoral cycles.
The US International Development Finance Corporation’s recent approval of USD 2.5 billion in strategic investments and the C5+1 roadmap for geological exploration, mining and processing, and global value chain integration are positive steps. But the gap between announced capital and deployed capital in this region remains historically wide. The Forum has documented this cycle repeatedly: enthusiasm peaks around major geopolitical events, and then the deals stall in permitting, due diligence, or financing committees.
3. Where the Real Business Opportunities Are
The following sets out where genuine commercial opportunities are opening up, rather than where the diplomatic activity is concentrated.
3.1 Midstream Processing — The Untapped Prize
The CPC report’s section on closing the midstream gap is the most commercially important part of the document. Central Asia produces raw ore and exports it, largely to China, which captures the value-added margin in processing and refining. The governments in the region know this and want to change it. Kazakhstan and Uzbekistan have explicitly stated they want to develop industrial clusters that capture more of the value chain domestically.
For investors and mining companies, this creates a specific opportunity: joint ventures in processing and refining that give Central Asian governments the industrial development they want and give Western offtake partners the supply chain security they need. This is not easy — it requires technology transfer, long-term offtake agreements, and patient capital — but it is where the alignment of interests is strongest. Companies with refining technology and Western governments with DFI instruments should be looking at this window seriously.
3.2 The Middle Corridor — A Structural Shift in Logistics, With a Named Weak Link
Freight along the Trans-Caspian International Transport Route has increased fivefold in seven years, reaching 4.1 million tonnes across the Caspian in 2024 alone. The war in Ukraine has accelerated this, but the trend is structural. For critical minerals, the Middle Corridor offers an alternative to Chinese-controlled logistics networks. Kazakhstan’s commitment to developing this route is serious, and the Hormuz blockade in place since February 2026 — with oil above $110 a barrel at the time of writing — is providing a live demonstration of exactly why overland alternatives to maritime choke points matter.
But the optimism around the corridor needs to be tempered by a specific and underreported vulnerability. Georgia is currently the corridor’s only gateway to Europe. Until the TRIPP route via Armenia and Azerbaijan’s Nakhchivan exclave becomes operational, Tbilisi is structurally irreplaceable. Yet the Georgian government has just cut funding for the Anaklia deep-sea port — identified by both the World Bank and the EU’s Trans-European Transport Network as the corridor’s central infrastructure priority — from 150 million lari to 50 million lari. Georgia’s existing port capacity is already nearing exhaustion.
The explanation for this decision is contested, but one strand is disturbing: after a Western-led consortium lost the Anaklia contract in 2020, the Georgian government selected as its preferred contractor a Chinese-Singaporean firm currently under US sanctions. There is a credible case that Beijing, which benefits from the Northern (Russian) Corridor and has no strategic interest in the Middle Corridor displacing it, is quietly applying pressure on Tbilisi to limit the western terminus’s capacity.
Kazakhstan’s position in this corridor is more structural than is commonly appreciated: approximately 80% of all rail cargo travelling between China and Europe already passes through Kazakhstan, making it not an emerging alternative route but the existing backbone of Eurasian overland trade. The commercial opportunity in the corridor’s logistics and infrastructure layer is real — port capacity at Aktau and Kuryk, rail and intermodal connectivity through Azerbaijan and Georgia to Türkiye — but companies positioning in this space need to price in the Georgia risk. Türkiye’s role as the corridor’s westernmost reliable node therefore becomes more, not less, strategically significant if Georgia continues to under-invest.
3.3 Uranium — The Quiet Giant
Central Asia produces approximately 50% of global uranium. Kazakhstan alone, through Kazatomprom, dominates global supply. The US Geological Survey has added uranium to its updated list of critical minerals. As the energy security debate in Europe and the US re-centres on nuclear power as a baseload complement to renewables, and as advanced reactor programmes (SMRs in particular) gather momentum, uranium supply security from non-Russian, non-Chinese sources becomes a premium.
The investment thesis for uranium in Kazakhstan is arguably more mature and more deliverable than for rare earths, precisely because the infrastructure already exists. The opportunity is in midstream — converting, enriching, and fabricating fuel outside of Russian-controlled supply chains — and in ensuring Western utilities have long-term offtake agreements with Kazakh producers.
3.3a Titanium — The Overlooked Aerospace Play
Titanium rarely features in critical minerals analysis focused on Central Asia, yet Kazakhstan accounts for approximately 20% of the global aerospace-grade titanium market — a concrete, active commercial relationship, not a geological aspiration. This matters because aerospace titanium supply has been severely disrupted by the Russia sanctions regime: VSMPO-AVISMA, previously the dominant Western supplier accounting for roughly 30% of global aerospace titanium, became inaccessible to Western manufacturers after 2022. Boeing, Airbus, and their tier-one suppliers have been seeking alternative sources ever since. Kazakhstan’s existing market position fills part of that gap and has been doing so quietly while the policy debate concentrates on rare earths and lithium. Titanium is now on both the EU and US critical minerals lists. For investors and industrial offtake partners, the titanium story in Kazakhstan differs from the rare earth story in one crucial respect: the supply chain is already functioning. The opportunity is in expanding and securing existing capacity, not in building it from scratch.
3.4 Kyrgyzstan and Tajikistan — Early-Stage, High-Risk, Potentially High-Reward
The CPC report and the C5+1 framework rightly include Kyrgyzstan and Tajikistan. Kumtor Gold in Kyrgyzstan and Zarafshon Gold in Tajikistan are the flagship projects, but the rare earth and critical mineral potential in both countries is largely unexplored. Legal frameworks are weaker, infrastructure is thinner, and political risk is higher. But for investors and juniors willing to absorb early-stage risk, the geological endowment is compelling.
The legal reform chapter of the CPC report is a necessary reality check here. As Dr. Ruchan Kaya argues directly: No Reform, No Mining. Without clear subsoil use codes, transparent licensing, independent dispute resolution, and ESG frameworks compatible with Western capital markets, foreign investment will remain shallow. Kyrgyzstan and Tajikistan have work to do.
3.5 Technology Transfer and Workforce Development
Central Asian governments are unanimous on one point: they do not want to be raw material exporters indefinitely. They want technology transfer, workforce development, and the creation of domestic industrial capacity. This creates a genuine market for mining engineering services, training, metallurgical technology, and environmental management expertise. European, Japanese, and South Korean companies with this expertise have an opening that pure extractive investors do not.
4. The Six-Party Chess Board: China, Russia, USA, EU, Türkiye, Japan/South Korea
China — The Incumbent with a Structural Advantage
China’s position in Central Asian critical minerals is not primarily about geology. It is about infrastructure, processing capacity, financing terms, and decades of relationship-building. The BRI has locked in logistical corridors, off-take agreements, and debt obligations that are difficult to unwind quickly. Chinese firms continue to invest at scale: Zijin Mining — now the world’s fourth-largest gold producer — has assembled a “Gold Triangle” across Kazakhstan (Raygorodok, $1.2 billion acquisition completed October 2025), Kyrgyzstan (Taldybulak Levoberezhny), and Tajikistan (Jilau and Taror mines, where it is the largest gold producer accounting for over 70% of national output). East Hope Group — one of China’s largest private industrial conglomerates and a top-ten global aluminium producer — is advancing a $12.6 billion fully integrated aluminium cluster in Kazakhstan: bauxite mining, a two million tonne per year alumina refinery, a one million tonne per year primary aluminium smelter, and a captive one-gigawatt power plant across the Kostanay and Aktobe regions. The framework agreement was signed with Astana in February 2025; geological exploration of eleven bauxite and coal deposits is already under way. If delivered, it would be one of the largest single foreign direct investment projects in Kazakhstan’s industrial history — and a textbook example of the integrated industrial model China deploys while Western investors are still circling at the MoU stage. China National Gold Group is advancing into Uzbekistan via government-level MoUs on exploration and technology transfer. Chinese cumulative investment in Central Asia reached $35.9 billion by mid-2025, a 1.5-fold increase since 2020, with Kazakhstan in the first half of 2025 alone attracting an estimated $23 billion in BRI-linked commitments — making it the single largest BRI capital recipient globally in that period. Any honest assessment must acknowledge that China will remain the dominant actor in Central Asian mineral supply chains throughout the 2020s.
The more important question is whether China’s dominance is vulnerable to a strategic discontinuity rather than gradual erosion. The CFR’s February 2026 report makes an argument that cuts against the grain of most current thinking: the United States cannot out-mine or out-process China, and attempting to do so is the wrong strategy. The correct approach is to leapfrog China’s dominance through innovation — scaling rare-earth-free magnets, mine tailings recovery, e-waste recycling, and AI-accelerated materials science. If this thesis is correct, the entire paradigm of building competing mine-to-magnet supply chains in Central Asia may be strategically secondary to the innovation race happening in US and allied laboratories. Central Asian governments and their Western partners should be alert to this possibility: the strategic premium on Central Asian deposits is real today, but it is not permanent if substitute materials technologies mature.
Russia — The Shadow Partner
Russia’s invasion of Ukraine has paradoxically accelerated Central Asia’s strategic importance to the West while complicating its own position in the region. Central Asian governments are navigating with care — they cannot afford to antagonise Moscow, which retains significant economic and security leverage, but they are actively diversifying. Russia’s ability to invest in and benefit from Central Asian critical mineral development is constrained by sanctions, capital flight, and the rerouting of its own economy. For the near term, Russia’s role is more that of a constraint than a competitor in the Western engagement story.
United States — Urgency Without Sustained Patience
Washington’s engagement since 2025 has been substantive. Project Vault (a USD 12 billion public-private reserve initiative), FORGE (the Forum on Resource Geostrategic Engagement), the Critical Minerals Ministerial with 54 countries, and the DFC’s Central Asia investment pipeline represent genuine institutional commitments. The C5+1 framework gives the US a multilateral architecture in the region.
However, it is important to understand what FORGE actually is — and what it is not. The Atlantic Council’s analysis makes a distinction that most coverage obscures: FORGE is structurally different from its predecessor, the Minerals Security Partnership. The MSP functioned primarily as a pooled investment co-ordination vehicle. FORGE is designed as a ‘membership by trade’ model — participation conditioned on adherence to shared market rules and price floors, rather than joint capital deployment. Investment remains bilateral. This means FORGE will not produce a multilateral investment fund for Kazakhstani or Uzbekistani mining projects. It will produce a shared pricing and trade architecture that in theory de-risks bilateral deals — but the capital mobilisation burden still falls on individual governments and DFIs acting separately. For Central Asian partners watching from Astana or Tashkent, this distinction matters enormously.
It is worth keeping the bilateral relationship in perspective: Kazakhstan has attracted more than $480 billion in cumulative foreign direct investment since independence, with gross FDI inflows reaching $20.5 billion in 2024 and investors from more than 120 countries currently active in the country. The US relationship is therefore being built onto an already diversified investment base, not into a vacuum. Kazakhstan signed USD 17 billion in new bilateral agreements with the US during President Tokayev’s November 2025 Washington visit, while Uzbekistan committed to investing up to USD 35 billion in the US over the next three years — directions of flow and deal structures that differ significantly, but which together signal that the C5+1 relationship has acquired genuine commercial weight. But commercial weight at the announcement stage and capital deployed in-country are different things.
The European Union — Engaged But Fragmented
The EU’s Critical Raw Materials Act and the selection of 60 Strategic Projects — including Kazakhstan and Ukraine as external partner countries — represent a serious policy commitment. But the EUISS Chaillot Paper is damning on Europe’s pace of execution: American, Japanese, and particularly European diversification efforts are not on track to replace the volume or range of China-dominated production over the next decade.
The EU’s problem goes deeper than slow bureaucracy or fragmented financing instruments. As of late 2025, despite all the summits, roadmaps, and declared billions, only five EU companies have actually invested in CRM projects in Central Asia. That is not a financing gap problem — it is a near-total absence of private sector engagement. EU policy documents treat Central Asia as five countries of strategic importance; EU commercial reality has concentrated almost entirely on Kazakhstan, which is the only fully recognised EU external strategic partner with both the resource base and the legal framework for large-scale collaboration. Kyrgyzstan, Tajikistan, and even Uzbekistan remain largely outside the EU’s actual investment footprint despite featuring prominently in its diplomatic declarations. Brussels risks building an elaborate architecture of frameworks and roadmaps that covers five countries on paper but delivers in one.
Türkiye — The Underappreciated Swing Player
Türkiye’s role in Central Asian critical minerals deserves far more analytical attention than it currently receives. Ankara’s position as a NATO member, a pragmatic economic partner to both Russia and China, and the institutional convener of the Organisation of Turkic States (OTS) gives it a combination of relationships that no other actor in this space possesses.
The OTS — which brings together Türkiye, Kazakhstan, Uzbekistan, Kyrgyzstan, Azerbaijan, and observer states — is an increasingly active institutional vehicle for economic co-operation amongst Turkic-speaking nations. For critical minerals specifically, it creates a framework for Türkiye to position itself not merely as a transit corridor but as a co-investor and processing ally for Central Asian governments that want to move up the value chain.
The strategic picture that emerges from available data is striking in its specificity. Türkiye’s mineral engagement operates across four distinct partner-and-material vectors:
Partner
Key Materials / Vectors
Türkiye’s Function
Central Asia
Boron, refined REEs, battery recyclables
Co-investor and institutional processing ally via the Organisation of Turkic States (OTS)
China
Manganese, chromium, lithium, copper
Supply chain alternative and competitor in REE midstream processing
Russia & Iran
Light and heavy rare earth oxides
Corridor guardian; bypassing northern routes via the Middle Corridor
Logistics vectors
Transport infrastructure, regional border security
Gateway and facilitator for Eurasian mineral freight flows
Read together, these vectors tell a coherent story. Türkiye is positioning itself simultaneously as a co-investor with Central Asian partners in boron and REE processing (leveraging the OTS institutional framework), as a competitive alternative to China in REE midstream capacity, and as the indispensable corridor guardian for the Middle Corridor route that bypasses both Russia and Iran.
What is new and underreported is the domestic industrial ambition underpinning this positioning. At the OECD Critical Minerals Forum in Istanbul in April 2026, Türkiye’s Energy and Natural Resources Minister Alparslan Bayraktar made a declaration that amounts to a strategic doctrine: “Having resources alone is no longer sufficient. You must be able to process them. Türkiye is building exactly that, combining extraction with deep processing capacity and high-tech industrial value creation.” The Beylikova REE project in Eskişehir province — described by Bayraktar as potentially one of the world’s largest deposits — already has a pilot facility operational, with plans for full industrial production including separation and processing of rare earth oxides for permanent magnets. A comprehensive Critical Raw Materials strategy is forthcoming from Ankara. This is not transit ambition. This is industrial policy.
The active Iran conflict and Hormuz disruption, which Bayraktar explicitly cited at the same forum, reinforces the Middle Corridor’s necessity. The corridor’s importance is no longer merely a response to the Ukraine war and the sanctioning of Russian routes — it is now being validated in real time by a second simultaneous crisis in maritime supply chains. Türkiye’s own boron endowment — approximately 73% of the world’s reserves — and the January 2026 mining sector MoU with Uzbekistan, which carries the weight of a presidential-level strategic council endorsement rather than a routine ministerial agreement, position Ankara as a co-architect of the post-Chinese supply chain rather than a passive transit facilitator.
The MINEX Asia Forum in Ankara on 24–25 June sits at exactly this intersection. Whether Türkiye chooses to deepen its processing and co-investment role, or remains primarily a corridor facilitator, will significantly shape the commercial geography of Central Asian mineral exports through 2030 and beyond.
Japan and South Korea — Quiet but Serious
Japan and South Korea have some of the most sophisticated critical mineral diversification programmes of any Western-aligned economies. Japan’s rare earth diversification after China’s 2010 export restriction was a decade-long institutional effort that produced real results. South Korea’s Korea Zinc committed USD 7.4 billion to new zinc refining in the US in 2025. Both countries are watching Central Asia closely and have existing relationships — South Korean companies are active in Kazakhstan’s energy and industrial sectors.
The EUISS paper notes that US and Japanese stockpiling and state-sponsored diversification efforts have been more successful than Europe’s — and that this risks disrupting the level playing field between downstream industries. Japan and South Korea’s engagement in Central Asia is likely to deepen significantly through 2030, and they may prove more reliable long-term partners than the US for the Central Asians, precisely because they have demonstrated institutional continuity in minerals diplomacy.
5. A 2030 Forecast: Honest Probabilities, Not Promotional Headlines
Based on the analysis above, the Forum’s assessment of where Central Asia is likely to stand in the global critical minerals picture by 2030 is as follows.
What Will Likely Have Happened
Kazakhstan will have advanced several significant critical mineral projects, particularly in uranium conversion and enrichment outside Russian supply chains, and in copper with one or two major Western-backed expansions. The Middle Corridor will carry materially higher volumes of goods, including mineral concentrates, with improved port and rail infrastructure — assuming the Georgia bottleneck is resolved, either through Tbilisi reversing course on Anaklia or through the TRIPP route becoming operational.
Uzbekistan will have attracted significant investment in gold and copper, building on its already-strong trajectory, and will have made progress on rare earth exploration, though commercial production at scale is unlikely before 2030.
Türkiye will have deepened its institutional role through the OTS and established at least one significant co-processing or co-investment arrangement with a Central Asian partner, most likely in boron derivatives or light rare earth oxides. The Beylikova project will have moved from pilot to initial industrial scale, giving Ankara credible processing capacity for the first time.
FORGE will have produced a shared pricing architecture and several concrete offtake agreements. However, because FORGE is a trade-rules framework rather than a pooled investment vehicle, the capital mobilisation it generates will be diffuse and bilateral rather than concentrated and strategic. The gap between FORGE’s institutional ambition and its actual investment footprint in Central Asia will remain a source of frustration.
Processing and refining capacity in Central Asia will have increased from its current low base, but will still represent a small fraction of what is needed to be genuinely China-independent. The midstream gap will have narrowed, not closed.
What Will Likely Not Have Happened
Central Asia will not have become a major supplier of processed rare earth materials to Western markets by 2030. The timeline from geological survey to commercial rare earth processing facility is typically fifteen to twenty years, and the clock has not been running long enough.
China’s dominance in processing will not have been broken. It may have been reduced at the margin — particularly for specific materials where Western-backed alternatives have been developed — but the structural advantage Beijing built over three decades cannot be unwound in five years.
A unified, coherent Western investment approach to Central Asia will not have materialised. The EU, US, Japan, South Korea, and Türkiye will continue to operate largely in parallel rather than in co-ordination, missing the synergies that a genuinely multilateral approach could generate.
The Wild Cards
Innovation as disruptor. The CFR’s February 2026 analysis argues that the US and its allies cannot out-mine or out-process China — and should not try. The alternative is to leapfrog China’s dominance through disruptive technologies: rare-earth-free magnets that eliminate the most geopolitically vulnerable inputs, mine tailings recovery that yields critical minerals from existing waste streams faster and more cheaply than new extraction, and e-waste recycling at industrial scale. If these technologies mature faster than expected, the strategic premium on Central Asian deposits could diminish even as geopolitical interest in the region remains high. For Central Asian governments, this is both a warning and an opportunity: the window in which their geological endowment commands maximum strategic attention may be narrower than current diplomatic momentum implies.
The China re-activation deadline. The October 2025 rare earth export controls suspended under the Xi–Trump deal are due to re-activate in November 2026 unless the deal is renewed. By the time of MINEX Eurasia in London on 30 November, this will be an immediate live issue. If Beijing re-activates, the urgency around alternative supply chains — including Central Asian ones — will intensify sharply. If it extends the suspension, the pressure on Western governments to maintain costly diversification programmes will ease, potentially slowing capital deployment.
Geopolitical escalation beyond Ukraine. The Hormuz blockade has already demonstrated that disruption can arrive simultaneously from multiple directions. Central Asia’s importance as both a resource base and a logistics corridor increases with every crisis in maritime routes. But escalation can also redirect capital and political attention away from the patient, long-horizon work of building supply chains.
Domestic political stability in Central Asia itself is not guaranteed. Kyrgyzstan in particular has experienced significant political turbulence. Investors will need to see sustained legal and regulatory reform to deploy long-term capital at scale.
Conclusion: The Window Is Open — But Not Indefinitely
Central Asia’s critical minerals moment is real. The geology is there. The geopolitical will is growing. The legal frameworks are improving in Kazakhstan and Uzbekistan. The Middle Corridor is becoming a genuine alternative logistics route — though its Georgian gateway is more fragile than most analyses acknowledge. And for the first time in a generation, Central Asian governments are actively seeking to diversify away from exclusive dependence on Chinese and Russian capital and markets.
But the picture is more complicated than the wave of optimistic policy documents suggests. FORGE is a trade-rules architecture, not a capital deployment machine — and the distinction matters for Central Asia. The EU has five companies on the ground despite its ambitious declarations. China’s export control détente has a hard expiry date in November 2026. And the CFR’s innovation thesis raises a genuinely uncomfortable question: what if the West’s best path to supply chain security runs through the laboratory rather than the mine shaft?
Türkiye’s OTS-anchored positioning adds a genuinely new dimension to this picture. An Ankara that is actively building REE processing capacity at Beylikova, institutionalising economic co-operation through the OTS, and serving as the corridor’s most reliable western terminus is not a passive transit hub. It is a co-architect of the post-Chinese critical mineral supply chain — if it chooses to be.
The businesses and investors who will win in this space are not those signing MoUs at ministerial summits. They are those who are currently doing the detailed geological work, building the processing partnerships, securing the offtake agreements, and positioning in the Middle Corridor logistics chain. They are thinking in fifteen-year horizons, not fifteen-month ones.
At MINEX Asia in Ankara, MINEX Europe in Ireland, and MINEX Eurasia in London, the Forum is convening these conversations — not about what Central Asia might become, but about what concrete steps, in what sequence, with what capital and what institutions, will make the difference between another wave of declarations and a genuine reorientation of global critical mineral supply chains.
The rocks are there. The question is whether the will, the capital, and the institutions are there too — and whether they will arrive before the window closes.
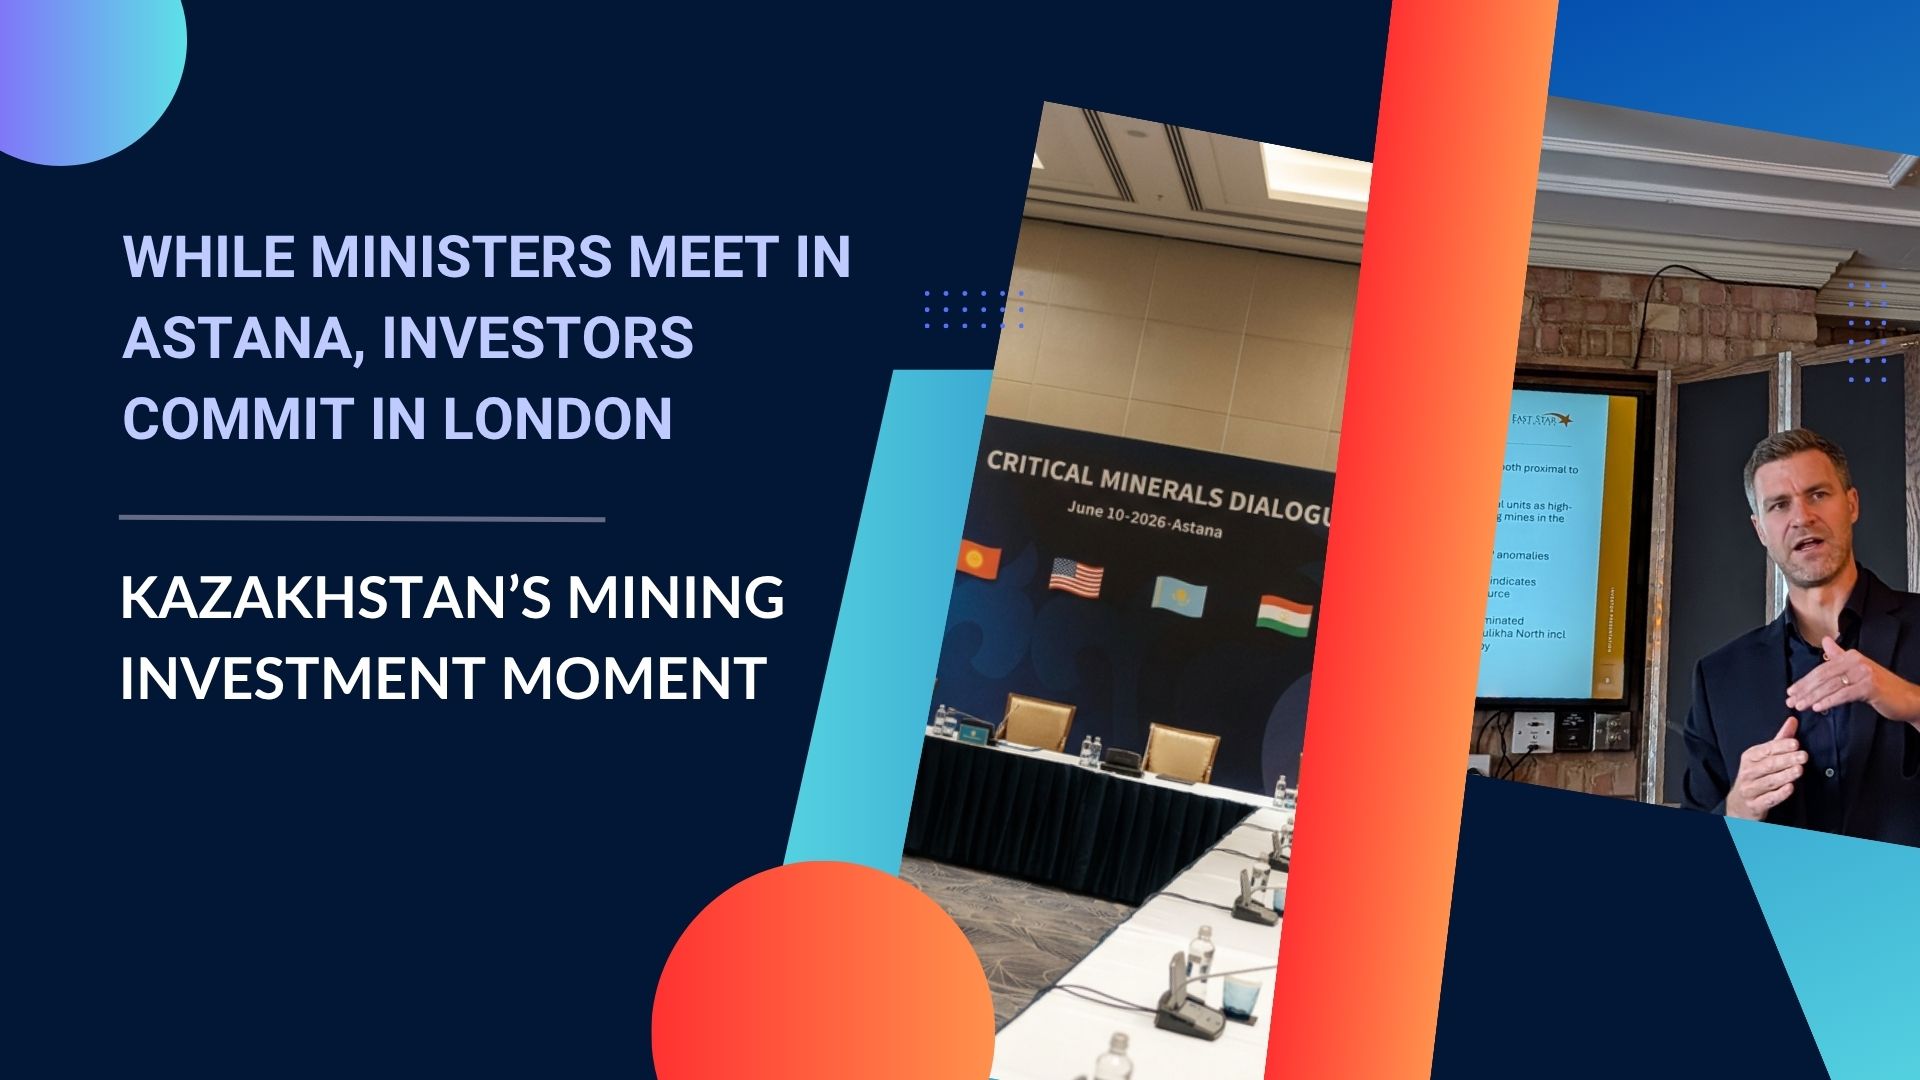
This week, Astana is hosting two very different conversations about Kazakhstan’s mining future.
In the official corridors, government delegations, US officials, and ministers from across Central Asia are gathered for high-level discussions. Grand statements are being made. Frameworks are being signed. Photographs are being taken.
On the other side of the world in a brick-walled London dining room — a rather different conversation is taking place. A small group of private investors is gathered around a screen, listening to a junior mining CEO explain, with disarming candour, exactly how he plans to turn a copper deposit in Kazakhstan into a billion-dollar producing mine. Without debt. Without dilution. And without losing sleep over capex blowouts.
These two conversations are not separate. They are, in fact, the same conversation — just conducted at different altitudes.
The Ground-Level Reality of Kazakhstan Mining Finance
East Star Resources CEO Alex Walker presented to investors with the kind of frankness that rarely makes it into official mining forums. His central message: the Verkhuba copper deposit in Kazakhstan is now funded to production, with Chinese EPCM powerhouse Xinhai taking 70% in exchange for carrying all development costs — an estimated US$65 million — to first copper.
East Star retains 30%, fully carried, with no debt obligation. Xinhai gains majority only when it has delivered US$50 million worth of equipment to site. Until that moment, East Star holds control.
“You do not get majority until you have sunk way more money into this,” Walker tells his audience.
It is a deal structure worth understanding carefully, because it illuminates something important about how junior miners are actually navigating the Kazakhstan opportunity in 2026 — and it is a long way from the headline-grabbing announcements coming out of this week’s official forums.
The Xinhai model — a Chinese EPCM contractor taking equity in exchange for funded development — is not new. But its scale and pace are accelerating. Xinhai now claims over 2,500 projects delivered globally, with more than US$42 million committed to ASX and LSE-listed companies for feasibility and construction in 2025 alone. They manufacture their own processing equipment, manage their own supply chains, and have demonstrated the ability to build a 1.5 million tonne per annum processing plant in Kazakhstan in under twelve months.
Walker is characteristically direct about the implications: “I visited their factory in Yantai. They make everything — the rubber liners that go in your crushing plants. That means you are not reliant on where you sit in a queue for your equipment provider. You manage your entire supply chain.” When Xinhai told him they thought they could deliver Verkhuba within a compressed timeline, he said, he believed them.
For a junior miner navigating the gap between resource and production — the graveyard of so many promising projects — this kind of vertically integrated partner is genuinely transformational. Walker is blunt about which risks he had effectively eliminated: financing, capex blowouts, and timing. Three of the five classic killers of junior development projects, struck off in a single deal.
The Copper Market Context Nobody Is Ignoring
Walker touched on the macro backdrop, referencing a conversation with senior Goldman Sachs mining analysts about the copper deficit forming in the rest-of-world, non-US market. The figures are striking. Goldman Sachs now projects a deficit of over 640,000 tonnes in ex-US copper markets in 2026 — a number revised sharply upward from a prior estimate of just 60,000 tonnes, driven largely by US front-loading of copper imports ahead of potential tariffs. J.P. Morgan adds a 330,000-tonne deficit projection of its own, while even the historically conservative International Copper Study Group has swung from forecasting a 209,000-tonne surplus in late 2025 to a 150,000-tonne deficit by May 2026.
The convergence of major institutional forecasters on a significant 2026 deficit is the backdrop against which Walker’s geopolitical point lands hardest. Copper from the DRC loaded onto a ship can be diverted mid-voyage to capture a premium on the COMEX in New York. Copper that travels by rail from Kazakhstan cannot. Its destination is fixed. In a world where tariffs and trade route disruption are rewriting commodity flows in real time, Kazakhstan’s landlocked geography – once a liability – is becoming a structural advantage for certain end markets, particularly China. The supply cannot be diverted. It simply arrives.
The Questions Investors Are Actually Asking
The sharpest exchanges of the meeting came during questions. One investor raised the spectre familiar to anyone who has backed a junior miner in a joint venture with a larger partner: what stops the big partner from simply putting the project on ice when it suits them?
Walker’s answer was layered. First, the deal structure itself: Xinhai only achieves majority when equipment worth US$50 million has been delivered to site. If they walk away before that, East Star keeps its majority and a significant amount of delivered capital. “They’d be selling US$50 million worth of equipment and still getting a good return on capital,” he noted. “So we’ll figure out how to build it ourselves.”
Second, he made a pointed commercial observation: Xinhai wants East Star to be their business development partner in Kazakhstan, bringing them more deals. Betraying a partner publicly would destroy that franchise. “The first group they screw over — that business model is shut,” he said. “That’s why I don’t think they’d do it.”
A second question probed the structure of East Star’s 30% retained interest more sharply: does the company actually own 30% of the project, or is it simply entitled to 30% of the copper? And crucially, who controls the surplus capital once the mine is producing?
Walker confirmed that East Star owns 30% of the project entity, with marketing rights for approximately 30% of production. On dividend distribution, he was direct: under the shareholders’ agreement with Xinhai, dividend policy is a reserved matter requiring mutual agreement — the majority shareholder cannot unilaterally determine how cash is deployed. “Dividend distribution is one of those matters that needs a vote from both sides,” he said. Whether the cash ultimately flows back to shareholders or is redeployed into new projects — perhaps towards building a 300,000-ounce-per-year gold mine with Endeavour — is a question for later. The structural protection, he argued, is real.
It was, collectively, the answer of someone who has read enough JV agreements to know exactly where the traps are.
AI and the New Exploration Toolkit
One detail from the evening deserves particular attention, and it speaks to how the competitive landscape for junior miners in Kazakhstan is changing.
East Star’s porphyry gold exploration programme — the Snowy and Piket licences on the Balkash-Ili magmatic arc — was initially funded through a grant from the BHP Xplor programme, which Walker described as “a highly competitive programme: 600 applicants, 6 accepted.” The programme is explicitly oriented around applying advanced analytical techniques — including AI-driven target generation — to early-stage exploration. East Star’s selection is a mark of technical credibility that carries weight with institutional investors.
The broader context matters here. Kazakhstan’s government has been investing heavily in the digitalisation of its geological archive — over 97% of primary geological information, approximately 250 terabytes of data, has now been scanned and consolidated into a unified system. An AI-powered platform has been developed to automatically process this archive, extract coordinates, and generate subsurface geological models. Officials describe the technology as significantly reducing data processing time and improving the quality of exploration decisions.
For companies like East Star, operating across some of Kazakhstan’s most prospective but underexplored belts, this convergence of digitised state geological data and AI-assisted targeting represents a genuine step-change in the speed and cost of identifying drill-ready targets. The question of where the next Nikolskoye or Verkhuba might be hiding is increasingly one that algorithms, not just geologists, are helping to answer.
The Regulatory Picture: Nuance Required
One of the most interesting questions of the meeting came from an investor who had been tracking changes to Kazakhstan’s mining regulatory framework. The question concerned a reported increase in the threshold for mandatory government approval of ownership changes in mining companies, and the role of the national mining company Tau-Ken Samruk in new joint ventures.
The regulatory picture here is genuinely nuanced, and worth examining carefully.
Kazakhstan’s December 2025 amendments to the Subsoil and Subsoil Use Code were primarily aimed at digitalisation, transparency, and strengthening strategic investor incentives. Separately, amendments signed by President Tokayev also tightened state control in the uranium sector specifically, raising certain transfer thresholds and granting Kazatomprom priority rights over uranium exploration licences.
As for Tau-Ken Samruk — the state’s national mining company and a subsidiary of the sovereign wealth fund Samruk-Kazyna — Chambers and Partners’ 2026 Kazakhstan Mining guide notes that the government is actively seeking to restore Tau-Ken Samruk’s priority rights for obtaining exploration and mining licences for critical minerals, a right that had previously been removed as part of earlier liberalisation efforts. “We expect this priority right to be restored in 2026,” the guide notes, describing it as a deliberate effort to increase the state’s foothold in the early stages of the critical minerals supply chain.
The direction of travel is clear, even if the precise mechanics are still being finalised: Kazakhstan is simultaneously offering incentives to attract international capital and tightening state participation rights in the assets that matter most. For investors in junior miners operating here, this duality is not a contradiction — it is the operating environment. Understanding it, and structuring agreements, accordingly, is the price of entry.
This is precisely the kind of regulatory intelligence that MINEX Eurasia Forum — convening in London on 30 November as part of London Mining Week — exists to provide. The forum brings together mining investors, operators, legal practitioners, and government representatives from across the region to examine exactly these dynamics: where is capital coming from, on what terms, and under what regulatory conditions?
The Endeavour JV: A Different Model, Same Logic
East Star’s joint venture with Endeavour Mining – a US$25 million exploration programme with one of the world’s top ten gold producers – follows a different but structurally similar logic. Endeavour funds exploration through to pre-feasibility study, earning up to 80% along the way. East Star manages the JV until Endeavour reaches 51% and is carried through to PFS completion.
Again: no dilution beyond agreed thresholds, no unilateral majority until capital milestones are met, and a world-class operator bearing the exploration and development risk.
Walker’s reference point is Independence Group in Western Australia — a company that held a minority in what became the Tropicana gold project with AngloGold, eventually building that stake into hundreds of millions of dollars of annual cash flow. The analogy is instructive: the value is not in owning the whole mine. It is in owning the right percentage of the right mine, with the right partner, under the right agreement.
Walker put it simply: “If we have 20% of something that Endeavour is building, even with financing, that’s a billion-dollar company for just East’s percentage. That’s something I’m really excited to maintain.”
This philosophy is increasingly evident among the better-managed junior miners operating in Central Asia. The era of the go-it-alone junior – raising capital dilutively on the back of exploration results, lurching from drill hole to drill hole – is giving way to something more sophisticated: structured, partner-funded development with clear milestone-based governance.
MINEX Asia and the Longer Arc
For those who follow the MINEX forum series closely, none of this comes as a surprise. Over more than a decade, MINEX Eurasia events in London have documented and debated the evolution of mining investment in Central Asia and the Caucasus — the shift from Soviet-era brownfield rehabilitation to greenfield discovery, the growing role of Chinese EPCM capital, the fitful but real improvement in regulatory environments, and the persistent challenge of converting geological endowment into investable projects.
What is new in 2026 is the intensity of the moment. The critical minerals agenda — driven by the energy transition, by great power competition over supply chains, and by the explicit industrial policy of both the EU and the US — has focused international attention on Kazakhstan, Kyrgyzstan, Uzbekistan, and their neighbours in a way that was not true even three years ago.
The question that MINEX Asia 2026, convening in Ankara this month, is already pressing — and that MINEX Eurasia Forum will continue to examine in London in November — is whether this intensified international attention translates into genuinely diversified investment, or whether the structural realities of Kazakhstani mining (Chinese EPCM dominance, evolving state participation requirements, infrastructure constraints) mean that the beneficiaries of the critical minerals boom will ultimately be narrower than the official narrative suggests.
The Real Work
Back in that London dining room, the questions kept coming. Minority shareholder protection. Dividend policy. The role of assay labs on site. The timeline to production. Each one answered with the same register: direct, detailed, and unspun.
It was a window into the real sophistication now required to operate as a junior miner in Kazakhstan. The geology is compelling. The copper market backdrop is as strong as it has been in years. Chinese EPCM capital is available, at scale, on terms that can work for a well-advised junior. The regulatory environment, for all its complexity, is navigable.
But the deals that will create value – the ones that will turn exploration licences into producing mines and producing mines into returns for investors — will be won or lost on the quality of the agreements, the rigour of the governance structures, and the acuity of the people sitting across the table.
Ministers may gather for the photographs, but the real work happens away from the cameras.
More than 50 US companies gathered in Bishkek on 4 February for the second B5+1 Business Forum, the private-sector counterpart to the C5+1 diplomatic format linking the United States with Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan and Uzbekistan, in what US Special Envoy Sergio Gor described as the largest and most comprehensive American commercial delegation ever to visit Central Asia.
The forum, co-organised by the Kyrgyz government and the Center for International Private Enterprise, is designed to bring companies and policymakers together to identify investment barriers and propose cross-border regulatory changes. The Bishkek agenda centred on reviewing progress against the 21 private-sector recommendations produced at the inaugural B5+1 forum in Almaty in March 2024, and setting priorities for the next phase of work.
Gor framed the forum as a deliberate shift in Washington’s approach to Central Asian engagement. “The private sector, not intergovernmental agreements, will become the key instrument of interaction,” he said, identifying electronic commerce, artificial intelligence, critical minerals, agriculture and transport infrastructure as priority areas. He also referenced the TRIPP transport corridor as a vehicle for connecting Central Asia through the South Caucasus to global markets — “a historic opportunity to strengthen economic integration and long-term prosperity across the region.”
Kazakhstan’s Industry and Construction Minister Yersaiyn Nagassayev used the event to make the case for treating Central Asia as a single investment market rather than a collection of bilateral relationships. He noted that more than 600 US companies currently operate in Kazakhstan and said foreign investors increasingly assess the region as a unified commercial space with aligned regulations and investment conditions.
Kyrgyzstan used the forum to highlight its domestic economic performance within that regional context. First Deputy Chairman Daniyar Amangeldiyev said Kyrgyzstan’s economy grew 11.1% in 2025, which he described as one of the highest growth rates in the region. Gor also met separately with Kyrgyz President Sadyr Japarov to discuss economic cooperation, trade expansion and investment attraction.
The B5+1 is being positioned as a standing mechanism with an ongoing cycle of working groups, private-sector proposals and annual meetings, rather than a one-off event. Any updated recommendations from the Bishkek forum are expected to be published following additional consultations rather than issued as immediate communiqués at the event itself.
The United States opened a new round of high-level critical minerals talks with all five Central Asian governments in Astana on 10 June, with US Special Envoy for South and Central Asian Affairs Sergio Gor delivering a pointed message that Washington has decided to significantly deepen its engagement with a region it acknowledges has not received the attention it deserves.
“We care about this region, we want to be involved with this region, we want to identify win-win situations for the United States and your nations,” Gor told the first in-person C5+1 Critical Minerals Dialogue, held at The Ritz-Carlton in Astana and attended by officials from Kazakhstan, Kyrgyzstan, Tajikistan, Turkmenistan and Uzbekistan. The session covered geological exploration, surveying and mapping, mining and processing, and global value and supply chains.
Gor said the Trump administration’s increased focus on Central Asia reflects a clear strategic calculation. “There’s a reason we’re sitting at this table and not at another table around the world. It’s because this is where we have identified trusted partners,” he said. He pointed to the US International Development Finance Corporation as a key instrument, saying it was preparing to invest in critical minerals, telecommunications and Trans-Caspian infrastructure, and saw potential to transform the region’s mineral deposits into “the foundation of a new wave of industrialisation.” He added that Washington stands behind American companies operating in the region: “There is no such thing as a deal too small.”
Kazakhstan’s Industry and Construction Minister Yersaiyn Nagassayev framed the dialogue as a continuation of the bilateral track opened during President Tokayev’s November 2025 visit to Washington, when a critical minerals memorandum of understanding was signed in Tokayev’s presence by Nagassayev and US Commerce Secretary Howard Lutnick. He cited the Cove Capital tungsten cooperation — involving the Northern Katpar and Upper Kairakty deposits in Karaganda Region — as a concrete follow-up to those agreements.
Nagassayev presented Kazakhstan’s case for deeper partnership on multiple dimensions. The country holds more than 9,500 mineral deposits, including over 100 containing rare and rare earth metals. Investment in geological exploration has tripled since 2018 to exceed $1 billion annually, and the country has adopted the CRIRSCO international reporting standards since 2024. Major international companies including Rio Tinto, Barrick Gold, First Quantum, Ivanhoe, Teck, Fortescue and Cove Capital have entered the market.
Crucially, Nagassayev emphasised that Kazakhstan seeks to be a value-added partner rather than a raw material exporter. “Kazakhstan is interested not only in exporting raw materials, but also in developing joint production facilities, technology transfer, workforce training, and scientific cooperation,” he said, proposing cooperation in processing, industrial clusters, advanced materials and research centres. He also linked the critical minerals agenda to the Middle Corridor transport route as a mechanism for diversifying Eurasian connectivity and ensuring reliable supply chain flows.
Gor met President Tokayev shortly before the dialogue session, and Kazakhstan’s Foreign Ministry said the bilateral talks with Foreign Minister Yermek Kosherbayev covered economic partnerships, innovation, artificial intelligence, education, transport, logistics and the implementation of Tokayev-Trump agreements from November 2025.
Japan’s Atomic Energy Agency and Kazakhstan’s National Nuclear Centre have signed a memorandum of cooperation to undertake a fourth phase of the EAGLE project — a long-running joint research programme on core safety experiments for sodium-cooled fast reactors — marking a new chapter in nuclear technology collaboration between the two countries.
NNC RK Director General Erlan Batyrbekov and JAEA President Masanori Koguchi signed the agreement, which initiates the EAGLE-4 project covering several in-pile experiments at NNC RK’s IGR research reactor, twelve out-of-pile experiments at the EAGLE test bench, and a series of small-scale tests. The main objectives are to test fuel assemblies for advanced Japanese Generation IV reactors, conduct research at NNC RK facilities, and provide a scientific basis for safety assessment of advanced nuclear technologies. NNC RK is in discussions with JAEA on extending the project through to 2031.
The EAGLE programme began in the early 2000s and has now completed three phases. Across those phases, approximately 200 preparatory tests, two intermediate-scale and nine full-scale reactor experiments, and more than 65 out-of-pile tests were carried out, collectively confirming that molten fuel is promptly discharged from a reactor core in the event of a severe accident — a key safety finding for the development of next-generation sodium-cooled fast reactor technology.
The programme sits within Japan’s broader strategic effort to revive fast reactor development after a prolonged pause. Japan’s government decommissioned the Monju sodium-cooled fast reactor in 2016 following a series of technical problems, including a sodium coolant leak in 1995. A strategic roadmap adopted by the Cabinet in 2018 and revised in 2022 selected sodium-cooled fast reactors as the target for a demonstration reactor conceptual design, with a demonstration fast reactor planned for operation by 2050.
Fast neutron reactors offer substantially more efficient use of uranium resources than conventional power reactors and can burn actinides — characteristics that make them attractive for long-term energy security and waste management. For Kazakhstan, the EAGLE collaboration provides both scientific engagement and a demonstration of the country’s growing role as a partner in advanced nuclear research, complementing its dominant position as the world’s largest uranium producer.
Kazakhstan is undergoing a fundamental repositioning in global resource markets, moving from a country primarily associated with oil, gas and bulk commodities to one increasingly recognised as a strategic supplier of uranium, rare earth elements, tungsten and other critical minerals essential to advanced manufacturing, defence systems and the energy transition.
Three themes dominated Central Asian mining capital markets over the past week: strategic developments at Kazatomprom, shifting ownership dynamics at Eurasian Resources Group, and US government-backed financing for Kazakhstan’s tungsten projects.
Kazatomprom, the world’s largest uranium producer, reinforced investor confidence by announcing the partial redemption of $100 million in long-term bonds — a signal of balance sheet strength during one of the strongest uranium markets in decades. The company’s market value has grown to approximately $19 billion, more than six times its IPO valuation, as nuclear energy regains strategic favour across Europe, North America and Asia. Management expects production growth in 2026 while maintaining a disciplined approach that prioritises value creation over aggressive volume expansion. State ownership through Samruk-Kazyna remains an important factor for investors assessing long-term strategic direction.
ERG, one of the world’s largest producers of ferroalloys, iron ore, aluminium, copper and cobalt, attracted attention following ownership changes involving a significant stake. Investors interpreted the development as part of a broader trend toward greater government influence over strategically important mining assets — a pattern that extends beyond corporate governance given ERG’s critical minerals portfolio. The group previously accounted for approximately 20% of global gallium production, a metal classified as strategic by both the US and EU for its applications in semiconductors, telecommunications equipment and advanced electronics. ERG’s growing importance to global resource security has elevated it from a traditional mining group to a company viewed as critical infrastructure within global supply chains.
On the tungsten front, a company developing the Northern Katpar and Upper Kairakty deposits — among the largest tungsten developments outside China — has reportedly sought an additional $400 million in US government-backed financing, supplementing previous expressions of interest valued at up to $1.6 billion. The scale of international backing reflects how strategic mineral projects are increasingly evaluated through a national security lens rather than as conventional commodity investments.
Both Kazakhstan and Uzbekistan are pursuing policies designed to move beyond raw material exports, attracting investment in processing, refining and downstream industrial operations to capture a greater share of the value chain domestically. This strategic shift mirrors approaches seen in other resource-rich regions seeking long-term economic resilience, and creates new investment opportunities across multiple segments of the mining and industrial ecosystem.
The US House of Representatives has passed the Developing Overseas Mineral Investments and New Allied Networks for Critical Energies Act — known as the DOMINANCE Act — bipartisan legislation designed to reduce American dependence on China for critical minerals and build more resilient supply chains through expanded cooperation with allied and partner nations.
The legislation was introduced by Representatives Ami Bera and Young Kim of California. It addresses four main pillars: expanding cooperation with allies and partners on mineral security, supporting strategic mineral and energy investments, strengthening US energy diplomacy, and investing in the workforce and expertise required to build diversified and resilient critical mineral supply chains.
Bera framed the bill as a matter of national security that transcends partisan lines. “Today, China controls roughly 90% of global rare earth processing capacity, creating a strategic vulnerability that Beijing has shown it is willing to exploit through export restrictions and economic coercion,” he said. “The United States must continue expanding domestic mining, processing, refining, and recycling capacity, but we cannot build secure and resilient supply chains alone.”
The legislation has attracted support from a broad coalition spanning national security, manufacturing, technology, energy and policy organisations, including the National Association of Manufacturers, the Information Technology Industry Council, the Bipartisan Policy Center Action, the Climate Leadership Council and the US-ASEAN Business Council.
The bill now moves to the Senate. Its passage through the House reflects growing bipartisan consensus that securing critical mineral supply chains is a strategic imperative requiring both domestic capacity building and systematic allied engagement — a recognition accelerated by China’s progressive tightening of export controls on gallium, germanium, graphite, antimony and rare earth elements over the past two years.
China has built a commanding lead in the global competition for critical minerals that its rivals are only beginning to take seriously, and the strategies required to challenge that dominance will need to go well beyond capital deployment, according to an analysis by Veridicor that frames the contest as a “Great New Game” of geopolitical rivalry over strategic resource access.
The scale of China’s position is striking. The country controls 60% of global rare earth mining and 87% of refining, 64% of graphite mining and 100% of its refining, 65% of cobalt refining and 40% of copper refining. This dominance has been built deliberately over 25 years through a strategy that understands critical minerals as integrated value chains — combining mining, refining and infrastructure — rather than isolated extraction activities. The integration of critical minerals policy with broader industrial strategy has delivered additional competitive advantages, including global leadership in solar power and electric vehicle manufacturing.
The macroeconomic context driving urgency is severe. Demand projections point to significant supply gaps in the medium and longer term. Estimates suggest the world needs to mine as much copper in the next 50 years as it has in the last 5,000 years — a challenge that Wood MacKenzie estimates will require $2.3 trillion in net new mining investment globally to address. The pattern repeats across most critical minerals, with supply gaps both looming and material.
The analysis argues that for the US, Europe and others to challenge China’s dominance, differentiation rather than imitation is the key strategic imperative. “Writing checks won’t be enough to change the critical minerals balance that China has earned,” the paper states. The proposed differentiator is excellence in responsible mining practices — an area where Western actors can build genuine competitive advantage in ways that China’s state-driven model has not prioritised.
The logic operates through several mechanisms. Communities, Indigenous nations and other stakeholders in mining regions can accelerate or obstruct permitting processes depending on the trust relationships developed with project operators. Responsible practices that earn genuine social licence reduce conflict risk and improve the stability and predictability of mineral flows from operating mines. Artisanal and small-scale miners represent a particularly underutilised opportunity: these operators are often early exploration indicators, can be integrated into formalised supply chains through professionalisation and offtake agreements, and their collaboration with large mines reduces conflict risk while boosting aggregate productivity.
The financing model proposed — Stakeholder Prosperity Bonds, developed as a subset of the broader sustainability bond market — combines artisanal mining professionalisation, improvements to large mine operations, infrastructure development, small-scale processing facility construction and regional capacity building into a single regional investment vehicle. The approach is framed not as a cost centre but as a generator of bankable value through productivity gains, risk reduction and regional development.