Website: Asia.com

  • Strategic Gains in Tungsten and Rare Earths: Almonty, Aurubis, and MP Materials Thrive Amidst Political Support

    Strategic Gains in Tungsten and Rare Earths: Almonty, Aurubis, and MP Materials Thrive Amidst Political Support

    In a landscape marked by increasing geopolitical tensions and a growing emphasis on domestic production, Almonty Industries, Aurubis, and MP Materials are emerging as key players in the mining sector, benefiting significantly from substantial financial backing from Washington and Brussels. The recent US decision to prohibit the export of tungsten waste and scrap without a licence highlights the strategic importance of tungsten, particularly as Almonty Industries prepares to ramp up operations at its Sangdong mine in South Korea. This mine, which is set to begin processing in July, boasts nearly 140,000 tonnes of ore valued at approximately USD 68 million. Almonty is well-positioned to address the ongoing supply shortage, with a remarkable 498% revenue increase to CAD 43 million and a gross margin of 60.7% reported in their latest quarterly figures. The company’s robust cash position of CAD 1.2 billion, bolstered by an USD 800 million senior notes offering, allows for significant investments, including a planned expansion of production capacity.

    Meanwhile, Aurubis, the Hamburg-based copper smelter, is navigating a complex year, marked by high metal prices and strong demand for sulphuric acid, alongside delays in its US expansion project. The company reported a 31% increase in operating earnings before tax (EBT) to EUR 374 million for the first nine months of the 2025/26 financial year, driven by rising copper prices and increased revenue from sulphuric acid. However, setbacks in the Richmond project have tempered investor enthusiasm, with full ramp-up now expected to be delayed by six months.

    On the other hand, MP Materials is showcasing operational progress with a 41% increase in NdPr production and a 127% rise in sales volume. Despite a GAAP loss of USD 20.3 million, the company is securing future revenues through strategic supply contracts with the US Department of Defense, which guarantees a minimum price for NdPr over the next decade. The company is also making strides in its magnet production, with expectations of over 1,000 tonnes of NdPr production in the upcoming quarter.

    The political support from both the US and EU is proving beneficial for these companies, as they navigate the complexities of the market. Almonty Industries is leveraging its strategic tungsten asset, while Aurubis is focused on solid operational performance despite expansion delays. MP Materials is capitalising on lucrative contracts and production advancements, although its share valuation remains a concern as market expectations may be overly optimistic. Overall, while the commodities boom is celebrated in stock markets, the path to sustained success for these companies is fraught with challenges and uncertainties.
  • Chinese Company to Extract 20 Tonnes of Silver Annually in Kazakhstan

    Chinese Company to Extract 20 Tonnes of Silver Annually in Kazakhstan

    The Liaoning Hongda Group, a Chinese mining company, has commenced the construction of the Burabay-Zhalgyzagas mining and processing plant in the Janakorgan district of Kazakhstan’s Kyzylorda region. The facility is set to produce 20 tonnes of silver and 210,000 tonnes of lead-zinc concentrate annually upon its completion in 2028. The project represents a significant investment in the region, with a total cost of 138 billion tenge, and is expected to create over 550 new jobs.

    During the groundbreaking ceremony, regional akim Murat Yergeshbayev highlighted the project’s potential to stimulate economic growth and diversify the local economy. He expressed gratitude to Liaoning Hongda Group for their commitment to such a large-scale and modern initiative. The project aligns with President Kassym-Jomart Tokayev’s directive to transition Kazakhstan to a new investment cycle, focusing on modern production and optimising regional economic potential.

    Currently, drilling works are underway to expand the mineral resource base of the site, alongside the construction of access roads and the establishment of construction sites. The project also includes plans for connecting the plant to electrical grids to ensure a reliable power supply.

    Liaoning Hongda Group has previously announced plans to invest $1.3 billion in the development of two lead and zinc deposits in the Janakorgan district, which will include two underground mines and two processing plants with a combined capacity of 8 million tonnes of ore per year, as well as a full-cycle metallurgical plant.

    Exploration activities at the deposits date back to the 1980s, with detailed surveys conducted between 2010 and 2012. The reserves are classified as C2 category, with forecast resources rated as P1. The average content of the deposits is reported at 2.01% zinc and 1.62% lead, with geologists noting the potential for resource growth at greater depths.

    Once operational, the new complex is projected to produce 420,000 tonnes of zinc and 220,000 tonnes of lead annually, which would significantly surpass the output of Kaz Zinc, making it potentially the largest producer of lead and zinc in Central Asia. The Chinese company has already invested approximately 9 billion tenge in geological exploration, utilising 15 drilling rigs during the process.


  • East Star Resources Partners with Kazakhstan’s Nova Ltd for Major Copper Project Development

    East Star Resources Partners with Kazakhstan’s Nova Ltd for Major Copper Project Development

    East Star Resources (EST), a British company operating in Kazakhstan, has announced a significant partnership with local firm Nova Ltd to establish a joint venture aimed at developing the Rulikha copper project in the East Kazakhstan region. The project will be operated by Orion Development Ltd, which has been tasked with the technical execution of the project, including resource confirmation, feasibility studies, permitting, construction, and the eventual commencement of production. This strategic collaboration is noteworthy as it allows East Star to advance the project without requiring additional funding from its side.

    Nova Ltd, specifically registered in the Astana International Financial Centre (AIFC) to finance the joint venture, boasts shareholders that include prominent figures in Kazakhstan’s natural resources sector. While the identities of these shareholders have not been officially disclosed, speculation suggests they may include notable entrepreneur Aigazy Kusaikov and businessman Askhat Omarov, the latter being associated with billionaire Aydin Rakhimbaev.

    Orion Development, also registered in the AIFC, brings a wealth of experience in the construction and operation of copper mines and processing facilities in Kazakhstan. This team is expected to leverage its expertise to ensure the successful development of the Rulikha project.

    The Nova and Orion teams have previously developed two copper assets in Kazakhstan: the Karshyga and Kamkor projects. The Karshyga site was acquired in February 2017 from British firm Orsu Metals, which had reported reserves of approximately 4.6 million tonnes of ore with an average copper content of 3.02%. Following the acquisition, the team designed, financed, and constructed a copper processing plant, which began operations in 2018, leading to a significant increase in annual revenue.

    The Kamkor project, acquired in 2021, contained around 15.7 million tonnes of copper ore with an average metal content of 0.65%. Construction of its processing facility commenced in January 2022, and it was operational by April 2023, with capital expenditures amounting to $14 million. The facility’s capacity was later increased by approximately 50%, resulting in a substantial rise in project revenues.

    With the Rulikha project, the initial phase requires the partner to drill at least 3,000 meters or fund $1.5 million worth of work. East Star has already secured drilling permits for the main site and plans to initiate operations in the third to fourth quarters of 2026. As the project progresses, Nova’s stake in the joint venture will increase, potentially resulting in a final structure where Nova holds either 75% or 65% of the venture, depending on the financial arrangements.

    Located about 33 km from the Upper Uba project, another copper initiative by East Star, the Rulikha project’s geological exploration target is estimated at a maximum of 23 million tonnes of ore with an average copper equivalent grade of 2.4%. This development marks East Star’s second copper project in Kazakhstan, following the entry of Chinese investors into the Upper Uba project, where East Star aims to retain a 30% stake post-production commencement, while for Rulikha, it aims for a stake between 25% and 35%.


  • China Discovers Major Uranium Deposit but Continues to Rely on Kazakhstan Supplies

    China Discovers Major Uranium Deposit but Continues to Rely on Kazakhstan Supplies

    China has announced the discovery of a significant uranium deposit in the Jingchuan area of Inner Mongolia, estimated to contain up to 30 million tonnes of uranium. This find could potentially bolster China’s domestic resource base for nuclear energy, reducing its reliance on foreign supplies in the long run. However, despite this promising discovery, China remains one of the largest purchasers of uranium from Kazakhstan, accounting for 44% of Kazatomprom’s revenue from natural uranium sales in 2025.

    Kazatomprom, Kazakhstan’s national atomic company, reported a revenue of 1.803 trillion tenge for 2025, showing little change from the previous year. The company experienced a decline in net profit, dropping from 1.13 trillion to 807 billion tenge, while the average selling price of uranium fell from $69.5 to $65.3 per pound due to a 14% decrease in the average annual spot price. However, the volume of natural uranium sales increased by 11%, with China being the primary buyer, contributing 797 billion tenge to Kazatomprom’s revenue.

    In comparison, uranium sales to the United States rose from 143 billion to 204 billion tenge, while sales to Russia decreased from 253 billion to 218 billion tenge. China’s interest in Kazakhstan’s uranium extends beyond mere purchases; Chinese entities are actively participating in several uranium projects within Kazakhstan, including the Zarichnoye and Khorasan-U projects, the latter located in the Kyzylorda region and notable for its Chinese involvement.

    Kazakhstan’s status as a leading global uranium producer with one of the largest resource bases makes it a crucial partner for China. Despite a decrease in net profit and average selling prices, Kazatomprom’s operational cash flow increased from 516 billion to 810 billion tenge in 2025. Shareholders received dividends of 1,264 tenge per share, up from 1,213 tenge the previous year, while capital expenditures rose from 190 billion to 256 billion tenge. Additionally, the uranium extraction tax in Kazakhstan increased from 6% to 9% as of January 2025, with a differentiated scale based on extraction volumes and uranium prices set to be implemented in 2026.


  • Digital Transformation in Central Asian Geology: Platforms, AI, and Workforce Challenges

    Digital Transformation in Central Asian Geology: Platforms, AI, and Workforce Challenges

    The mining industry is increasingly recognising the importance of digitalisation, particularly in the field of geology, which is one of the most knowledge-intensive sectors. However, the pace of digital transformation in Central Asia is lagging behind the demands of the business and global investment markets. This article explores how Kazakhstan and Uzbekistan are addressing this issue through strategic programmes aimed at expanding their mineral resource bases.

    In the competitive landscape of critical minerals, the integration of digital technologies is essential for success. From forecasting and assessing mineral reserves to product exportation, the mining industry must embrace digital solutions. Despite the existence of scientific literature and discussions at strategic business forums, the application of AI, big data, and machine learning remains limited to isolated practices. A systematic approach is needed to harness geological information effectively, and both Kazakhstan and Uzbekistan are developing their own transformation scenarios.

    Kazakhstan has made significant strides since the launch of a unified subsoil use platform in 2025. By August 2026, the country completed the digitisation of geological information, processing over 4.8 million archival materials, marking a revolutionary step that could serve as a model for other Central Asian nations. Meanwhile, Uzbekistan announced the creation of a National Geological Data Base, aiming to digitise 36,000 reports and establish a Centre for Technological Transformation, which is expected to double the quality and speed of geological data generation and modelling.

    Experts at the MINEX Kazakhstan 2026 forum highlighted that the digitalisation of geology is a matter of survival rather than prestige for Central Asian countries. Traditional methods are no longer sufficient to ensure growth or replenish mineral resources, especially as older deposits are depleted and ore quality declines. The key challenge is not just the quantity of reserves but the effective management of geological data and decision-making based on that data. Currently, only 21% of geologists in Kazakhstan have access to modern data transmission networks, significantly delaying project timelines.

    A critical barrier to digitalisation is the skills gap, particularly in the intersection of IT, big data, and geology, which are essential for quality predictive analysis. The reliance on foreign software and the lack of local intellectual resources hinder the rapid development of homegrown solutions. The competition for skilled professionals in IT and data science is fierce, with companies vying for talent by offering lucrative salaries.

    Another significant obstacle is the absence of unified standards for geological information, although Kazakhstan has made progress in this area. Without the integration of historical data, its value diminishes, and investors are less inclined to engage. To improve the situation, experts suggest a shift in focus towards innovative priorities within the industry.

    The Ministry of Industry and Infrastructure Development of Kazakhstan has begun practical steps to implement neural network models in geology, collaborating with the National Geological Service and Astana Hub. This initiative is supported by EPAM Kazakhstan and aims to address the skills shortage by training geologists in big data and machine learning techniques.

    The article also discusses various applications of AI in modelling mineral deposits and the use of digital tools in geophysical exploration across Kazakhstan and beyond. Companies are employing advanced methods such as 3D modelling and machine learning to enhance the accuracy of geological assessments and streamline operations. As Kazakhstan embarks on a state programme to study 20 areas for detailed geological surveys, the integration of IT tools will be crucial for achieving its resource potential.

    In conclusion, Central Asia is undergoing a significant transformation in its geological sector, which will ultimately determine the success of the entire mining industry in the region. The future of geology in Central Asia hinges on the successful implementation of digital technologies and the establishment of an open ecosystem for geological information, positioning countries like Kazakhstan and Uzbekistan as high-tech hubs in the Eurasian landscape.


  • Advancements in Geological Exploration and Risk Management in Central Asia

    Advancements in Geological Exploration and Risk Management in Central Asia

    The demand for critical minerals is reshaping the role of Central Asia, particularly Kazakhstan and Uzbekistan, in global supply chains, while highlighting the urgent need for verified geological information. Many raw materials in the region remain unexplored, and the extent of its mineral wealth is still largely speculative, based on historical data and limited new findings. Leaders from the five Central Asian countries agree on the necessity to explore, balance, and utilise natural resources efficiently and economically for national interests.

    Central Asia is not only rich in copper, uranium, tungsten, lithium, graphite, titanium, and rare earth elements but also holds over 38% of the world’s manganese ore reserves and significant quantities of other critical minerals. Uzbekistan alone boasts reserves of over 30 types of critical minerals, with plans for 76 projects worth $2.6 billion aimed at developing 28 rare minerals by 2030. In Kyrgyzstan, the Kyzyl-Ompol deposit holds an estimated 20 million tonnes of titanomagnetite, while the Kutessai-2 site contains approximately 60,000 tonnes of various critical minerals.

    Kazakhstan is actively mining and integrated into global raw material supply chains, with rare earth exports quadrupling by early 2025 compared to 2020. The country joined the Minerals Security Partnership in 2024 and plans to invest nearly $5.3 billion in the development of its rare metals and minerals sector by 2028, including geological research.

    Experts believe that with detailed geological exploration using new technological solutions, the overall reserves of critical minerals in Central Asia could increase significantly. Recent geological exploration at the Kuiraktykol deposit in Kazakhstan saw resource estimates rise from 20 million tonnes to 282 million tonnes, illustrating the potential for discovery through modern methods. The rapid global economic changes and the rise of green energy and high-tech industries have intensified the demand for strategic raw materials, making extensive geological surveys essential for development.

    At the MINEX Kazakhstan 2026 forum, discussions highlighted the need for innovative approaches in geological exploration, emphasising a shift from traditional methods to systematic targeting based on modern capabilities. The reliance on archival data for over 55% of geological information underscores the importance of verifying historical data to mitigate exploration risks. The forum also addressed the balance between speed and quality in geological surveys, advocating for investments in reliable data rather than merely land.

    The implementation of advanced technologies, such as geophysical methods and remote sensing, has transformed the landscape of geological exploration, enabling the identification of previously inaccessible mineral deposits. The integration of these technologies is crucial for enhancing the efficiency and accuracy of geological assessments, ultimately leading to more successful exploration outcomes. As Central Asia continues to evolve its approach to resource exploration, the MINEX forum serves as a vital platform for international dialogue on the future of the mining industry in the region.


  • NGMK’s Investment Projects: Boosting Gold Production and Modernisation

    NGMK’s Investment Projects: Boosting Gold Production and Modernisation

    The Navoi Mining and Metallurgy Combinat (NGMK) in Uzbekistan is making significant strides in gold production and modernisation, as highlighted during the MINEX Kazakhstan 2026 forum. The company has increased its gold output to 98.2 tonnes in the previous year, achieving a net profit of $3.5 billion, a 64% increase, largely due to favourable market conditions where the average price per ounce exceeded $3,400. NGMK plays a crucial role in Uzbekistan’s strategy for 2030, which aims to elevate the country’s gold production from 118 tonnes to 175 tonnes. This ambitious target positions NGMK as a leader in the region, which currently accounts for 7.5% of global gold production, with nearly half of that attributed to the NGMK.

    To maintain its growth momentum, NGMK is leveraging various tools for sustainable development, including geological exploration, advanced technologies, and infrastructure improvements. The company has invested significantly in expanding the Muruntau mine, which has been recognised as a global leader in gold production. The mine’s dimensions have grown substantially since its inception in 1967, and recent investments have further enhanced its capacity.

    In addition to expanding existing operations, NGMK is also focusing on exploring new mineral deposits. The company has acquired licenses for new areas and is conducting geological exploration to confirm gold reserves in regions like Kokpatas and Daugiztau. The resource base of NGMK currently stands at approximately 140 million ounces of gold, with ongoing efforts to increase this through the processing of lower-grade ores.

    Investment in infrastructure is another key focus for NGMK, with over $1 billion allocated for 2025 alone. This includes modernising existing facilities and introducing new technologies to improve operational efficiency. The company has successfully implemented various projects aimed at enhancing its processing capabilities and expanding its mining fleet, which is crucial for meeting the growing demand for gold.

    Digital transformation is also a priority for NGMK, with a strategy in place to modernise operations by 2030. This includes the adoption of information technologies for geological exploration, automated inventory calculations, and real-time monitoring of production processes. The integration of artificial intelligence and machine learning is helping to optimise operations and reduce human error, thereby improving overall efficiency.

    As NGMK continues to evolve, its commitment to sustainable practices and technological advancement positions it well for future growth in the competitive global mining landscape. The company’s proactive approach to investment and innovation not only strengthens its market position but also contributes to Uzbekistan’s economic development and industrial sovereignty.


  • Critical Minerals in Central Asia and the South Caucasus Regions—Challenges and Opportunities

    Critical Minerals in Central Asia and the South Caucasus Regions—Challenges and Opportunities

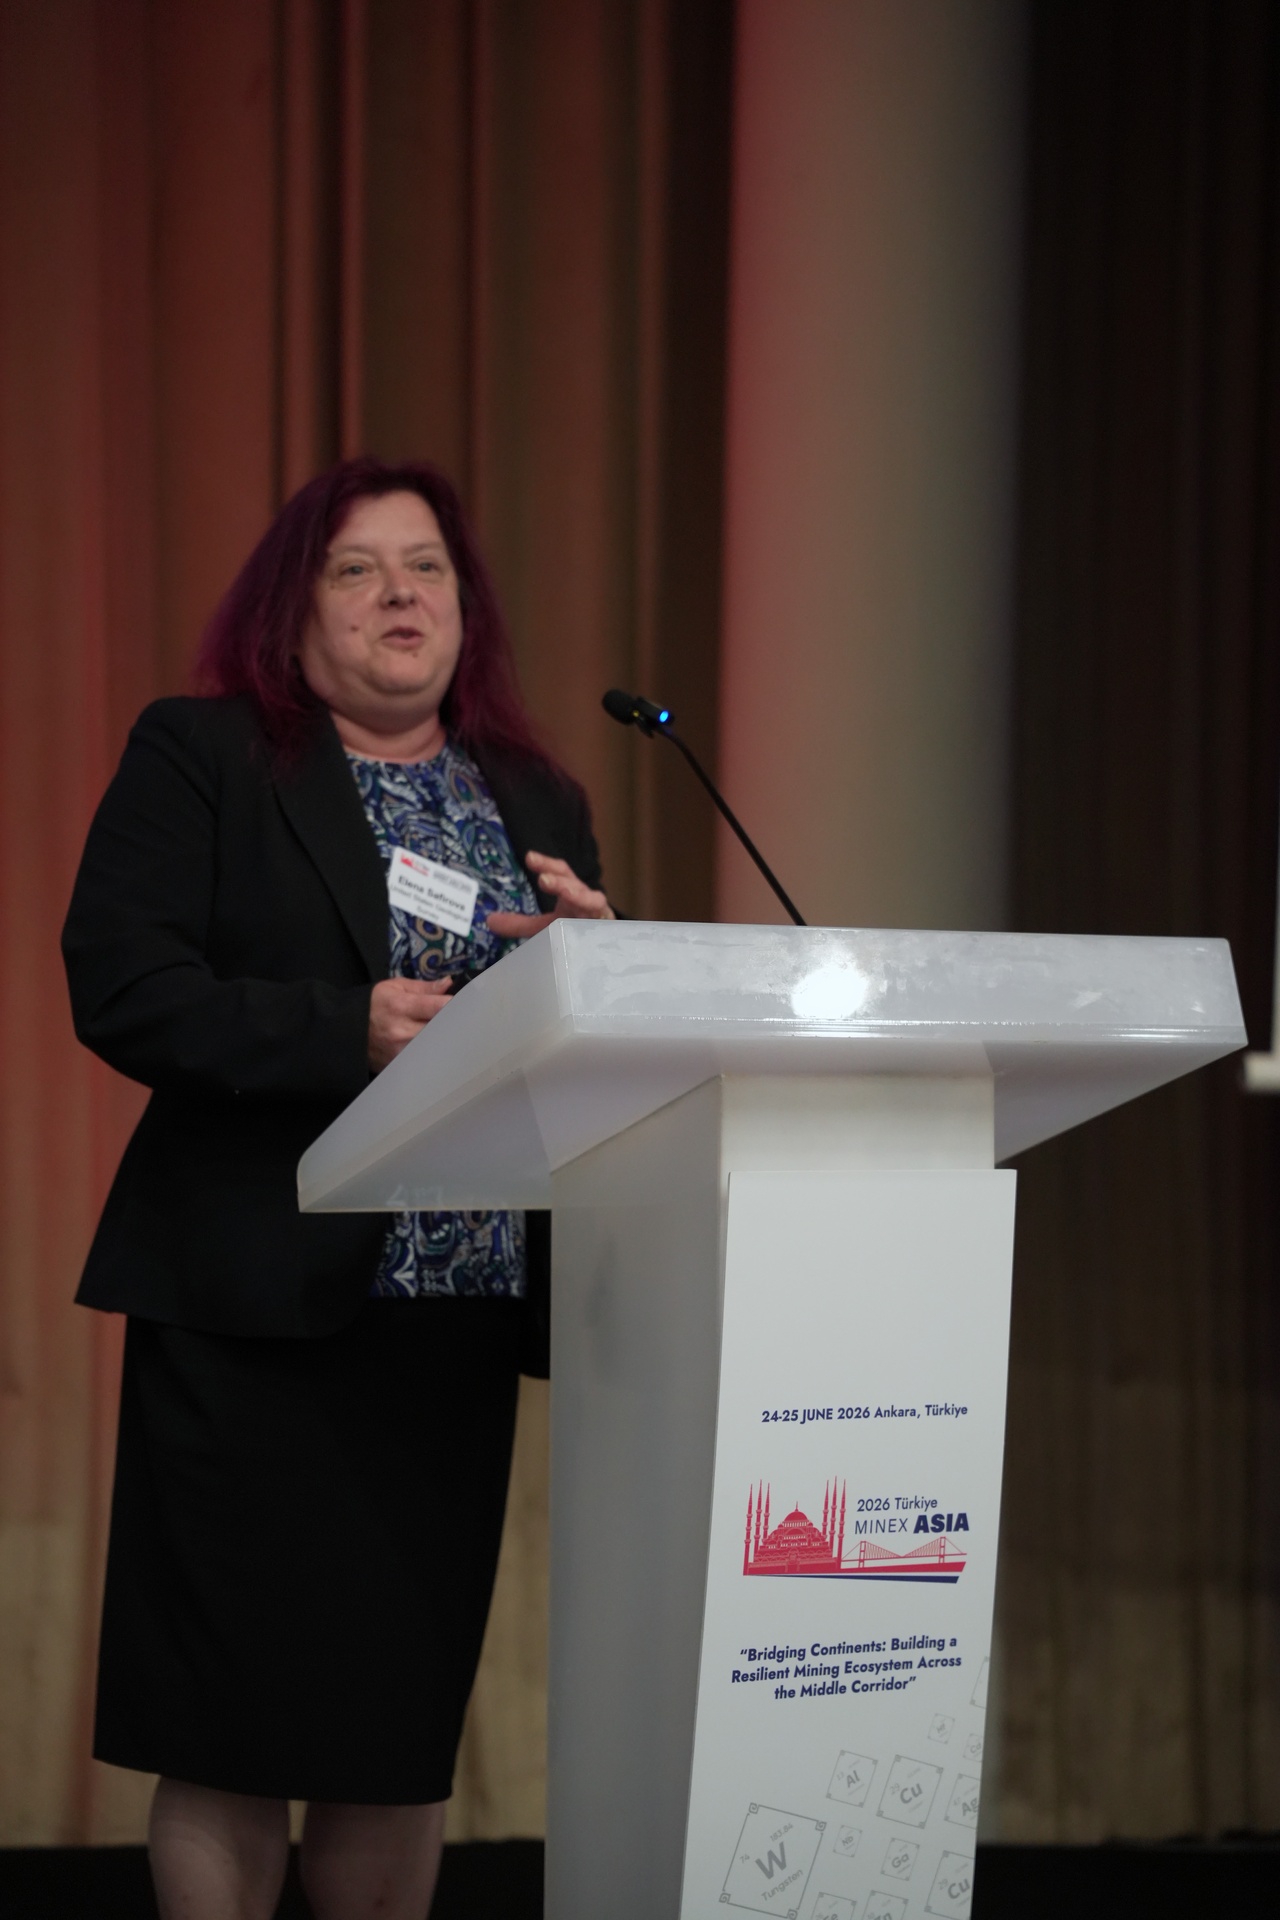
    Elina Sofirova — U.S. Geological Survey (USGS)

    Sofirova distinguishes her role — reporting on existing, verified production data rather than forecasts — and explains how the U.S. government defines critical minerals (a legally mandated, criticality-index-based list, now numbering 60 minerals and updated every three years; the newest list added items like boron, where Turkey is the top global producer). She contrasts approaches: the EU’s list (34 minerals), Canada’s, and Russia’s domestically focused framework, versus the US/Canada “hybrid” approach balancing domestic production and diversified sourcing.

    Using 2024 USGS production data, she runs through the region: Kazakhstan is the clear regional leader (number one globally in uranium, among others); Kyrgyzstan and Georgia currently show minimal or no listed CRM production; Tajikistan ranks second globally in antimony; Uzbekistan has a broader production base, though data quality has only recently improved; Armenia produces rhenium and molybdenum (though molybdenum isn’t on the US list, since the US produces its own). She notes Turkmenistan reports essentially no CRM production and is difficult to get data from at all. She closes by reiterating that her focus is strictly on what already exists, not projections.

    #CriticalMinerals #MiningIndustry #CentralAsia #SouthCaucasus #USGS #MINEXAsia #ResourceSecurity

  • U.S. policy on critical minerals

    U.S. policy on critical minerals

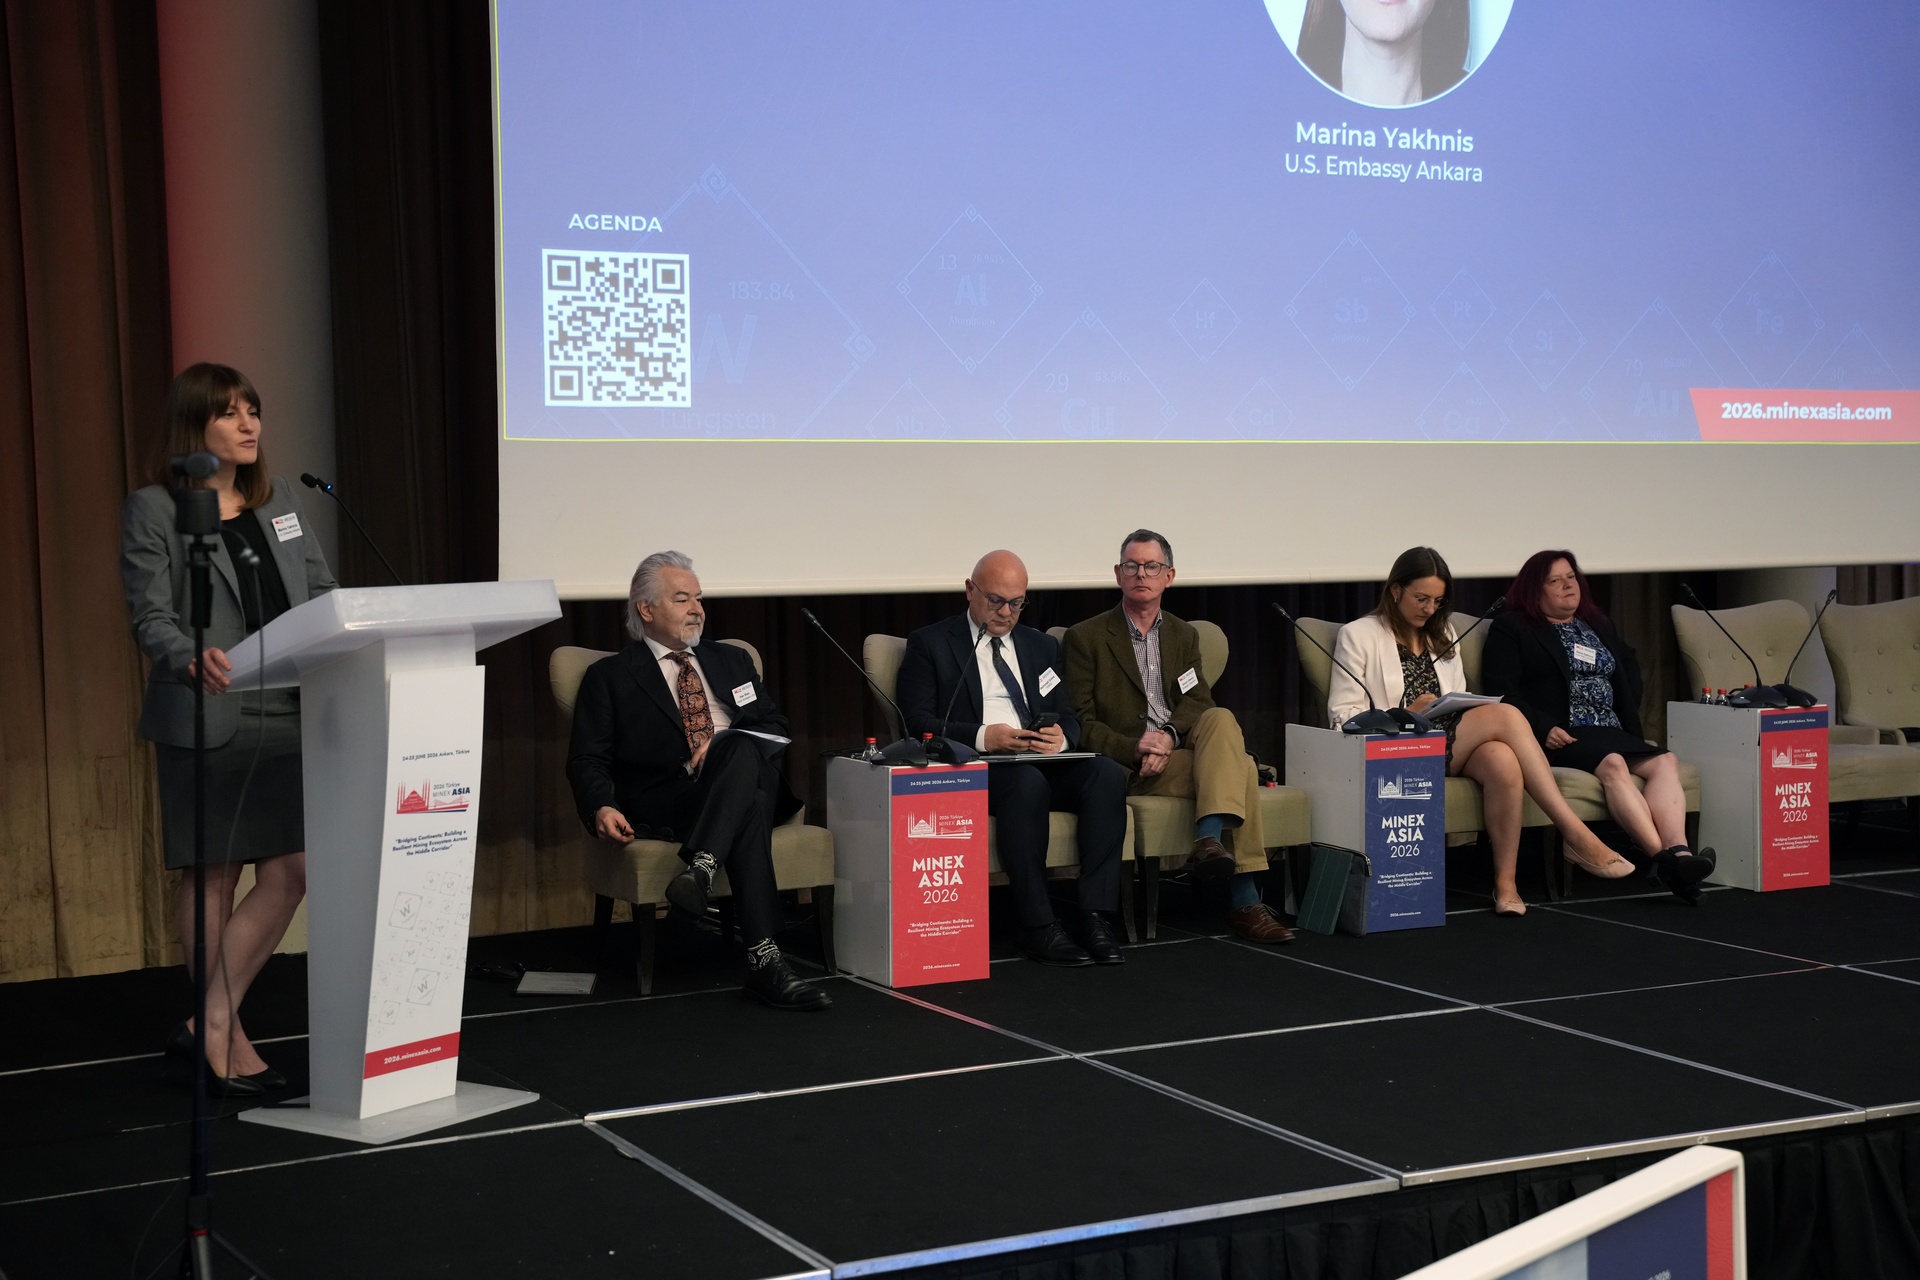
    Marina Yaknes — U.S. Department of State (Economic Officer, Ankara)

    Yaknes presents a “1,000-foot view” of U.S. critical minerals policy, fra


    ming China’s dominant, non-market-driven control of key mineral markets as the central problem. She outlines four policy pillars: investing (hundreds of billions in debt and equity, including new-for-the-US equity investing), stockpiling (including “Project Vault,” a domestic strategic reserve backed by a $10 billion Export-Import Bank loan facility), protecting mining companies abroad, and reforming the domestic permitting ecosystem to move faster than the historical ~29-year mine-development timeline.

    She details recent diplomacy: a February 2026 critical minerals ministerial with 54 countries plus the EU (representing roughly two-thirds of global GDP), where the U.S. signed 11 new bilateral CRM frameworks (adding to 10 signed earlier), and Secretary Rubio announced “FORGE” (Forum on Resource Geostrategic Engagement) as successor to the Mineral Security Partnership, alongside a complementary initiative called “PAX Silica” covering broader technology and infrastructure supply chains. She closes citing over $30 billion in U.S. letters of interest, investments, and loans over the past six months, intended to mobilize far larger private capital.


    #USPolicy #CriticalMinerals #SupplyChainSecurity #FORGE #ProjectVault #PAXSilica #MiningIndustry


  • Unlocking the Tethyan Belt: The Strategic Vision for the Middle Corridor’s Mineral Wealth

    Unlocking the Tethyan Belt: The Strategic Vision for the Middle Corridor’s Mineral Wealth

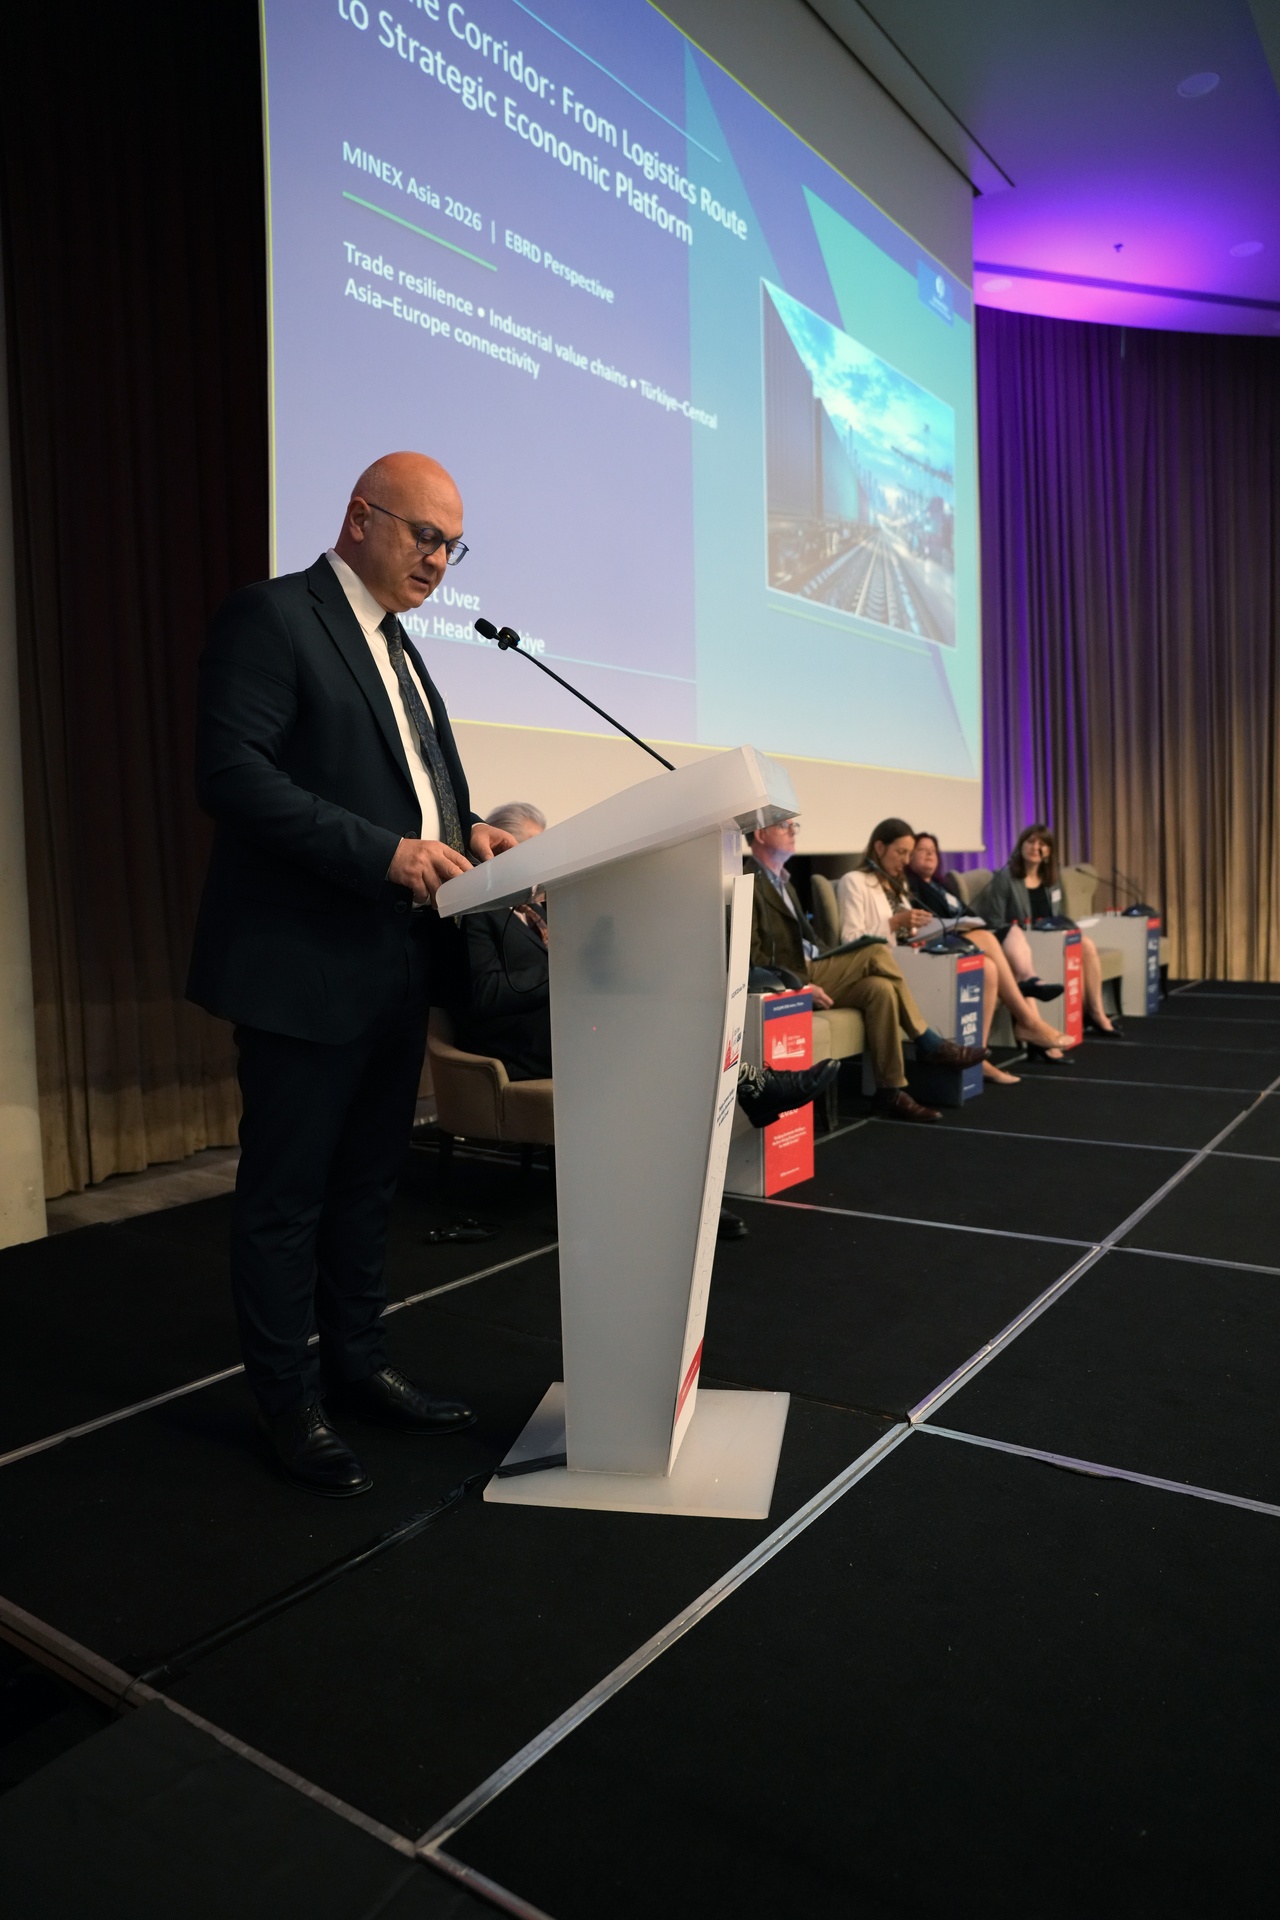
    Mehmed Uves — European Bank for Reconstruction and Development (EBRD)

    Uves argues connectivity is no longer just about moving goods faster — it’s about securing and diversifying the supply chains underpinning industrial transformation. He positions the Middle Corridor as the emerging physical backbone linking Central Asian and Caucasus minerals to Turkish and European markets, and makes three points: (1) the corridor must evolve from proving its relevance to working at scale — improving capacity, cross-border interoperability, and commercial viability, while supporting full value chains rather than just transit; (2) Turkey plays a pivotal role, not merely as a transit segment but as an industrial base positioned to anchor processing and manufacturing closer to end markets; (3) EBRD backs this through substantial financing — roughly €2.5–3 billion invested annually in Turkey (90% private sector), including over €1.5 billion across 30 transport and logistics projects. He cites the North Istanbul rail crossing project (up to €500 million in EBRD sovereign financing, alongside other multilateral development banks) as a flagship example. He closes by framing the corridor as a strategic economic platform rather than a simple alternative route.

    #MiddleCorridor #TethyanBelt #CriticalRawMaterials #SupplyChainSecurity #EBRD #Turkey #CentralAsia