Website: Europe.com

  • Türkiye’s R&D and Production Vision in the Rare Earth Elements Ecosystem

    Türkiye’s R&D and Production Vision in the Rare Earth Elements Ecosystem

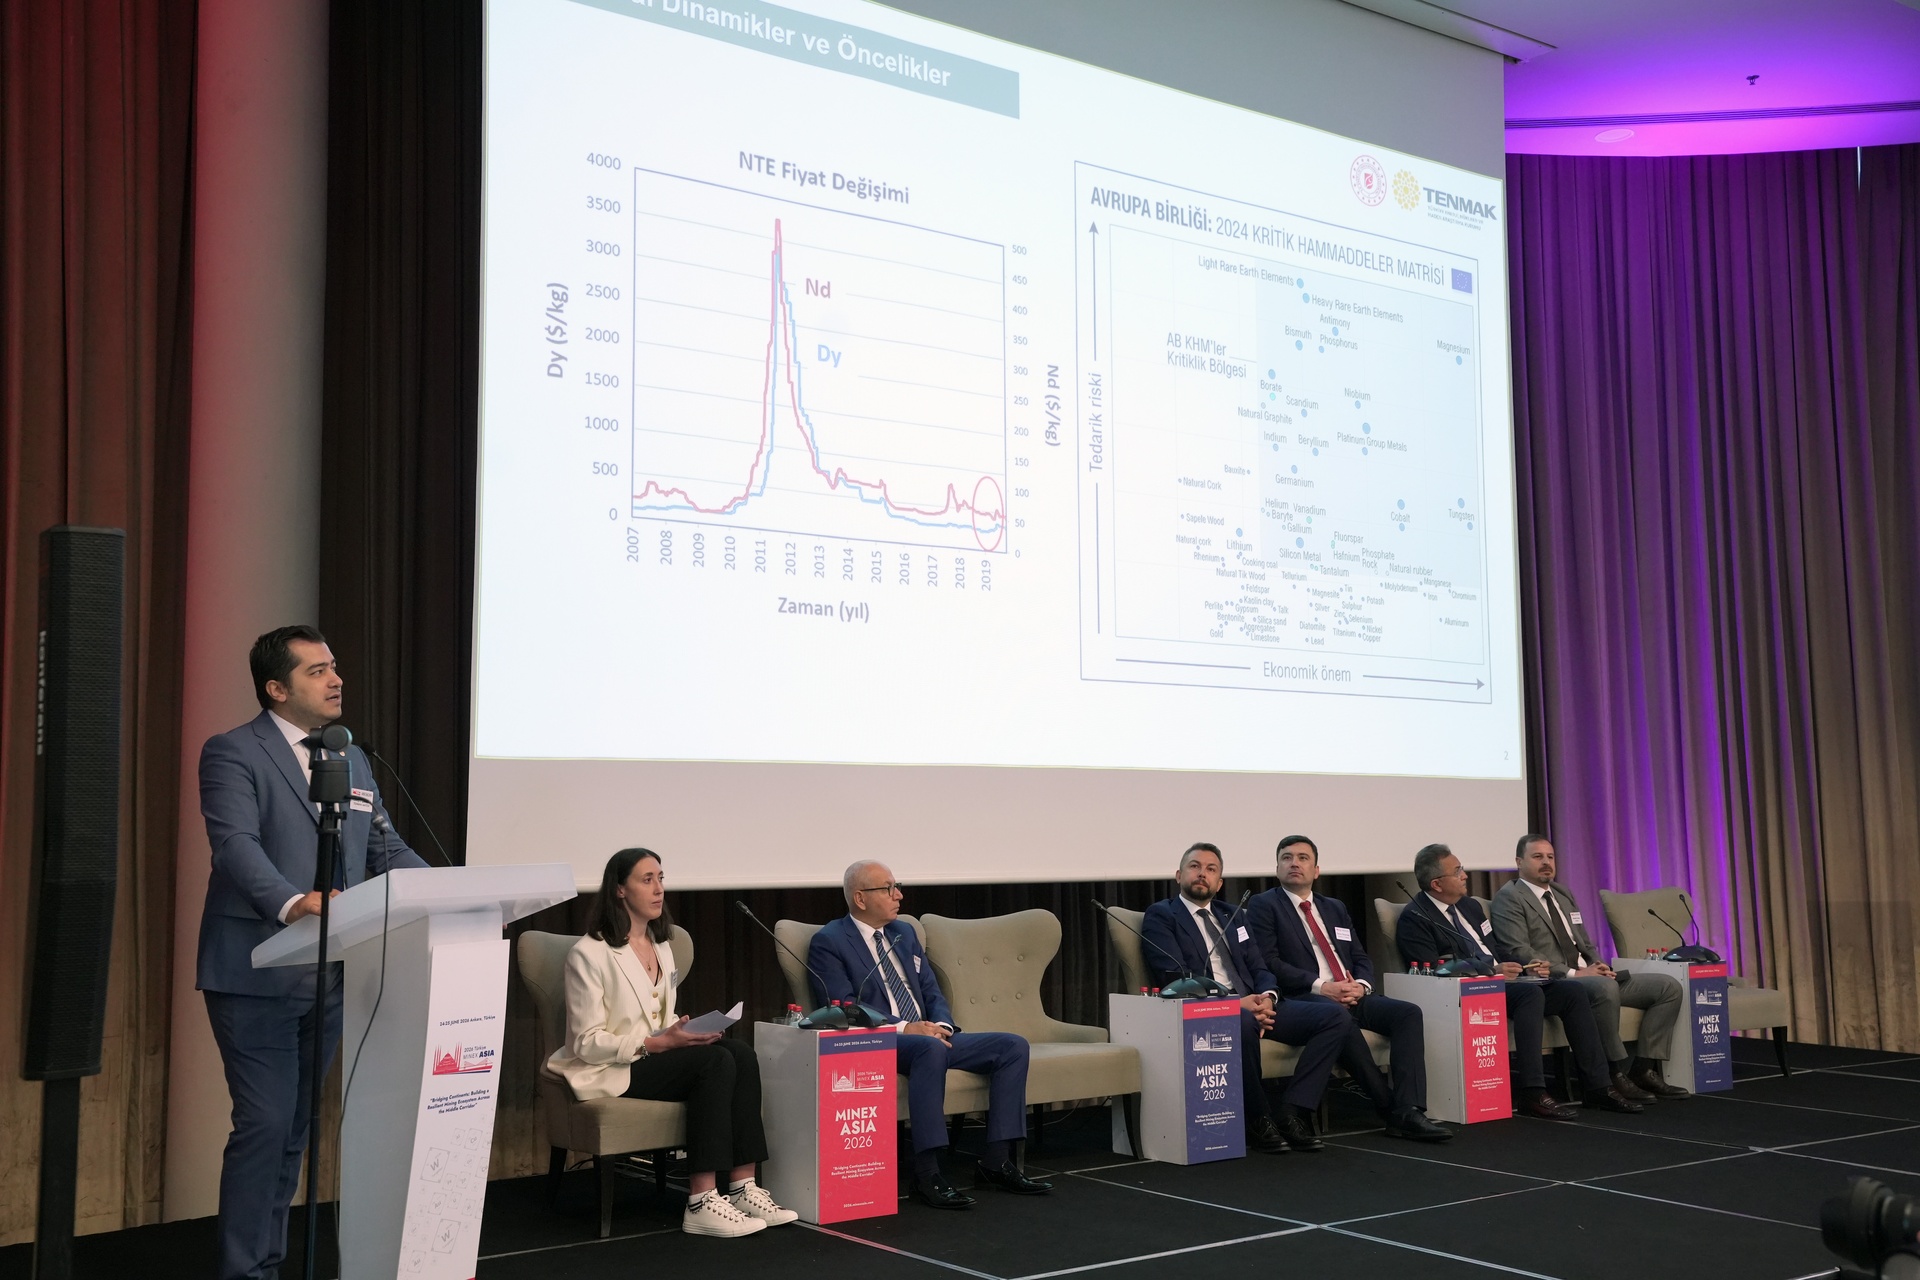
    Hüseyin Çaldırak traced global rare earth (REE) awareness to a 2010 China-Japan dispute that triggered export restrictions and market volatility, prompting the EU to launch its Critical Raw Materials framework in 2011, with updated lists every three years since. Roughly 9-10 other countries now publish similar lists, typically converging on materials with high supply risk and economic importance — REEs feature prominently due to wind turbine and EV applications, with defense uses carrying outsized strategic weight despite smaller volumes.

    He detailed China’s dominance across the REE value chain, illustrated by Lynas Corporation processing Australian ore but relying on Malaysia for purification, with China now requiring export licenses for any product containing Chinese-origin REE content. He noted REE economics vary sharply by element: cerium and lanthanum comprise about half of REE volume, while neodymium, praseodymium, dysprosium, and terbium represent roughly 96% of market value despite scarcity.

    He described the EU’s 2024 Critical Raw Materials Act setting concrete targets — no single country supplying over 65% of any material, with minimums of 10% domestic mining, 40% processing, and 25% recycling — alongside similar strategies emerging across the US, Australia, Canada, and 25+ other countries in the past year.

    A major focus was the US approach, including a policy effective January 2027 barring magnet production stages from China, Russia, Iran, or North Korea. He highlighted Mountain Pass’s ten-year MP Materials partnership plus agreements with Lynas and Serra Verde, which establish price floors regardless of spot prices. He noted Serra Verde’s ore grade is just 0.12% — far below Turkey’s often-criticized 2% at Beylikova — arguing this shows US willingness to invest despite lower ore quality.

    On recycling, he cited European magnet recycling processing only 4,000-5,000 tons annually, with the EU’s 25% target currently realized at under 1%, though the IEA projects recycling could reduce virgin REE mining needs by up to 35% by 2050.

    Turning to Turkey, he presented Beylikova’s figures: roughly 694 million tons at ~2.5% grade, yielding potentially 12.5 million tons of reserves — enough to rank third globally, pending international certification. If state miner Eti Maden reaches 10,000 tons annual production with 30% yearly growth, Turkey could become self-sufficient in REE for domestic wind needs and potentially an exporter. He walked through demand modeling: wind turbines require ~650 kg of neodymium-iron-boron per megawatt (~165 kg REE), and Turkey’s planned growth from 15 GW to 48 GW by 2035 would require roughly 3,500 tons of REE — demand Beylikova could fully satisfy.

    He outlined institutional history: REEs entered the 11th Development Plan, leading to the Institute’s 2018 founding, 2020 integration into NADEM, and the 2025 Ministry Critical and Strategic Minerals Report, which he described as Turkey’s only report built on genuine mathematical modeling rather than qualitative lists.

    He detailed technical achievements: upgrading Beylikova’s 2% concentrate to over 30% REE oxide at above 80% efficiency, plus high-yield barite and fluorite concentrates; achieving over 99% purity mixed oxides; and developing a domestic mixer-settler separation system with Istanbul Technical University. On secondary sources, he cited successful extraction from fluorescent lamps, waste magnets, PCB boards, and hard drives, including a prototype domestic magnet from recycled materials, plus ongoing work on mining waste, geothermal sources, and partnerships with Turkey’s coal institutes showing promising Zonguldak results.

    He closed by listing end-product goals — permanent magnets, optical and polymeric nanocomposites, magnetic materials — alongside EU Horizon project participation and infrastructure spanning ore beneficiation labs and dedicated magnet R&D facilities.
     

  • The Role of Geochemical and Metallurgical Laboratories in Mining Value Chain Data

    The Role of Geochemical and Metallurgical Laboratories in Mining Value Chain Data

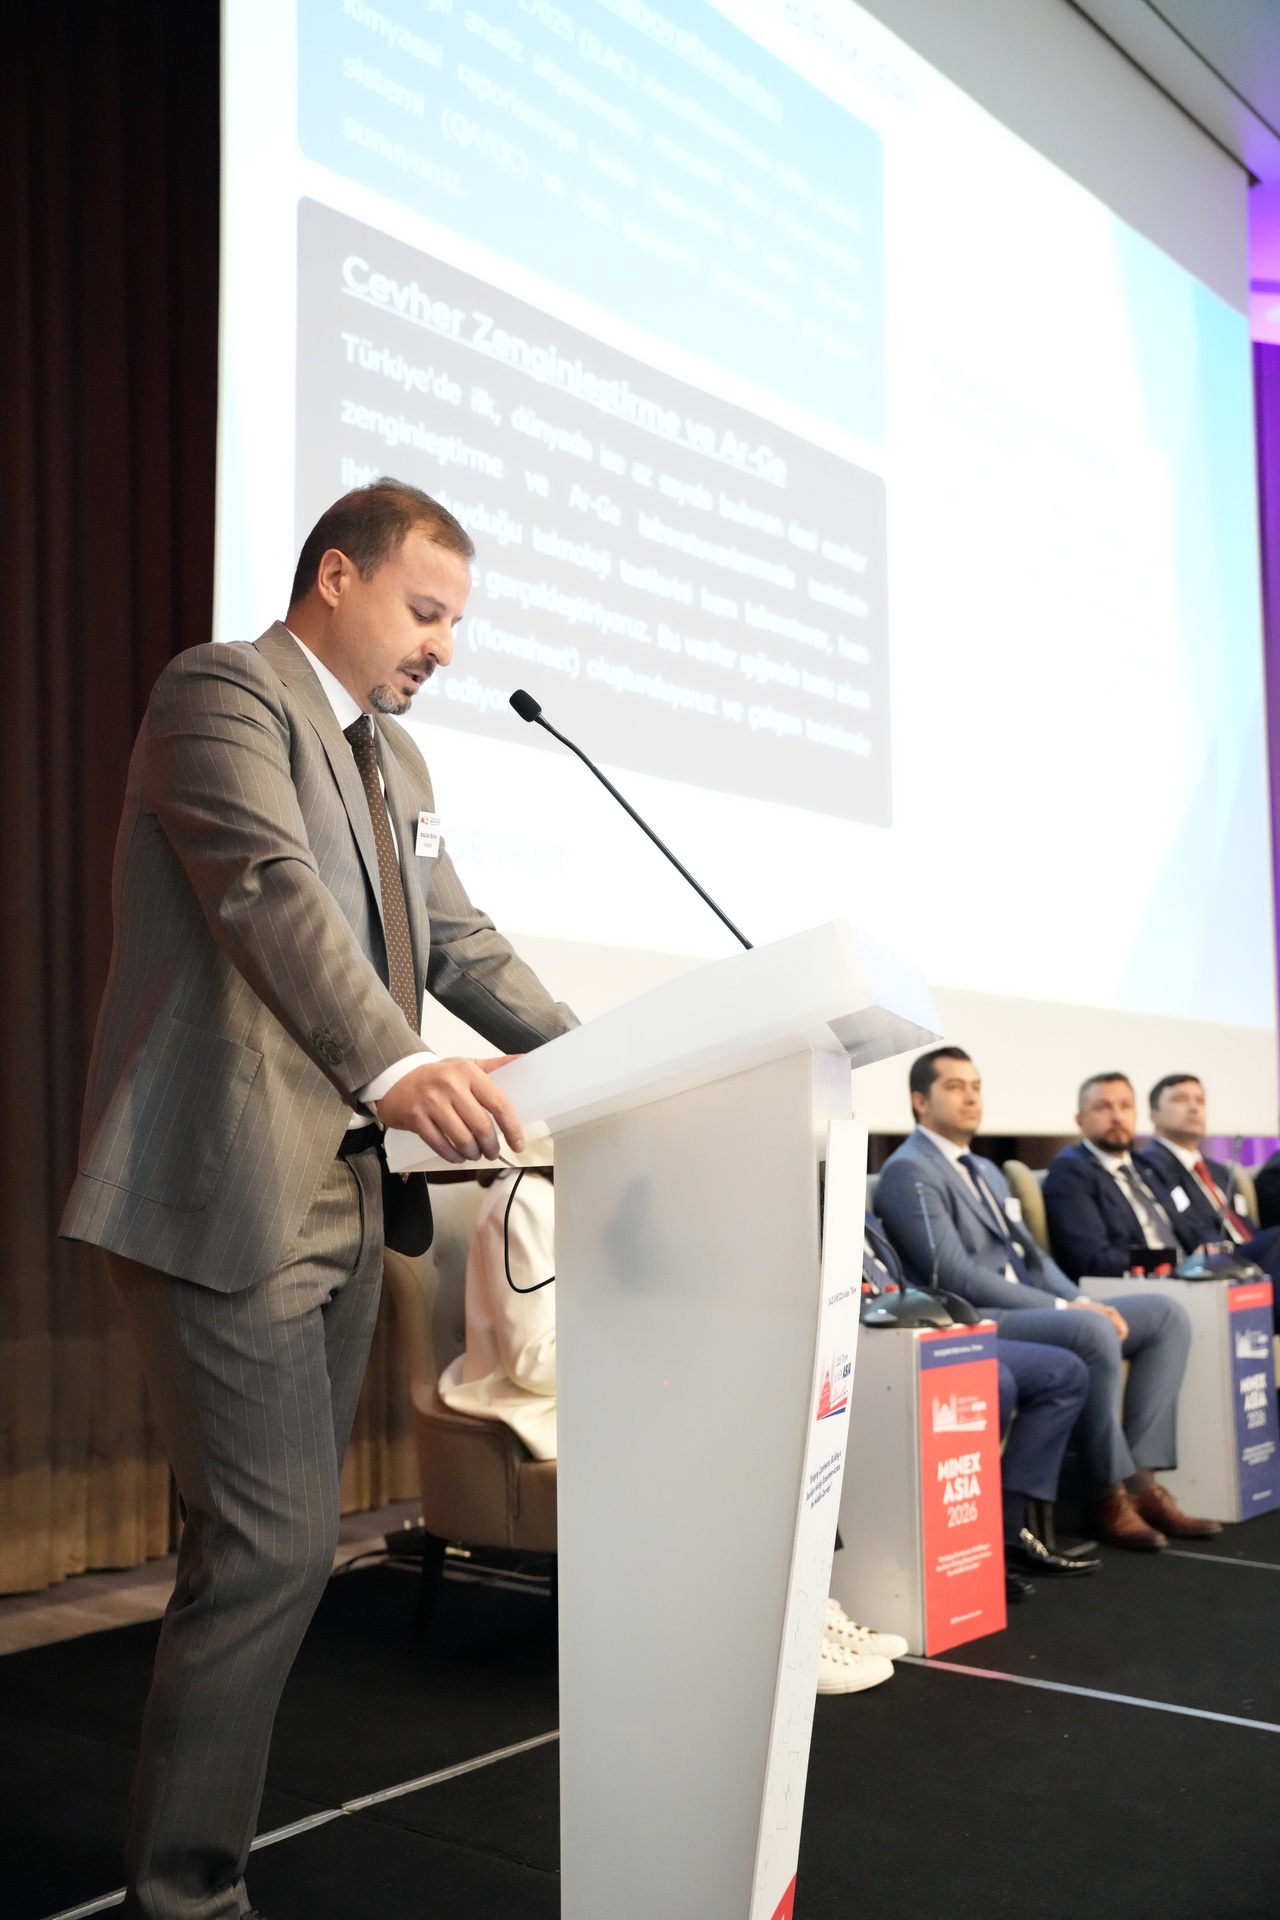
    Abdullah Buhur opened by shifting focus away from the large machinery and infrastructure typically associated with mining, toward a less visible but critical component: data. He argued that modern mining requires precisely and thoroughly characterizing ore composition before extraction even begins, and positioned his talk around the role geochemical and metallurgical laboratories play in generating end-to-end data across the mining value chain.

    He introduced ARGETEST, founded in Ankara in 2012 with the explicit goal of functioning not merely as a testing center but as a decision-support mechanism shaping the future of mining projects. He described the company as operating Turkey’s first, and among the world’s few, private ore beneficiation and R&D laboratories, capable of designing plant process flowsheets and optimizing existing operational facilities for greater efficiency and economic performance. He noted the company’s high-technology geochemical analysis labs offer full traceability from sample intake through reporting.

    He emphasized that data credibility today is measured by international recognition, citing ARGETEST’s ISO 9001, 14001, and 45001 certifications alongside ISO/IEC 17025:2025 laboratory accreditation — framing these not as mere certifications but as guarantees recognized by international banks and stock exchanges that partner companies rely on.

    Acknowledging that mining rarely happens in convenient urban locations, he described the company’s mobile, containerized field laboratories, which bring accredited testing infrastructure directly to remote mine sites, minimizing delays and allowing engineers to view results in near real-time. He noted this approach has already expanded internationally, with the company’s first overseas laboratory established in Tashkent, Uzbekistan, and plans underway to establish facilities in three additional countries.

    Returning to the core theme of data value, he explained that mining involves enormous capital risk, and that a single flawed geological or chemical data point can lead to incorrect process design — potentially rendering an entire facility economically nonfunctional. He noted that international reporting standards (JORC, NI 43-101, UMREK) depend fundamentally on accredited, independent laboratories producing statistically repeatable, verifiable, and traceable analytical results.

    He organized laboratory contributions across four project phases: exploration (identifying potential through geochemical analysis), feasibility (determining optimal ore recovery process flowsheets), production (continuous plant optimization via real-time data), and closure (environmental toxicology testing to fulfill environmental responsibilities). He detailed technical processes within each phase — including sample preparation standards, QA/QC protocols using blanks, duplicates, and certified reference materials, and metallurgical testing methods like comminution testing and predictive process modeling.

    He reiterated the earlier point about the outsized financial impact of even small measurement errors in recovery rates, framing laboratory investment as one of the lowest-cost yet highest-impact investments relative to total project capital. He closed by discussing digital data integration — barcode-tracked samples, direct digital data transfer without manual handling, and continuous system interconnection — designed to minimize human error toward near-zero levels, and reaffirmed ARGETEST’s commitment to expanding its footprint from Turkey through Central Asia and beyond as a trusted partner across the mining value chain.


  • What Should Change in Turkey’s Mining Legislation and National Mining Policy Principles

    What Should Change in Turkey’s Mining Legislation and National Mining Policy Principles

    Ayhan Yüksel, representing Turkey’s Chamber of Mining Engineers, opened with foundational principles necessary to understand mining regulation: mines are non-renewable resources formed over millions of years; whether something qualifies as an economically or technologically viable “mineral” can change over time with shifting economic and technological conditions; minerals belong partly to future generations; and mining must be conducted where deposits are physically located, since they cannot be relocated.

    He traced Turkey’s mining legislative history, starting with the original 1954 Mining Law (No. 6309), characterized by a strong statist framework with a licensing system under clear state authority. This was followed by Law No. 3213 in 1985, introduced during a period of globalization and liberal economic policy shifts, which refined the licensing system while maintaining core constitutional principles that minerals remain under state jurisdiction, alongside introducing indivisible mining rights and state oversight and royalty principles.

    His central argument concerned the frequency of legislative change: the law remained unchanged for 31 years between 1954 and 1985, and unchanged again for 19 years between 1985 and 2004 — but since 2004, has undergone 31 amendments (including 9 major overhauls) in just 24 years. He walked through specific triggers for these changes: the 2004 reforms coincided with broader foreign investment liberalization across multiple sectors; a subsequent wave incorporated growing environmental regulation and protections; the 2014 Soma mine disaster prompted stronger occupational safety requirements and permanent on-site supervision; and 2019 brought UMREK, Turkey’s version of international reporting standards (comparable to JORC/NI 43-101), along with revised state royalty calculations and stricter technical/financial oversight — followed by further adjustments in subsequent years, including changes to site subdivision rules.

    He argued that this constant legislative churn has genuinely undermined the sector — mining’s contribution to GDP has remained around just 1%, and public opposition to mining projects has persisted or intensified, suggesting frequent regulatory change hasn’t solved underlying problems, precisely because mining requires long-term (20-30+ year) planning horizons incompatible with regulatory instability.

    He then outlined the Chamber’s proposed foundational principles for mining policy: the core objective should be national development and social welfare, not purely commercial mechanisms; mining must be grounded in scientific and technical planning given the non-renewable nature of resources; mining should be integrated with domestic industry rather than treated as pure ore extraction; domestic mineral resources should be prioritized in energy production to ensure supply security; exploration activity needs to increase since Turkey’s territory remains incompletely explored; technology and R&D investment must grow; human resources — particularly mining engineers — need continued development and employment support; both public and private sector management should be more efficient, transparent, and accountable; environmental opposition should be addressed by integrating environmental and mining considerations together rather than framing them as an either-or dilemma; and mining must be conducted in cooperation and peace with local communities, with transparency and multi-stakeholder collaboration across government, industry, and civil society. He closed by summarizing that national mining policy should ultimately be human-centered, scientifically grounded, environmentally compatible, supportive of domestic industry, and built on participatory planning.


  • Why Invest in Türkiye? A Macroeconomic and Investment Case for the Mining Sector

    Why Invest in Türkiye? A Macroeconomic and Investment Case for the Mining Sector

    Özkan Özkardeş presented a macroeconomic case for investing in Turkey, framing his talk explicitly as a non-specialist, broad-perspective overview rather than a technical mining presentation. He outlined ten core strengths making Turkey attractive to international investors, starting with the country’s robust economy — now around $1.6 trillion in GDP — supported by Customs Union membership, trade agreements with over 30 countries, and a population of roughly 86 million providing indirect access to a billion consumers globally.

    He emphasized Turkey’s strategic geographic position at the crossroads of multiple continents, and its favorable demographics — a young, dynamic population with a median age around 35, contrasting favorably with aging populations in many advanced economies, even while acknowledging recent declining fertility rates. He cited Turkey’s 10th-place global ranking by purchasing power parity, with a trajectory potentially reaching the top five economies by that measure in coming years, and highlighted sound public finance indicators — including manageable public debt and budget balance ratios — comparing favorably to EU peer averages.

    On trade performance, he noted export volumes exceeding $283 billion in goods (excluding services), with roughly 9% average annual growth over 22 years compared to a global average closer to 6%, alongside more than 50 product categories with over $1 billion in export value each. He cited quality-of-life indicators like quadrupled automobile ownership and roughly eightfold growth in aviation passenger volumes as evidence of committed infrastructure investment.

    Turning to foreign direct investment specifically, he cited over $13 billion in FDI received in the most recent year, spanning manufacturing, finance, energy, and mining sectors, and extended an explicit invitation for international investors to take advantage of Turkey’s incentive schemes. On mining specifically, he noted Turkey’s position as a global producer of several critical minerals — citing chromium and fluorite (fluorspar) as areas of particular strength — alongside gold and copper, and referenced over 600 international companies currently operating within the Turkish economy.

    He devoted a substantial portion of his talk to logistics, acknowledging that rail currently represents a relatively underdeveloped share of Turkey’s freight transport but noting government commitment to raising rail’s share to roughly 20% by the mid-2050s through four major infrastructure projects currently under construction. He connected this investment directly to the Middle Corridor initiative, positioning Turkey as a stable geographic anchor for international trade given recent geopolitical developments in the region. He also referenced Turkey’s Development Road initiative — a planned rail and highway corridor connecting from Iraq’s Al-Faw port through Iraqi territory to integrate with existing Turkish infrastructure — as another emerging alternative trade route relevant to mineral logistics. He closed by positioning Turkey as poised to become a major hub not just for mineral production but for the transport of minerals from source to global markets.


  • Critical Mineral Needs and Turkey’s Mining Perspective on Energy Transition and Digitalisation

    Critical Mineral Needs and Turkey’s Mining Perspective on Energy Transition and Digitalisation

    Ibrahim Halil Kırsan opened with a historical sweep of global energy transitions — from coal’s dominance following the industrial revolution, through oil in the 20th century, to natural gas from the 1970s, and now the shift toward renewables over the past two decades. He noted that despite this transition, fossil fuels remain heavily used globally, particularly in Asia (China, India), the Middle East (oil and gas), and hydro-rich countries like Canada. He cited that coal’s share of global electricity generation has only modestly declined, from roughly 35% to about 34%, meaning fossil-based systems will persist until renewable capacity grows substantially further.

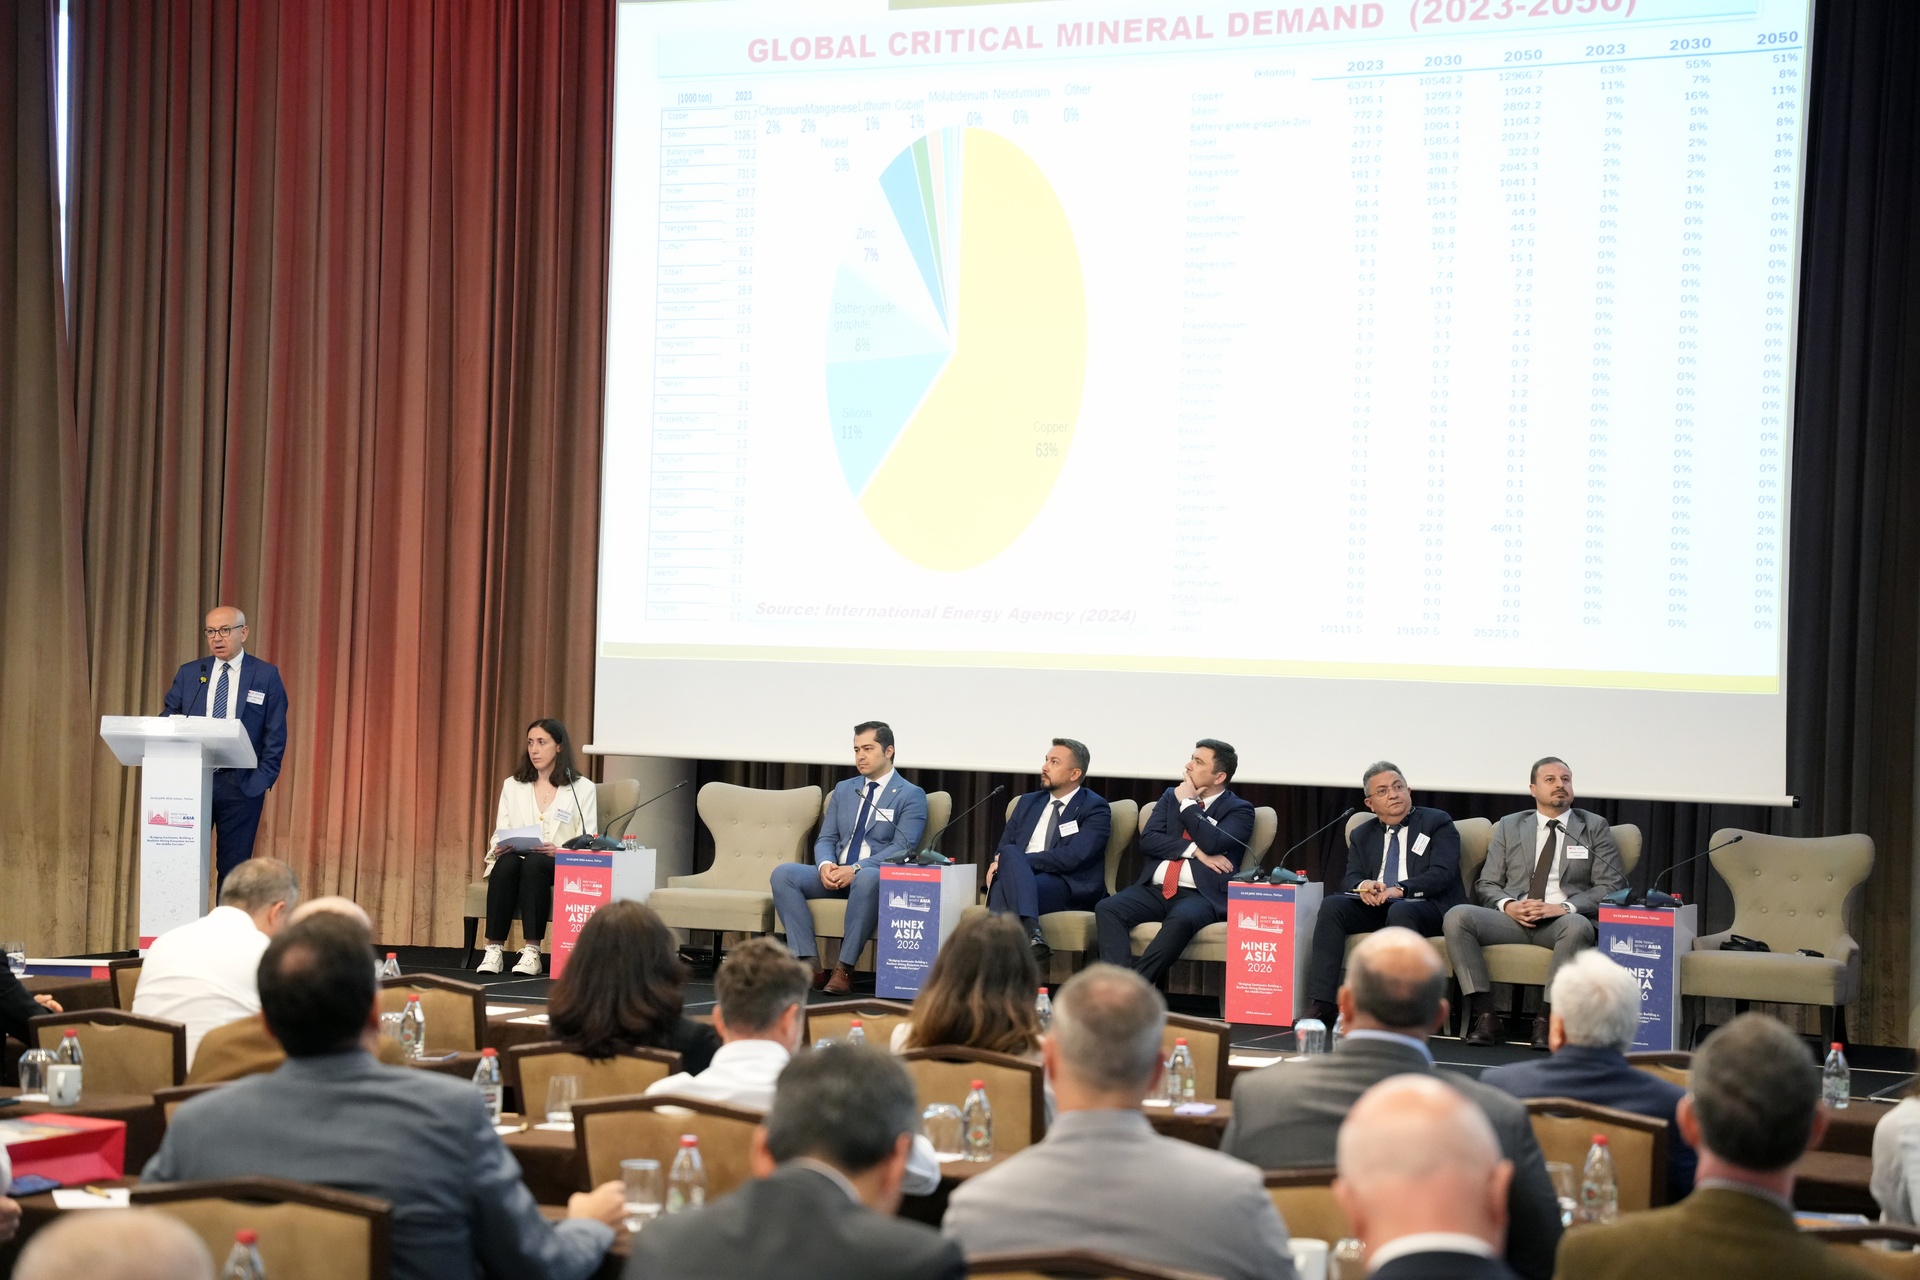
    He presented IEA projections showing critical mineral demand could grow four to six times by 2040 depending on the climate scenario, with battery-related minerals like lithium and cobalt seeing the steepest increases. He highlighted that global mineral production has surged particularly in the last 5-10 years, driven by clean energy, digitalization, and space industry demands, with copper playing an especially central role in future demand projections due to insufficient scrap-based supply relative to other metals.

    He explained that while mineral deposits are widely distributed geographically, refining capacity is heavily concentrated in China across nearly all major critical minerals — lithium, cobalt, nickel, rare earths — with the notable exception of nickel, where Indonesia holds a dominant position. He cited an estimate that if China restricted exports of these materials, the EU and US could face combined annual losses of roughly $3.5 trillion, underscoring the depth of Western dependency. He connected this dependency directly to recent US-China trade tensions, noting China’s extensive mining investments across multiple continents to secure both supply and refining dominance.

    He reviewed how numerous countries (EU, US, Canada, Japan, and now Turkey, whose list was published in 2025) have begun publishing critical minerals lists, with substantial overlap across roughly 200 shared minerals. Turning to Turkey specifically, he described the country as geologically comparable to a “small continent” in terms of mineral diversity — ranking in the top 8 globally for diversity, with strong positions in boron (world’s largest reserves), marble, chromium, and pumice, among many other metallic, industrial, and energy raw materials.

    A significant highlight was his discussion of the Eskişehir Beylikova rare earth element deposit, which he described as potentially the world’s second-largest known REE resource after China’s Bayan Obo deposit, with an estimated 694 million tons of material and roughly 12.5 million tons of REE reserves at approximately 3% grade. He noted that extensive drilling (roughly 125,000 meters across 310 locations) has been completed and pilot-scale processing work is underway, though the site hasn’t yet been formally certified against international reserve reporting standards.

    He closed with policy recommendations: Turkey needs to move beyond exporting raw or concentrated ore toward producing finished, technology-enriched products; critical minerals lists need regular updating; and — his central proposal — Turkey should establish a dedicated Critical Minerals Presidency or Institute, given that the issue now spans multiple ministries (Energy, Industry, National Defense) rather than falling under any single one.


  • Türkiye’s Mining Vision: Export Growth and Strategic Autonomy Through Gold Mining

    Türkiye’s Mining Vision: Export Growth and Strategic Autonomy Through Gold Mining

    Ahmet Serkan Sarıtaş introduced Türk Gold Corp (formerly Koza Gold Enterprises), describing it as Turkey’s first wholly domestically-capitalized gold mining company, founded in 2005, with 30% of its capital publicly listed on Borsa Istanbul since 2010. He noted the company rebranded to its current name in 2025 and now operates as a strategic national asset within the portfolio of the Turkey Wealth Fund. He cited the company’s scale: 2,553 specialized employees, operations spanning 41 provinces, and 231 active licenses, framing this footprint as evidence of the company’s commitment to converting Turkey’s mineral potential into economic value.

    He situated gold mining within the broader narrative of energy transition, electrification, AI, and digitalization, arguing that reliable mineral resources underpin all of these transformations — electric vehicles, battery technology, AI infrastructure, renewable energy systems, and defense industries. He argued that minerals have consequently evolved beyond simple economic commodities to become fundamental elements of economic security, industrial policy, and strategic independence, making the creation of reliable, sustainable, and diversified supply chains a top national priority.

    He positioned Turkey favorably within this new landscape, citing the country’s roughly $3.5 trillion mineral potential, strong industrial infrastructure, developed logistics network, skilled workforce, and long mining history as preparing it for a stronger role in the global mining ecosystem. He argued that future competitive advantage will belong not simply to countries possessing mineral resources, but to those capable of converting those resources into knowledge, technology, industry, and sustainable development — emphasizing that investment in geological knowledge, scientific research, human capital, and advanced technology serves as the guarantee of future resource security, alongside environmental responsibility, social awareness, and good governance principles.

    He addressed Turkey’s “strategic” mining characterization directly, clarifying that this should not be understood as economic isolation, but rather as strengthening domestic capabilities while simultaneously deepening international cooperation and building resilient supply chains — with Turkey’s position at the center of the Middle Corridor serving as a natural bridge between Europe and Asia, valuable not just as a logistics route but as a platform for investment, technology transfer, and high-value industrial clustering.

    He described Türk Gold’s approach as reducing Turkey’s external dependency and contributing to narrowing the current account deficit, while measuring success not solely by gold output volume but by employment generation, local supply chain development, and social investment in the regions where the company operates — framing mining’s success as ultimately measured by contribution to quality of life rather than metal tonnage alone.

    He highlighted several human capital initiatives: the company’s first-time sponsorship of Teknofest Mining Technology competitions, establishment of an R&D center, international scholarship programs, and dedicated scholarships for students entering mining-related university programs. He closed by identifying four themes he expects to shape the sector going forward: intensifying global competition for critical minerals, transformative impact of AI and digital technologies, rising environmental and social expectations, and growing importance of international cooperation and resilient supply chains — positioning Turkey as aiming to be among the leading countries shaping this future.


  • Neo Performance Materials Finalises Transfer of Sarfartoq Interest to Greenland Mines

    Neo Performance Materials Finalises Transfer of Sarfartoq Interest to Greenland Mines

    Neo Performance Materials Inc. has successfully completed the transfer of its interest in the Sarfartoq Project to Greenland Mines Ltd., following the approval from the Government of Greenland. The transaction, valued at US$35 million, includes US$20 million in cash and US$15 million in shares of Greenland Mines. Neo retains a significant equity stake and offtake rights for up to 60% of the ore or mineral concentrate produced from the Sarfartoq Carbonatite Complex, located in Southwest Greenland.

    The merger, involving Neo’s wholly-owned subsidiary Neo North Star Holdings LLC and other shareholders of NNSR Holdings Inc., allows Greenland Mines to advance its leadership and investment in the Sarfartoq Project. Rahim Suleman, President and CEO of Neo, expressed confidence in the project’s future, highlighting Neo’s commitment as both a shareholder and an offtake partner. This strategic move aligns with Neo’s broader midstream and downstream growth strategy, ensuring that capital is effectively allocated to generate maximum value for customers and shareholders.

    Neo Performance Materials is known for manufacturing advanced industrial materials that are essential for various technologies, particularly those aimed at enhancing efficiency and sustainability. The company’s product portfolio includes magnetic powders, rare earth magnets, specialty chemicals, and alloys, which are critical for the performance of many everyday products and emerging technologies. With operations spanning multiple countries, including Canada, Estonia, China, Germany, Thailand, and the UK, Neo is well-positioned to contribute to the global transition towards net-zero technologies.

    This transaction marks a significant step for both Neo and Greenland Mines, as they look to leverage the potential of the Sarfartoq Project, which is expected to play a crucial role in the supply of critical minerals. The completion of this deal not only strengthens Neo’s position in the mining sector but also underscores the growing importance of sustainable practices in mineral extraction and processing. As the industry evolves, partnerships like this will be vital in meeting the increasing demand for rare earth elements and other critical materials necessary for modern technologies.


  • Tungsten Price Surge Highlights Supply Crisis and Future Demand Challenges

    Tungsten Price Surge Highlights Supply Crisis and Future Demand Challenges

    The tungsten market is experiencing a significant price surge, with prices increasing by 310% from January to July 2026, driven by Chinese export controls and rising military demand. According to a recent report from S&P Global, global first-use tungsten demand is projected to rise from approximately 162,000 tonnes of WO₃ in 2025 to 180,000 tonnes by 2030 and 202,000 tonnes by 2035. China remains the dominant player in the tungsten market, having produced 67,000 tonnes of the total 85,000 tonnes mined globally in 2025 and controlling about 85% of APT refining capacity.

    Despite the announcement of 11 new projects that could add about 20,000 tonnes of annual mine capacity outside China by 2030, S&P Global estimates a primary mine supply gap of 16,000 tonnes ex-China by 2030. This gap is concerning, especially as the price of tungsten APT has surged from approximately US$83/kg WO₃ in January 2026 to US$340/kg in July 2026. While the price increase has surpassed the theoretical investment hurdle for new supply, the real challenge lies in the development bottlenecks related to financing, permitting, and construction.

    The report highlights several key projects that could potentially deliver new tungsten supply, including the Sangdong project in South Korea, Hemerdon in the UK, and Northern Katpar in Kazakhstan. However, the timeline for these projects remains uncertain, and their success is contingent upon various factors, including financing and regulatory approvals.

    Tungsten is classified as a critical mineral due to its unique properties, which make it essential for various applications, including defence, industrial tools, and technology. The rising prices reflect a complex interplay of supply chain issues, geopolitical tensions, and strategic stockpiling, particularly in the context of US-China relations. As the US prepares to impose significant restrictions on tungsten imports from certain countries in 2027, the market is likely to face further challenges in meeting demand.

    While the current price levels may incentivise new tungsten supply, the industry faces significant hurdles in terms of project financing and development timelines. The tungsten market is at a critical juncture, with supply constraints likely to persist unless substantial investments and regulatory support are provided to facilitate new production.


  • Mkango Resources Completes Acquisition of Remloy Rare Earth Magnet Recycling Business

    Mkango Resources Completes Acquisition of Remloy Rare Earth Magnet Recycling Business

    Mkango Resources Ltd. has successfully finalised its acquisition of the Remloy rare earth magnet recycling business from Heraeus Amloy Technologies GmbH for €8 million (approximately US$9.3 million). This transaction, which was first announced on 20 May 2026, includes an initial payment of €5 million (around US$5.8 million) upon closing, with the remaining €3 million (approximately US$3.5 million) due on 28 August 2028, marking the second anniversary of the deal’s completion.

    Remloy operates a recycling facility in Bitterfeld, Germany, which employs a melting process to recycle end-of-life rare earth magnets. This process produces neodymium-iron-boron (NdFeB) alloy powders, catering to the bonded and hot-deformed magnet markets. The Remloy recycling method complements the short loop recycling process of HyProMag, which focuses on producing sintered magnets, and Mkango Rare Earths UK’s long loop recycling process aimed at generating mixed rare earth carbonates and oxides. The facility aims for a production capacity of at least 500 tonnes of NdFeB alloy powder annually.

    The acquisition comes with several advantages, including a fully commissioned production facility bolstered by substantial investments in equipment and feedstock. At the time of completion, Remloy had a significant stockpile of approximately 345 tonnes of end-of-life rare earth magnets and alloys, which will provide essential feedstock for both Remloy and HyProMag, supporting their growth strategies and creating future trading opportunities.

    Mkango’s CEO, William Dawes, expressed optimism about the acquisition, highlighting the potential to enhance the rare earth supply chain and recycling ecosystem in Germany and surrounding regions. He noted that Mkango is now strategically positioned across the entire rare earth supply chain in Europe and North America, with operations spanning recycling, magnet and alloy manufacturing in the UK, Germany, and the USA, as well as rare earth separation in Poland and mining activities in Malawi.

    David Bender, the newly appointed Managing Director of Remloy, emphasised the company’s readiness to scale up production and recycling capacities for rare-earth magnets. He believes that the integration into Mkango will significantly bolster supply chain resilience and security of supply in Europe, allowing Remloy to better serve its customers through enhanced synergies within the Mkango Group.

    Overall, this acquisition marks a significant step for Mkango Resources as it aims to solidify its position in the rare earth sector, particularly in the context of increasing demand for sustainable recycling solutions and the growing importance of rare earth materials in various industries.


  • EIT RawMaterials Proposes Strategic Model for European Critical Raw Materials Centre

    EIT RawMaterials Proposes Strategic Model for European Critical Raw Materials Centre

    The European Commission’s recent decision to establish a European Critical Raw Materials (CRM) Centre marks a significant step towards enhancing Europe’s raw materials policy framework and transforming it into industrial capability. EIT RawMaterials has expressed strong support for this initiative and is poised to take a leading operational role in its implementation, working under the strategic authority of the European Commission and Member States.

    In a newly published position paper, EIT RawMaterials outlines its vision for the CRM Centre, detailing how it can assist in translating Europe’s raw materials strategy into tangible industrial outcomes. The paper proposes a practical operating and delivery model for the CRM Centre, positioning EIT RawMaterials as a strategic partner and market-facing operational arm.

    Europe has already laid much of the necessary policy groundwork, with initiatives such as the Raw Materials Mechanism, CRMA Strategic Projects, RESourceEU, and the G7 Critical Minerals Action Plan amplifying the urgency for coordinated implementation. EIT RawMaterials emphasises that the CRM Centre should not merely add another layer of policy or data but should instead connect strategic intelligence with markets, projects, and finance. This connection is essential for executing European priorities into concrete industrial actions.

    The proposed model is structured around four interconnected pillars: strategic intelligence, market formation, strategic value-chain delivery, and stage-gated finance and de-risking. Strategic intelligence will focus on combining market, project, technology, and geopolitical insights to identify vulnerabilities and set action priorities. Market formation aims to qualify supply and demand, aggregate buyer requirements, and develop independent price references to encourage investment. Strategic value-chain delivery seeks to address the ‘missing middle’ in Europe’s processing and refining capabilities, while stage-gated finance will align project stages with appropriate funding mechanisms.

    Additionally, strategic stockpiling and preparedness are highlighted as crucial components that would enhance Europe’s resilience against disruptions and foster more robust supply chains in the long term. EIT RawMaterials already possesses a solid foundation for delivery, with its Metal & Mineral Platform M2i integrating over 2.5 million verified data points for informed decision-making. The investment pipeline managed by EIT RawMaterials exceeds €25 billion, and the organisation has successfully deployed more than €700 million across over 800 projects and startups, mobilising an additional €8.3 billion in investment.

    With these existing capabilities, Europe is not starting from scratch in building a new delivery ecosystem. EIT RawMaterials is prepared to facilitate a swift transition from strategy to implementation for the CRM Centre, should it receive the mandate from the European Commission and Member States.