An unidentified investor has acquired a 30% stake in Forum Muider Limited — the holding company that owns Bogatyr Komir, Kazakhstan’s largest coal producer — through a new share issuance that simultaneously diluted the stakes of both existing shareholders, state energy holding Samruk-Energo and Russian aluminium giant Rusal, raising transparency concerns about the privatisation of a strategically significant national asset.
According to Samruk-Energo’s 2025 financial statements, Forum Muider Limited issued and placed 7,779 new shares in favour of the new investor in the course of 2025. As a result, from 24 September 2025, the stakes of both Samruk-Energo and Rusal’s Miradore Enterprises Limited were reduced from 50% to 35% each, with the new investor holding the remaining 30%. Data from adata.kz identifies the third shareholder as a non-resident entity called Primet LLC.
Samruk-Energo’s exit from the structure is now imminent. On 30 December 2025, the national company signed an agreement to sell its remaining 35% stake to the same investor, subject to a number of conditions precedent including the signing of an undertaking agreement on the mechanism for declaring and paying historical dividends owed to both Samruk-Energo and Miradore at the level of both Bogatyr Komir and Forum Muider. The company’s management expects all conditions to be met and the transaction to close in 2026. Samruk-Energo had already classified the investment as an asset held for sale at year-end, valued at 77.1 billion tenge on its balance sheet, while recognising an impairment and disposal loss of 15.7 billion tenge during 2025.
The identity of the beneficial owner behind Primet LLC has not been publicly disclosed, prompting questions about whether the privatisation of Samruk-Energo’s stake in Kazakhstan’s largest coal enterprise is proceeding with adequate transparency.
Bogatyr Komir is a major contributor to Kazakhstan’s energy system. Its Bogatyr and Severny open-pit mines in Ekibastuz produced 45.3 million tonnes of coal in 2025 — a 6% increase on 2024 output of 42.7 million tonnes — supplying coal-fired power plants in Astana, Pavlodar, Petropavlovsk, Stepnogorsk, Almaty and Karaganda. The company raised its Ekibastuz coal prices by 30% last year and is planning a further 20% increase in July 2026. A cyclical-flow extraction technology upgrade at the Bogatyr mine is also planned, which is expected to significantly improve profitability.
The ownership restructuring follows a broader corporate reorganisation in which Forum Muider B.V., previously registered in the Netherlands, was merged into Forum Muider Limited — a company registered in Cyprus in 2023 — which then relocated to the Astana International Financial Centre jurisdiction in late October 2025.
О чем видео: Фокус на глобальном энергетическом переходе и экономике. По мере роста спроса на электромобили и чистую энергию начинается битва за критически важные минералы (литий, кобальт, редкоземельные элементы).
Ключевые детали: Видео объяснит концепцию «зеленого ресурсного проклятия» — ситуации, когда развивающиеся страны берут на себя весь экологический ущерб от добычи руды, экспортируют ее за бесценок, а затем вынуждены импортировать дорогие готовые технологии. Главной темой станет попытка Казахстана и Узбекистана вырваться из этой ловушки путем создания собственных заводов по переработке и рафинированию (midstream).
Видео подготовлено по материалам публикации “Central Asia as New Battle Grounds: Critical Mineral Strategies of Kazakhstan and Uzbekistan” в Journal of Eurasian Studies.
https://journals.sagepub.com/doi/epdf/10.1177/18793665261442863
Presidents Kassym-Jomart Tokayev and Recep Tayyip Erdoğan were presented with a package of joint investment projects during the Kazakhstani-Turkish summit in Astana, with five new initiatives expected to attract more than $920 million in investment and create over 3,100 jobs across Kazakhstan.
The projects span five regions and multiple sectors. In Abai Region, Turkish mining company Miryıldız plans to build a mining and processing plant — an extension of the company’s existing $480 million gold development programme at the Zhanan deposit. In Almaty, İskefe Holding intends to launch gelatin production. In Turkestan Region, Orzax Group will establish a modern facility for the production of dietary supplements. In Aktobe, S Sistem Lojistik is partnering with Kazpost to create a logistics centre at the city’s international airport. In Astana, Tiryaki Holding will build a plant for the deep processing of wheat and peas.
Deputy Prime Minister Serik Zhumangarin briefed the two heads of state on the broader trajectory of Turkish investment in Kazakhstan, noting that approximately 100 investment projects involving Turkish companies have already been completed in the country, with a combined value of around $4 billion across various economic sectors. A further 50 joint projects with a total estimated value of approximately $4 billion are currently being implemented, underscoring what Zhumangarin described as a high level of investment interaction between the two countries.
The death toll from the explosion at Glencore’s Kazzinc facility in Ust-Kamenogorsk has risen to three, Kazakhstani officials confirmed, as a joint investigative team comprising law enforcement, the state labour inspectorate and emergency services continues to work at the site.
Vice Minister of Labour and Social Protection Baurzhan Tuyakbayev told a Senate briefing that investigators are working to establish the precise cause of the incident, examining several possible factors including failure to observe safety regulations, inadequate worker safety briefings, a technological malfunction at the facility, or the continued use of outdated equipment. “We will find out the cause, and believe me, responsibility will follow,” he said.
Asked when the last workplace safety and industrial security inspection had been conducted at the facility, Tuyakbayev said large enterprises of Kazzinc’s scale fall within the highest-risk category — those employing between 5,000 and 10,000 workers — and are subject to annual preventive inspections. He said inspections of Kazzinc and other major enterprises had been carried out in both the previous year and the year before that, and that all compliance orders issued at the time had been fulfilled within the prescribed deadlines without the imposition of fines.
The explosion, which occurred on 5 May at the Kazzinc plant in Ust-Kamenogorsk, was followed by a fire and the partial collapse of a roof structure. Environmental officials in East Kazakhstan Region launched urgent air quality monitoring in the immediate aftermath. Prime Minister Olzhas Bektenov has personally taken control of the situation at the plant.
Turkey is emerging as a significant potential contributor to global critical minerals supply chain diversification, backed by its resource endowment — including the world’s second-largest rare earth element reserve — and its strategic geographic position connecting Asia, Africa and Europe, a senior OECD official has said.
Marion Jansen, director at the OECD Directorate for Trade and Agriculture, made the assessment on the sidelines of the OECD Critical Minerals Forum in Istanbul. “Türkiye is already an important player in critical minerals,” she told Anadolu Agency, pointing to the country’s strength as a major global supplier of borates and its significant rare earth reserves, discovered in the central province of Eskişehir in 2022. “This is one of the countries where more investment could take place,” she said. Turkey’s location also gives it a natural advantage as a logistics and transit hub. “Türkiye is situated between Asia, Africa and Europe. This is a fantastic trading hub.”
As a participant in the OECD’s export credit arrangement, Turkey also has a voice in coordinated international financing efforts for critical minerals projects — a mechanism Jansen described as increasingly important as the world works to broaden the supplier base for minerals essential to the energy transition, digitalisation and defence industries.
Jansen used the forum to deliver a pointed warning about the structural conditions undermining the global critical minerals market. In some markets, a single country accounts for up to 90% of global supply at either the extraction or processing stage. “This is not good,” she said, noting that excessive concentration distorts markets and prevents normal price formation, while high entry barriers limit the emergence of new participants.
On export restrictions, the OECD data she cited painted a concerning picture. The use of export restrictions on critical materials has increased nearly fivefold between 2009 and 2024 and remains at historically elevated levels, with the most severe measures — including outright export prohibitions — being deployed with growing frequency. “It becomes nearly acceptable to use it and that’s not good news for the multilateral trading system at all,” she said.
Investment in the sector faces its own structural challenges, Jansen noted. Mining and processing projects require long-term capital commitments in markets where price volatility is a real risk precisely because competition is limited. “If market conditions are not competitive, the risk that prices will be volatile is real,” she said, adding that addressing these investment barriers will be essential to unlocking the supply diversification the global economy needs.
China’s East Hope Group, one of the world’s largest producers of electrolytic aluminium and alumina, is progressing plans for a colossal $12.6 billion investment in Kazakhstan’s aluminium sector, according to the country’s Ministry of Industry and Construction.
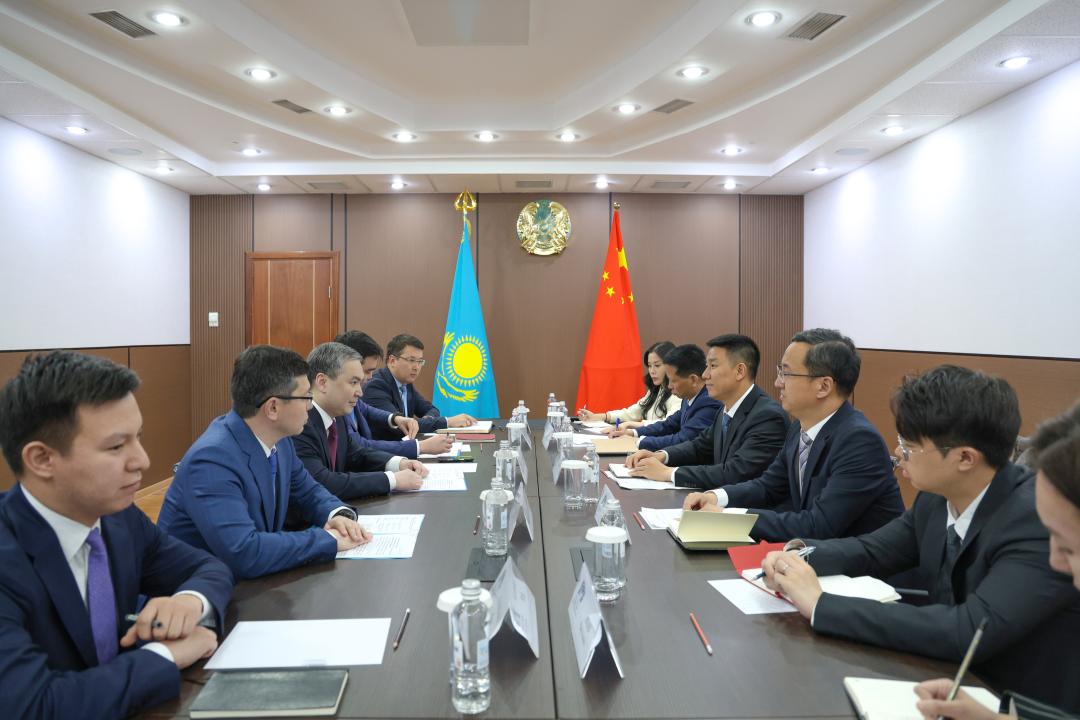
Kazakhstan’s Industry and Construction Minister Yersayin Nagaspayev held discussions with Chen Lei, East Hope Group’s Director for Strategic Investments. The two sides discussed establishing a full-cycle aluminium cluster within Kazakhstan, spanning the entire process from bauxite extraction through to primary aluminium output.
Nagaspayev emphasised that full-cycle production projects are in keeping with Kazakhstan’s state industrial policy, which is geared towards deeper processing and the manufacture of high-value-added goods.
The talks also covered the project’s current status, the formation of a raw materials base, and the development of production capacity and industrial cooperation. The company is currently undertaking geological exploration across multiple blocks in the Aktobe and Kostanay regions. The broader vision encompasses the development of 11 bauxite and coal deposits across the Kostanay and Aktobe regions, with the project expected to generate approximately 10,000 jobs once fully operational. KursivThe Times Of Central Asia
The initiative has been gathering momentum since February 2025, when East Hope registered a subsidiary in Kazakhstan to serve as the project’s principal operational centre. An investment framework agreement was subsequently signed between East Hope and the Kazakh government. The Times Of Central AsiaMysteel
As part of the scheme, East Hope Group intends to construct a 1-gigawatt coal-fired power station in the Kostanay region, whilst also exploring potential renewable energy ventures. The project is designed around circular economy principles, with the aim of creating a complete production cycle for green aluminium products. Qazaqgreen
Both parties reaffirmed their commitment to advancing the project and strengthening investment cooperation.
Kazakhstan’s Energy Minister Yerlan Akkenzhenov has met with senior leadership of China’s East Hope Group to discuss a series of major investment projects in Kostanay Region, including a proposed one-gigawatt coal-fired power plant intended to supply electricity to a new aluminium complex.
The meeting between Akkenzhenov and East Hope Group Chief Strategy Investment Officer Chen Lei covered the Chinese conglomerate’s plans to develop industrial and energy capacity in the region. Beyond the coal plant and aluminium complex, East Hope Group signalled interest in expanding into renewable energy and broader coal industry projects in Kazakhstan.
Akkenzhenov pledged the Ministry of Energy’s full support for initiatives that strengthen Kazakhstan’s industrial and energy capabilities, emphasising the importance of foreign investment, advanced technology adoption, localisation of production and the creation of high-value-added employment.
East Hope Group is one of China’s largest private industrial conglomerates, with extensive interests in aluminium smelting, silicon manufacturing and chemical industries, making it a strategically relevant partner for Kazakhstan’s ambitions to develop domestic aluminium processing capacity alongside its existing raw material base.
Turkish President Recep Tayyip Erdoğan is paying a state visit to Astana on 13 to 14 May at the invitation of Kazakhstani President Kassym-Jomart Tokayev, with the sixth meeting of the High-Level Strategic Cooperation Council between the two countries scheduled alongside broader bilateral talks. The visit will be followed on 15 May by an Informal Summit of the Organisation of Turkic States in Turkistan.
The diplomatic encounter arrives at a moment of sharp economic momentum. Bilateral trade between Kazakhstan and Turkey reached $1.13 billion in the first two months of 2026 alone, up 44.9% year-on-year from $777.6 million in the same period of 2025. Kazakhstan’s exports to Turkey surged 66.1% to $916.4 million, driven overwhelmingly by copper and oil, which together account for approximately 90% of export value. Copper and copper cathode supplies more than doubled to $515.7 million, while crude oil exports rose 31.7% to $314.5 million. The trade surplus in Kazakhstan’s favour more than doubled to $705.6 million.
Beyond the dominant commodities, notable growth was recorded in several other categories: unwrought aluminium rose 80-fold, unwrought zinc nearly 184-fold, and more technologically advanced exports including electric motors, pipeline fittings and automatic control instruments also expanded significantly. Turkey’s exports to Kazakhstan, while declining overall by 6.7%, showed growth in pharmaceuticals, prepared food products, electric generating sets and specialised industrial equipment — indicating a gradual shift toward finished goods and industrial supply.
The broader relationship has been three decades in the making. Turkey was the first country to recognise Kazakhstan’s independence on 16 December 1991, and bilateral relations have since evolved through three distinct phases — from cultural and political foundation-building in the 1990s, through the formalisation of a strategic partnership framework from 2009, to the current phase emphasising transport and logistics, energy, defence industry cooperation, digital technology and education. More than 5,000 companies with Turkish capital operate in Kazakhstan, Turkish investment over 20 years has totalled nearly $6 billion, and Kazakhstani investment in Turkey has exceeded $2.5 billion. The two countries aim to raise bilateral trade turnover to $10 billion.
A central pillar of the current partnership is the Middle Corridor — the trans-Caspian transport route connecting Central Asia, the South Caucasus, Turkey and Europe. World Bank estimates suggest cargo volumes along the corridor could triple by 2030 while transit times are halved, making logistics infrastructure one of the fastest-growing and most strategically significant dimensions of the bilateral relationship. In 2025 alone, the two sides signed 20 interstate and intergovernmental agreements covering energy, transport and logistics.
Analysts note that achieving the $10 billion trade target will require export diversification beyond copper and oil, development of processing industries and removal of logistical bottlenecks — challenges that both governments acknowledge as central to the partnership’s next phase.
A MINEX Forum Production: Escaping the Green Resource Curse in Central Asia
Welcome to this special deep-dive podcast episode, brought to you by the MINEX Forum. This episode is based on the groundbreaking research article, “Central Asia as New Battle Grounds: Critical Mineral Strategies of Kazakhstan and Uzbekistan,” authored by Younkyoo Kim, Lyailya Ivatova, Sujin Kang, and Yerden Ordabek.
Whether you are driving an electric vehicle in Europe, using a smartphone in the USA, installing solar panels in Australia, or relying on advanced semiconductors in South Korea, your daily life depends on an invisible, highly concentrated global supply chain. This introductory long-read breaks down the complex science and geopolitics of critical minerals, revealing why the true battleground for the future of green technology isn’t in the mines—it’s in the midstream.
The “Hourglass” Supply Chain and the Green Resource Curse
As the world accelerates its transition away from fossil fuels, the demand for critical minerals like lithium, cobalt, nickel, and rare earth elements is skyrocketing. However, a severe structural imbalance threatens the stability of this green revolution.
While the extraction of these minerals happens all over the globe, the capability to refine and process them is heavily monopolized. The global supply chain resembles an “hourglass,” where raw materials from dozens of countries flow into a tiny number of refining bottlenecks—predominantly in China, which controls 85% to 90% of the processing capacity for key elements like rare earths, lithium, and cobalt.
For resource-rich developing nations, this creates a dangerous trap known as the “green resource curse”
. Just as oil and gas historically led to corruption, economic volatility, and environmental damage in some nations, the rush for green minerals risks repeating the cycle
. Developing countries bear the heavy environmental and social burdens of mining, only to export low-value raw ores
. They are entirely excluded from the lucrative “midstream” stages—smelting, refining, and chemical separation—meaning they must ultimately buy back expensive, finished green technologies manufactured elsewhere.
The New Battlegrounds: Kazakhstan and Uzbekistan
Central Asia has emerged as a crucial “third zone” capable of disrupting these bottlenecks and offering a more secure supply chain to the world. But Kazakhstan and Uzbekistan are no longer content to simply dig dirt out of the ground; they are fighting for “midstream sovereignty” to capture the actual value of their natural resources.
Kazakhstan’s “New Oil” Kazakhstan, already a dominant force in global uranium production, is treating its vast rare earth element deposits as its “new oil”. The country holds massive potential, such as the Kuirektykol deposit which holds an estimated 28.2 million tons of rare earths. However, separating rare earth elements into high-purity industrial materials requires incredibly complex precision technology. To bridge this technological gap, Kazakhstan is rapidly attracting Chinese capital—recently launching a $300 million tungsten processing plant—while simultaneously courting Western nations and South Korea to avoid becoming entirely dependent on Beijing’s vertically integrated supply chains. Uzbekistan’s $2.6 Billion Masterplan Uzbekistan is taking a highly centralized, state-driven approach. The government has consolidated its critical mineral assets under a new entity, the Uzbekistan Technological Metals Complex (UzTMK), and launched a massive $2.6 billion investment program covering 76 different projects. Remarkably, Uzbekistan is also building its own domestic electric vehicle manufacturing base, partnering with companies like BYD to ensure that the minerals they extract can be used in factories right at home. To make its products attractive to strict Western markets, Uzbekistan is pioneering eco-friendly processing methods, such as a closed-loop system for molybdenum that slashes chemical emissions.
A New Model for Partnership
As Central Asia attempts to climb the value chain, it faces competing models of global partnership. The Chinese Model offers incredibly fast infrastructure development and capital, but threatens to lock Central Asian processing into China’s broader monopolies, stifling domestic technological independence. The Western Model (US & EU) focuses heavily on environmental, social, and governance (ESG) compliance and supply chain transparency. However, Western initiatives often emphasize financial de-risking over the actual transfer of the complex refining technologies these nations desperately need.
This gap has created an opening for an alternative approach, championed by middle powers like South Korea. Because South Korea is highly reliant on mineral imports (procuring over 82% of key battery minerals from China), it is highly motivated to help Central Asia succeed. Rather than just providing cash or demanding regulatory compliance, South Korea is utilizing a “Process-Embedded Industrial Partnership Model”. Through initiatives like the Uzbek-Korea Rare Metals Center, South Korea is actively transferring laboratory skills, high-purity separation techniques, and process engineering knowledge directly to the local workforce.
Why This Matters to You
The fight for midstream processing in Central Asia is not just a regional economic issue; it is the linchpin of global clean energy security. Escaping the green resource curse is the only way these nations can achieve sustainable industrialization, and diversifying the refining bottlenecks is the only way everyday consumers can rely on a stable, affordable supply of electric vehicles and renewable energy in the decades to come. Hit play on the podcast to listen to our hosts dive deeper into the strategies, the science, and the high-stakes geopolitical chess game defining the future of the global energy transition.
The global energy transition is creating a new form of resource dependency risk for mineral-rich developing countries — one that mirrors the classic extractive trap of the 20th century but operates under a green technological banner. A detailed comparative analysis of Kazakhstan and Uzbekistan argues that unless these countries can move beyond raw material extraction into the refining, smelting and separation stages of the critical minerals value chain, they risk becoming peripheral suppliers to a decarbonised global economy rather than industrial beneficiaries of it.
The paper’s central concept is the “green resource curse” — an extension of classic resource curse theory to the minerals powering electric vehicles, wind turbines and solar panels. While mining for lithium, cobalt, rare earth elements and battery metals is geographically dispersed across multiple continents, processing and refining capacity is extraordinarily concentrated. Between 60% and 90% of refining capacity for most key transition minerals sits in a single country or region — primarily China — creating what the authors describe as an hourglass-shaped supply chain in which global resource flows converge at a handful of strategic bottlenecks. Resource-rich countries bear the environmental costs of extraction while remaining excluded from the high-value industrial segments where technological learning and economic returns accumulate.
Kazakhstan and Uzbekistan represent the most instructive cases in the emerging “third zone” of critical minerals geopolitics — countries with broad mineral portfolios and growing state-led industrial strategies that are simultaneously being courted by China, the United States, the EU, Japan and South Korea. Kazakhstan holds the world’s third-largest rare earth reserves, produces 19 of the EU’s 34 critical raw materials, and is the world’s largest uranium producer. Uzbekistan holds significant reserves of tungsten, lithium, copper and rare earths, and has launched a $2.6 billion three-year investment programme across 76 mineral projects.
Yet both face the same structural bottleneck: the midstream. Kazakhstan’s SARECO joint venture — established between Kazatomprom and Japan’s Sumitomo to produce rare earth oxides at Stepnogorsk — has struggled to move beyond mixed rare earth extraction due to the precision demands of individual element separation. The technological difficulty of high-purity rare earth refining, particularly for heavy rare earth elements essential to permanent magnets, exceeds what can be resolved through capital investment alone. A significant share of Kazakhstan’s rare earth ores continues to be exported for processing abroad, primarily to China, which controls approximately 90% of global rare earth processing capacity.
China’s investment model — illustrated by the $300 million tungsten processing plant led by Chinese capital in Almaty Province — offers speed and scale but carries the risk of integrating Central Asian industrial capacity into Chinese supply chain networks rather than building domestic technological sovereignty. As Western regulatory frameworks including the US Inflation Reduction Act and the EU Critical Raw Materials Act increasingly scrutinise supply chain origin and ownership, Central Asian projects deeply embedded in Chinese capital may face market access constraints that negate the industrial gains achieved.
Western engagement offers regulatory alignment and ESG compliance but, the analysis argues, insufficiently addresses the technological dimension of midstream sovereignty. Financial de-risking mechanisms do not automatically generate domestic process engineering capability or separation expertise.
South Korea emerges as offering a potentially distinctive model — what the paper terms a “process-embedded industrial partnership.” Unlike capital-dominant Chinese integration or compliance-driven Western frameworks, the Korean approach emphasises the transfer of operational know-how, pilot plant design, high-purity separation techniques and workforce training alongside physical investment. The Uzbekistan-Korea Rare Metals Centre, combining geological analysis with separation technology design and applied research collaboration, exemplifies this model. Japan, meanwhile, has pledged ¥3 trillion ($19 billion) in Central Asian business investment over five years and brings what the paper describes as “technological depth and long-term institutional strength.”
The paper identifies four conditions that must be met to escape the green resource curse: internalising midstream processing and separation technologies that generate learning effects; reducing the carbon intensity of refining to preserve access to emerging carbon border adjustment regimes; diversifying external partnerships to avoid single-bloc dependency; and sustaining institutional learning through workforce development and domestic research capacity. Where these conditions are absent, mineral wealth risks reproducing volatility, dependency and unequal value capture — even within a decarbonised economy.