Website: Asia.com

  • China’s Zhaojin Mining Eyes West African Acquisitions as US and European Miners Exit and Gold M&A Wave Accelerates

    China’s Zhaojin Mining Eyes West African Acquisitions as US and European Miners Exit and Gold M&A Wave Accelerates

    Chinese gold miner Zhaojin Mining Industry is actively seeking to acquire additional gold mines in Africa and other regions, targeting assets being exited by European and American miners in politically stable West African countries including Côte d’Ivoire, Ghana and Guinea, the company’s chief investment officer has said.

    Speaking in an interview, Xu Jianzhuo said Zhaojin is also evaluating projects in Central Asia and the Asia Pacific as part of a broader international expansion strategy. The company’s first major overseas move came in 2024 with the acquisition of assets in Côte d’Ivoire, where the Abujar mine is on track to produce four to five tonnes of gold this year in line with earlier guidance.

    Zhaojin’s ambitions reflect a wider acceleration in gold sector consolidation. Record gold prices have driven miners globally to step up acquisitions, and Chinese companies have emerged as active participants in the M&A wave. Zijin Mining, Zhaojin’s largest domestic peer, moved earlier this year to acquire Canada’s Allied Gold Corp for $4 billion, adding mines in Mali, Côte d’Ivoire and Ethiopia to its portfolio.

    Xu described the M&A environment as highly active and expected the trend to intensify. “Gold M&As are very active at the moment. The trend will only become stronger. Even under such high gold prices, we still see deals being carried out to boost scale,” he said, adding that post-merger asset disposals by larger miners create additional acquisition opportunities for Chinese firms looking to pick up non-core properties.

    On gold prices, Xu said the recent pullback triggered by the Iran war is likely temporary, with structural drivers including central bank buying and dollar diversification remaining firmly intact.

    Beyond gold, Zhaojin is also building copper exposure, though Xu said the company would approach the industrial metal with caution given its high capital requirements. The focus is on relatively small copper projects in southern African countries including Namibia and Botswana. Zhaojin’s Hong Kong-listed shares have rallied more than 50% over the past year.

  • Turkey Plans $600 Million Investment to Turn Beylikova Into World Top-Five Rare Earth Producer With 1,500 Jobs

    Turkey Plans $600 Million Investment to Turn Beylikova Into World Top-Five Rare Earth Producer With 1,500 Jobs

    Turkey is moving to transform its Beylikova rare earth project from pilot operations into full industrial-scale production with a planned $600 million investment across three facilities, as Ankara positions itself to enter the global top five rare earth producers and capture value beyond raw material extraction.

    Energy and Natural Resources Minister Alparslan Bayraktar announced the investment commitment while highlighting the scale of the Beylikova deposit in Eskişehir Province, which the Energy Ministry describes as holding 694 million tonnes of rare earth elements — the world’s second-largest reserve after China’s Bayan Obo deposit at 800 million tonnes. “Beylikova is a project the whole world is watching. We aim to rank among the top five globally in rare earth elements,” Bayraktar said.

    The three planned facilities are expected to create close to 1,500 jobs in Eskişehir, a city the minister described as already a central hub for mining and industry and one that hosts globally significant boron reserves. The new investments, he said, could push Eskişehir into a leading position in Turkey’s broader industrial landscape, with mining acting as a driver of wider economic activity.

    Bayraktar signalled a clear strategic direction beyond extraction, emphasising that Turkey’s approach to its rare earth endowment must generate value at every stage of the supply chain. “We should not limit ourselves to raw materials. We need to transform them into intermediate and final products,” he said — a position consistent with the broader shift among mineral-rich nations to capture processing and manufacturing value rather than exporting raw ore.

    Environmental standards and worker safety were also cited as central priorities for the project, with the minister stressing that mining activities must align with environmental requirements rather than operate at their expense — a consideration that will be important for attracting Western industrial partners and offtake agreements.

  • Kazzinc Explosion Reignites Debate Over Glencore Sale as Analyst Warns Kazakhstan Must Not Let Foreign Investor Exit Without Cleaning Up

    Kazzinc Explosion Reignites Debate Over Glencore Sale as Analyst Warns Kazakhstan Must Not Let Foreign Investor Exit Without Cleaning Up

    The fatal explosion at Glencore’s Kazzinc facility in Ust-Kamenogorsk on 5 May has thrown fresh scrutiny on the planned sale of the company to Kazakhstani businessman Shakhmurat Mutalip, with financial analyst Rasul Rysmambetov warning that any rushed transaction risks allowing a wealthy foreign investor to exit without resolving environmental liabilities that have accumulated for decades.

    Glencore has held a 70.2% stake in Kazzinc since 1997, with the remaining approximately 30% held by Tau-Ken Samruk, a subsidiary of sovereign fund Samruk-Kazyna. Bloomberg has reported that Mutalip is considering acquiring Glencore’s stake at a valuation of around $3.5 billion. In January 2026, Mutalip registered two new structures at the Astana International Financial Centre — KazZinc Group Ltd and Central Asia Resources Holding Ltd — though no official confirmation of a deal has been made. Tau-Ken Samruk has said it has no intention of selling its own stake.

    Rysmambetov, commenting to Kursiv, argued that the explosion and the broader ownership question should not be separated from Kazzinc’s long-standing environmental record. “Kazzinc is probably one of the largest polluters in East Kazakhstan Region. The state ignored this for a long time,” he said. He noted that the facility has never faced penalties comparable to those imposed on oil companies in western Kazakhstan, despite generating significant pollution. Residents of Ust-Kamenogorsk have long complained about air quality, and Rysmambetov said the situation had become serious enough that people were being advised not to go outside.

    On the prospective sale, the analyst was sceptical about both its urgency and the buyer’s financial capacity. “A rushed buyout is not necessary, in my view. The environmental situation needs to be fixed first,” he said. He also questioned whether Mutalip has sufficient funds to finance a transaction of this scale while simultaneously acquiring other major assets — Mutalip has already bought gold producer Altynalmas and is reportedly pursuing a 40% stake in ERG.

    The deeper concern Rysmambetov raised was one of structural accountability. If Glencore sells before addressing environmental liabilities, the cost of remediation would fall entirely on the new Kazakhstani owners. “It will turn out that Kazakhstani businesspeople buy it and then fix the ecology, while the investors are let go in peace — even though they earned enough to have paid attention to environmental problems,” he said.

    Kazzinc generated $5.1 billion in revenue in 2025 according to Glencore’s preliminary financial reporting.

  • Kazakhstan Emerges as Washington’s Key Central Asian Partner in Critical Minerals Race Against China — But Partnership Needs Depth Beyond Dialogue

    Kazakhstan Emerges as Washington’s Key Central Asian Partner in Critical Minerals Race Against China — But Partnership Needs Depth Beyond Dialogue

    Kazakhstan has become a focal point of the United States’ effort to build a non-Chinese critical minerals supply chain, with a combination of vast geological endowment, political will and recent high-level investment commitments elevating the Central Asian nation’s strategic profile in Washington’s resource diplomacy — even as analysts warn that the partnership remains tilted toward dialogue over concrete industrial action.

    The backdrop is a decade-long escalation between the US and China that has placed critical minerals at the centre of global trade competition. China controls approximately 60% of global critical mineral production and 85% of processing capacity, and supplied over half of US demand for 24 critical minerals and 90% of rare earth element demand in 2024. Beijing has repeatedly deployed that dominance as a trade weapon, imposing progressive export controls on gallium, germanium, graphite, tungsten, tellurium, molybdenum, indium and bismuth during periods of tariff escalation. The vulnerability those controls expose has made diversification of mineral supply chains a strategic imperative for Washington.

    Kazakhstan occupies a compelling position in that diversification effort. The country holds 21 of the 50 minerals classified as critical by the United States — including uranium, copper, chromite, gold, titanium, tungsten and rare earth elements — and may contain the world’s third-largest rare earth reserves. Mining accounts for 12% of GDP. In 2025, Kazakhstan allocated $127 million to geological exploration, more than any other Central Asian state.

    The bilateral architecture has developed rapidly. The US launched the C5+1 Critical Minerals Dialogue in 2024 to foster cooperation across the Central Asian region from exploration through processing, and held a US-Kazakhstan Strategic Energy Dialogue the same year, backed by a signed memorandum of understanding. Kazakhstan joined the Minerals Security Partnership Forum alongside major economies including the EU, Australia and Japan.

    The most tangible commitment came at the C5+1 Summit in Washington in November 2025, when US investment firm Cove Capital agreed to allocate $1.1 billion to the development of Kazakhstan’s largest tungsten deposits at Upper Kairakty and North Katpar, backed by $900 million in Export-Import Bank financing — a level of government support that signals genuine strategic commitment rather than diplomatic gesture.

    Yet the overall pattern remains uneven. Most US-Kazakhstan minerals engagement has focused on frameworks and agreements rather than operational projects. The US currently accounts for only 5% of Kazakhstan’s critical minerals exports, compared with 27% going to China and 16% to Russia. Analysts argue that to meaningfully compete with China’s embedded position — built through decades of direct investment, engineering capacity, infrastructure integration and offtake arrangements — the US must move beyond resource extraction agreements toward integrated projects that include geological exploration, processing capacity development, technology transfer and downstream industrial linkages.

    President Kassym-Jomart Tokayev has publicly emphasised the importance of US cooperation in developing Kazakhstan’s critical minerals sector, and the Kazakhstani government’s own interest in diversifying away from Chinese and Russian market dependence aligns with Washington’s goals. Whether the partnership translates into durable industrial outcomes will depend on whether bilateral agreements are upgraded to include financing commitments, timelines, technology transfer provisions and enforcement mechanisms comparable to the more detailed frameworks the US has established with Australia and Japan.

  • Uzbekistan Halts IPO Preparations for World-Class Gold Producer Navoi Mining as Government Reassesses Terms and Timing

    Uzbekistan Halts IPO Preparations for World-Class Gold Producer Navoi Mining as Government Reassesses Terms and Timing

    Uzbekistan has temporarily suspended preparations for the initial public offering of the Navoi Mining and Metallurgical Combine, one of the world’s largest gold producers, as the government reassesses market conditions and the optimal parameters for what would be one of Central Asia’s most significant capital markets transactions.

    According to sources cited by UzDaily, the government is reviewing both the timeline and the structure of the IPO, with all previously discussed schedules now open-ended. Earlier plans had envisaged a dual listing on the London and Tashkent stock exchanges, with a target of selling up to 5% of the company’s shares on international markets — a strategy that had already superseded an earlier consideration of a domestic “people’s IPO” format. Two percent of NGMK’s shares had been transferred to Uzbekistan’s State Assets Management Agency to support pre-sale preparation and deal structuring.

    Analysts suggest the pause may reflect concerns that partial privatisation could reduce the dividend flow the state currently receives from the company — a significant consideration given NGMK’s financial performance. In 2025, the combine produced approximately 3.2 million ounces of gold, with revenues rising 46% to $10.8 billion and pre-tax profit surging 71% to $6.1 billion. At that scale, even a modest reduction in state dividend receipts would represent a material budgetary impact.

    The suspension does not signal a retreat from Uzbekistan’s broader privatisation programme. Other candidates previously mooted for public listings include uranium producer Navoiyuran and the national carrier Uzbekistan Airways, and the government has indicated it intends to continue advancing those processes alongside a reassessment of NGMK’s IPO parameters, format and potential listing venues.

  • TETHYS and Hartree Announce Life‑of‑Mine Offtake Agreement for the Cataltepe Polymetallic Project in Türkiye

    TETHYS and Hartree Announce Life‑of‑Mine Offtake Agreement for the Cataltepe Polymetallic Project in Türkiye

    TETHYS, a Turkish-incorporated critical minerals and strategic infrastructure platform with projects across Eurasia, and Hartree Metals LLC, a subsidiary of the global commodities firm Hartree Partners LP — a leading independent commodities trading and asset management company — have entered into a life-of-mine offtake and commercial prepayment arrangement to support concentrate exports from the Cataltepe polymetallic mining project in north-western Türkiye.

    The agreement establishes a long-term commercial partnership between the two companies, anchored on the Cataltepe operation. Production from the mine is expected to be processed at the Kalkım flotation facility, generating zinc, lead, and copper concentrates for export to international smelting markets.

    Under the arrangement, Hartree Metals has provided a commercial advance payment to support the restart of operations and ongoing production activities, and will purchase and export 100% of the zinc, lead, and copper concentrates produced for the life of the operation. Production at Cataltepe is expected to commence shortly, with monthly shipments increasing progressively as operations ramp up.

    The transaction demonstrates a shared commercial understanding of the project and a mutual commitment to establishing reliable concentrate supply chains in Türkiye. For TETHYS, the agreement represents the commercial activation of its flagship Turkish operation and a significant milestone in its broader strategy to develop a multi-country portfolio of critical mineral assets across Eurasia. For Hartree Metals, it signifies a deepening of its commercial engagement with Türkiye’s expanding mining sector.

    Prof. Dr Leyla Keser, Chairperson of TETHYS Gateway Trading LLC, said: “The Cataltepe offtake agreement is a landmark transaction for TETHYS and a strong endorsement of the project’s commercial potential. We are delighted to be partnering with Hartree Metals as our long-term trading partner and look forward to building on this relationship as TETHYS continues to develop its portfolio of mineral assets across the region.”

  • Uzbekistan–Turkey Business Forum: A Key Opportunity for MINEX Forum Partners

    Uzbekistan–Turkey Business Forum: A Key Opportunity for MINEX Forum Partners

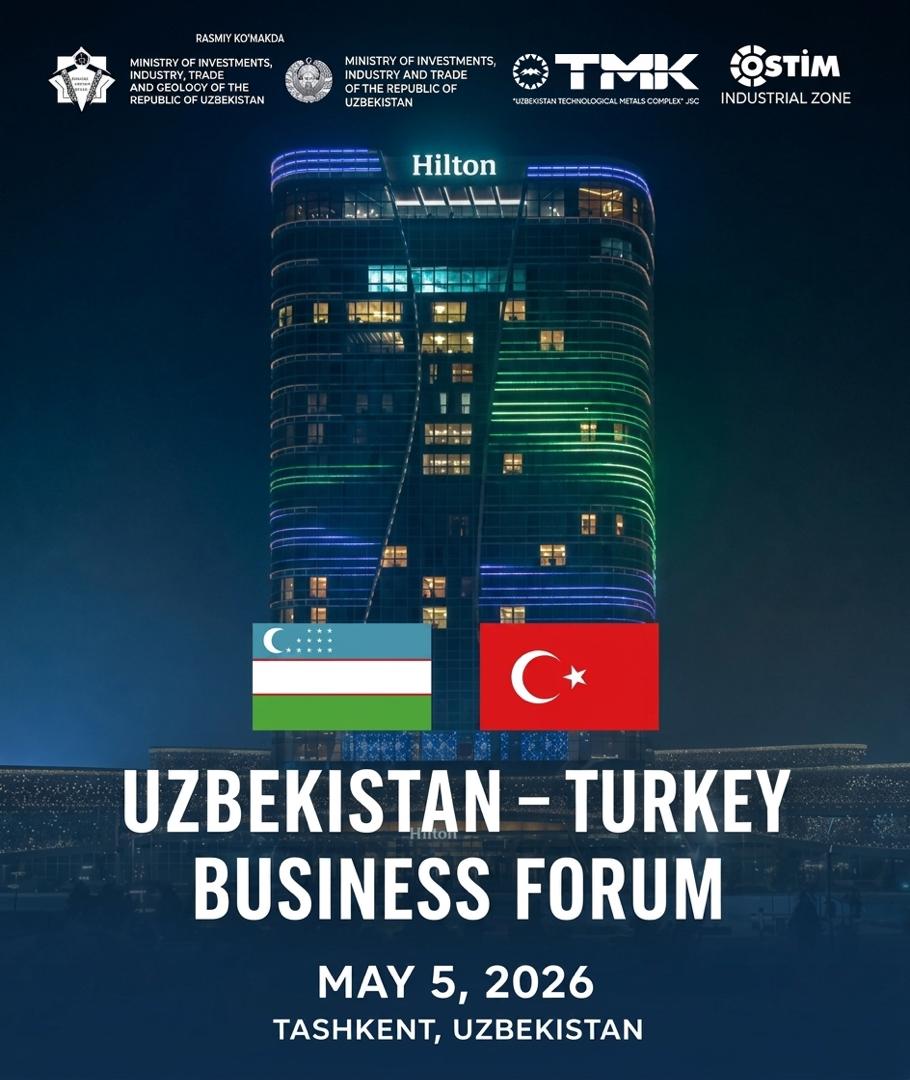
    The MINEX Forum team is delighted to participate in the upcoming Uzbekistan–Turkey Business Forum on 5 May at the Hilton Hotel. This event serves as a vital precursor to our broader regional discussions, focusing on concrete industrial proposals and joint investment ventures.

    The forum is a collaborative effort between OSTIM, the Ministry of Mining Industry and Geology of Uzbekistan, and TMK. It offers a deep dive into Uzbekistan’s ambitious industrial roadmap, specifically focusing on critical minerals and deep processing.

    Key highlights include presentations on:

    • The R&D Park for critical minerals.

    • Technopark initiatives for high-value metal processing.

    • Graphtech’s latest mining developments.

    Our representatives will be on the ground to discuss how these initiatives align with the broader goals of value creation and regional connectivity that we champion at MINEX. We invite our colleagues and partners to join us for a day of high-level networking and strategic planning.

  • Kazakhstan’s Copper Sector: Strategic Asset in a Tightening Market

    Kazakhstan’s Copper Sector: Strategic Asset in a Tightening Market

    Kazakhstan rarely commands the attention its copper endowment deserves. Producing roughly 900,000 tonnes annually from 35 million tonnes of registered reserves, it accounts for approximately 4% of global copper output — a share comparable to many of the names that dominate industry headlines. Yet Western investment community engagement with the sector remains shallow relative to the opportunity, and the geological case for what remains undiscovered is, if anything, more compelling than the production figures alone suggest.

    At a recent British-Kazakh Society webinar on copper in Kazakhstan — convened jointly with the Embassy of Kazakhstan in London and the UK Department of Business and Trade — geologists, exploration executives, and market analysts gathered to examine the sector in detail. The discussion made one thing clear: Kazakhstan’s copper story is not simply one of existing production. It is one of a sector arriving at a structural inflection point at precisely the moment the global market needs it most.

    The Resource Base

    Kazakhstan’s copper reserves are concentrated in two mature producing provinces. The Zhezkazgan deposit in central Kazakhstan is one of the great sediment-hosted copper systems on earth, developed since the post-war Soviet era and still the backbone of national production. Eastern Kazakhstan contributes largely through complex polymetallic deposits, of which Aktogai — a world-class porphyry system — is the most prominent. Together these provinces underpin an annual output of around 900,000 tonnes, placing Kazakhstan comfortably among the world’s significant copper producers.

    The registered reserve figure of 35 million tonnes, however, almost certainly understates the country’s true endowment. USGS analysis of undiscovered global copper potential consistently identifies central and eastern Kazakhstan as among the most prospective territories on earth for porphyry copper systems. Two distinct porphyry belts cross the country. The younger Valerianov Belt connects, across the Uzbek border, to the super-giant Kalmakyr deposit; that belt, within Kazakhstan, remains largely undrilled. A substantial portion of central Kazakhstan lies beneath Aral Sea basin sediments with no surface outcrop and minimal modern exploration coverage. What has been found is not broadly what exists.

    The Data Opportunity

    Unlocking Kazakhstan’s exploration frontier depends significantly on data — and here, material progress is underway. The National Geological Service has scanned 97.5% of its Soviet-era archive, a vast repository of maps, drill logs, and technical reports accumulated over decades of intensive geological work. An AI and OCR programme now underway aims to render that material machine-readable by mid-2027, and a unified digital subsoil platform will eventually integrate it with online licensing and compliance functions.

    The Soviet geological archive has long been one of Central Asia’s most underleveraged assets — rich in detail, largely inaccessible to modern analytical methods. As that changes, the information barrier that has historically complicated early-stage investment decisions in Kazakhstan will begin to fall. The same technology has implications for Uzbekistan, Mongolia, and other jurisdictions carrying similar archival burdens.

    The Exploration Dynamic

    Despite over 3,500 active exploration licences — a market that has grown dramatically since Kazakhstan’s current mining code opened competitive licence pegging — major mining companies outnumber junior explorers among active operators. This is structurally unusual for a jurisdiction at Kazakhstan’s stage of geological maturity. Seventy percent of the world’s mineral discoveries are made by junior companies. The early-stage risk capital that drives discovery is underdeveloped relative to the opportunity.

    That is beginning to shift. Aurora Minerals Group, a Kazakh-rooted exploration services company with international technical partnerships, has spent years systematically de-risking early-stage copper targets — culminating in First Quantum Minerals taking an earn-in position on the Lakeside porphyry project in the northern Balkhash district. A second project targeting sediment-hosted copper in the Tenis Basin, an analogue setting to the Zhezkazgan deposit, is entering its first field season on ground only recently opened by the government for exploration. The model — patient local knowledge combined with international technical and capital partnerships — is one the market needs more of.

    Market Dynamics and Kazakhstan’s Position

    The global copper market is broadly balanced today, but the trajectory is clear. A supply deficit of around 140,000 tonnes is expected this year, widening materially into next. Exchange stocks, inflated by the US tariff distortion that pulled copper from China and Europe into COMEX warehouses at premiums of up to $3,000 per tonne above LME, are elevated but unwinding. Underneath the short-term noise, the structural picture is one of tightening supply against demand that governments and industries across the developed world are now treating as a strategic priority rather than a market variable.

    Kazakhstan sits well within that supply picture. It produces 24 of the 36 minerals identified in the UK’s critical minerals strategy. Its copper is exported into global supply chains that are increasingly subject to scrutiny over reliability and geopolitical exposure. The Astana International Financial Centre provides an internationally anchored legal framework. There is explicit political will to support long-term foreign investment — not extractive engagement, but sustained industrial partnership.

    The friction points are real: dual reserve reporting systems under GKZ and KAZRC create disclosure complexity for internationally oriented investors; permitting timelines warrant attention; and Kazakhstan’s position between China and a reengaging Western investment community requires careful navigation. None of these are disqualifying. All are manageable with the right local knowledge and structuring.

    The copper market’s structural shift is not speculative. The demand is real, the supply constraint is real, and the timeline for bringing new production online is unforgiving. Kazakhstan, with a large established production base, a geologically compelling frontier, and an improving investment environment, is one of the few jurisdictions that can contribute meaningfully to closing that gap — if the engagement comes early enough to matter.
  • EU Trade Chief Vows to Fight “Tooth and Nail” for European Jobs as China Threatens Retaliation Over Industrial Policy

    EU Trade Chief Vows to Fight “Tooth and Nail” for European Jobs as China Threatens Retaliation Over Industrial Policy

    The European Union will not retreat from its industrial sovereignty agenda despite Chinese threats of retaliation, EU Trade Commissioner Maroš Šefčovič has declared, issuing one of his most combative statements yet on the deteriorating state of EU-China trade relations.

    Speaking exclusively to Euronews, Šefčovič said the bloc would “always” defend the interests of its companies and workers. “We will fight tooth and nail for every European job, for every European company, for every open sector, if we see they are treated unfairly,” he said, responding to Beijing’s threat of countermeasures over the EU’s Industrial Acceleration Act and its Cybersecurity Act — two pieces of legislation China has accused of discriminating against its companies.

    Relations between Brussels and Beijing have deteriorated sharply over the past year. China has tightened export controls on rare earths vital to Europe’s clean technology and defence industries and restricted semiconductor chips essential to the automotive sector, intensifying pressure on already strained supply chains. In response, the EU has pressed ahead with legislation tightening market access for foreign companies and potentially restricting Chinese telecoms firms’ presence across the bloc — prompting Beijing to warn that the EU should not underestimate China’s “firm resolve” to safeguard its interests.

    Šefčovič rejected characterisations of the situation as a looming trade war but was unequivocal that Brussels would not operate under pressure. “We never threaten our partners, and we certainly don’t do it through the media,” he said. “What we need is strategic patience and a great deal of courage.” He noted that a trade conflict is easy to start but difficult to exit — a warning he appeared to direct as much at Beijing as at domestic audiences.

    At the heart of the EU’s grievances is a trade deficit with China that reached €359.3 billion in 2025 — a level Šefčovič described as “simply unsustainable” and one showing no signs of improvement despite repeated EU calls for rebalancing. Brussels is also growing increasingly concerned that Chinese exports being shut out of the US market by higher tariffs are being redirected toward Europe, compounding existing overcapacity concerns.

    Šefčovič said he had invited China’s foreign minister to Brussels for a comprehensive assessment of the current state of relations, stressing that what he wants is “constructive engagement” rather than escalation. He defended the EU’s industrial policy ambitions by pointing to equivalent frameworks elsewhere: “There are very strong industrial policies in China. You have the same in the US, in Canada, in Japan and in Korea. So nobody should be surprised if the European Union responds in kind.”

  • China Threatens Countermeasures Against EU Industrial Acceleration Act, Warning of WTO Violations and Investment Discrimination

    China Threatens Countermeasures Against EU Industrial Acceleration Act, Warning of WTO Violations and Investment Discrimination

    China has launched a formal diplomatic offensive against the European Union’s Industrial Acceleration Act, warning that the bloc’s strategy to boost domestic manufacturing could violate World Trade Organisation rules and constitute institutional discrimination against foreign investors — and signalling that retaliatory countermeasures may follow if dialogue fails.

    China’s Ministry of Commerce delivered formal feedback to the European Commission on Friday and went public with its criticism on Monday, with a spokesperson arguing that the Act imposes numerous restrictive requirements on foreign investment. At the heart of Beijing’s objection is the EU’s use of preferential “EU origin” tags in public procurement and public support policies — conditions the Chinese government says amount to investment barriers and discriminatory treatment of non-European companies.

    The spokesperson said China is willing to engage in dialogue with the EU to mitigate the policy’s impact, but made clear that if those discussions fail to produce results, Beijing is prepared to take countermeasures to “firmly safeguard” its business interests. The European Commission’s response was measured. Spokesperson Olof Gill said the bloc’s proposals are “carefully calibrated to achieve certain economic wider goals for our citizens” and that the Commission remains open to engagement with global partners.

    The Industrial Acceleration Act, launched by the European Commission in March, targets three strategic sectors: clean technologies, car manufacturers and energy-intensive industries including aluminium, steel and cement. It includes domestic content thresholds of 70% EU-content for electric vehicles, 25% for aluminium and 25% for cement. The measures are designed to direct public procurement and state support toward European producers, reducing industrial dependencies and strengthening economic sovereignty.

    European Commissioner for Industry Stéphane Séjourné framed the initiative as a direct response to a mounting employment crisis. More than 200,000 European jobs have been lost in energy-intensive industries and the automotive sector since 2024, with projections pointing to 600,000 further losses in car-making alone this decade. The proposal must still be approved by the European Parliament and the European Council before it can enter into force.