Website: Europe.com

  • Metinvest’s ESG Practices: How Transparency and Accountability Are Paving the Way to the EU Market

    Metinvest’s ESG Practices: How Transparency and Accountability Are Paving the Way to the EU Market

    Ukrainian industrial giant Metinvest is proactively addressing the European Union’s escalating sustainability-reporting requirements, viewing robust Environmental, Social, and Governance (ESG) practices not just as an advantage but as a necessity for accessing the EU market.

    At a recent training session organized by the Federation of Employers of Ukraine (FEU) and the Danish Business Association, Kristina Rusnak, Metinvest’s ESG and Sustainable Finance Manager, shared the company’s extensive experience in implementing ESG practices, managing sustainability risks, and preparing for new reporting mandates. She also highlighted Metinvest’s commitment to social responsibility during wartime.

    The session brought together experts from the FEU, the Confederation of Danish Industry, and other leading Ukrainian companies to discuss the EU’s new regulations, particularly the Corporate Sustainability Reporting Directive (CSRD). A key takeaway was the concept of Double Materiality Assessment, which considers both a company’s impact on the environment and society, and how those factors, in turn, affect the business itself.

    Why ESG Matters for Metinvest:

    Rusnak emphasized that adhering to ESG principles helps Metinvest:

    • Reduce Risks: Mitigating risks related to environmental protection, employee safety, regulatory compliance, and corporate governance.
    • Enhance Resilience and Stability: Bolstering the company’s overall resilience and financial stability.
    • Meet Regulatory Pressure: Responding to EU requirements like the CSRD and the planned Carbon Border Adjustment Mechanism (CBAM).
    • Secure Financing: Meeting ESG criteria increasingly applied by international and Ukrainian banks and investment funds.
    • Address Consumer Demand: Catering to growing consumer demand for transparency and environmental responsibility throughout supply chains.

    Navigating the EU’s New Rules (CSRD):

    The CSRD, set to replace the Non-Financial Reporting Directive (NFRD), will significantly expand ESG reporting requirements. From 2028, even large, unlisted companies connected to the EU market will need to publish detailed sustainability reports.

    Metinvest’s approach to implementing ESG begins with identifying material topics – understanding its impact on people and the environment, and vice versa. These topics are updated annually using the Global Reporting Initiative (GRI) Standards. Subsequently, the company selects indicators to track progress across all ESG areas, including detailed environmental data.

    “In wartime, social responsibility takes on particular significance. Metinvest has already allocated more than US$250 million to support the Armed Forces of Ukraine, humanitarian projects and aid to civilians,” Rusnak stated.

    Metinvest annually publishes its sustainability data on its website, aligning with recommendations from the GRI, Sustainability Accounting Standards Board (SASB), and the Task Force on Climate-related Financial Disclosures (TCFD).

    Metinvest’s Reporting Journey:

    Metinvest’s commitment to sustainability reporting dates back to 2008 with its first corporate social responsibility report based on GRI standards. Key milestones include:

    • 2019: Annual sustainability reports incorporating SASB standards and initial materiality assessments.
    • 2021: First integrated report combining sustainability data with financial results.
    • Last Year: First disclosure of climate-related practices, including risk assessment under Paris Agreement scenarios and a shift in corporate governance to focus on climate change.

    The company also uses three ESG ratings to track progress and identify areas for improvement.

    Governance and Risk Management:

    Metinvest’s ESG practices are guided by principles of accountability, transparency, and alignment with international standards. Core areas like community engagement, workforce relations, occupational health and safety, and environmental protection are governed by internal policies and overseen by the Supervisory Board through dedicated committees and executive directorates.

    In 2024, climate governance was integrated, now supervised by the Health, Safety and Environmental Committee. The Internal Audit Directorate monitors ESG risks and reports annually to the Supervisory Board’s Audit and Finance Committee.

    Furthermore, Metinvest operates a Code of Ethics for all employees and, in 2024, adopted a Human Rights Policy extending to partners. An anonymous Trust Line is available for reporting misconduct. The company also enforces a Code of Business Conduct for all suppliers, with compliance being a mandatory condition for doing business.

    Metinvest continuously reviews and mitigates ESG risks, including emerging threats like climate-related challenges (CBAM and global climate change) and wartime labour shortages. The company is actively strengthening its climate-risk management system, exploring low-carbon technologies, launching decarbonisation initiatives, and expanding human-capital programmes, including pay rises, enhanced employee support, and veteran-focused initiatives.
  • South Korea Shows Interest in Ukrainian CRMs

    South Korea Shows Interest in Ukrainian CRMs

    Investment firm BGV Group Management recently showcased Ukraine’s potential as a future hub for critical raw materials at the Asian Leadership Conference 2025 in Seoul.

    During the panel discussion “The Foundation of the Future Economy: Energy and Critical Minerals,” BGV presented its projects, framing Ukraine as a reliable supplier for global supply chains and a nation capable of delivering innovative industrial solutions.

    Sergii Voitsekhovskyi, a board member at BGV Group Management, provided an update on the Group’s progress across various production areas. Notably, the BGV Graphite project at the Balakhivske deposit in the Kirovohrad region has successfully produced spherical graphite (SPG) samples. This marks a significant step towards developing advanced CSPG manufacturing technology. Ongoing work, in collaboration with international firms like Finland’s Metso and America’s AETC, includes testing for coated spherical graphite, battery production, thermal enrichment, and the development of basic engineering for the enrichment plant.

    Mr. Voitsekhovskyi also highlighted Ukraine’s promising prospects in developing beryllium, titanium, zirconium, molybdenum, and rare earth elements.

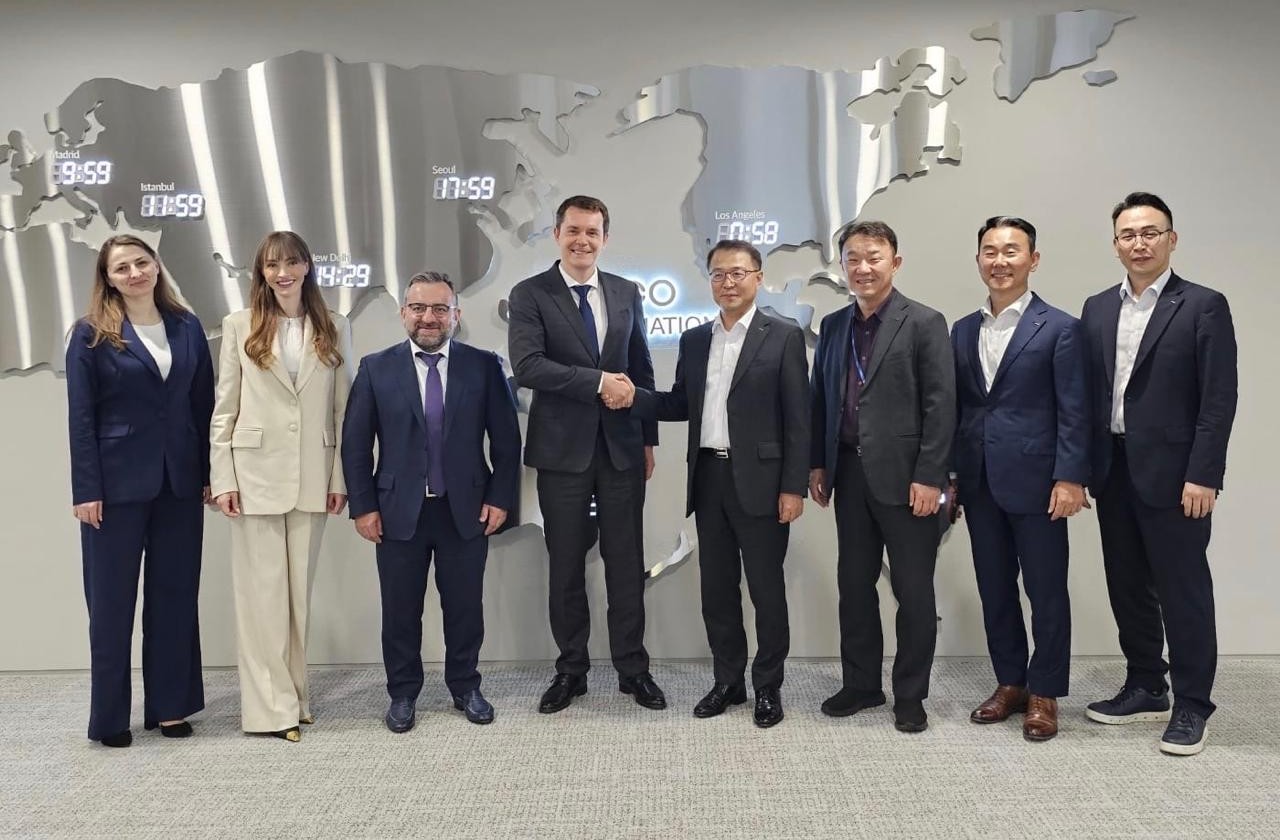
    During the conference, the BGV team held several meetings with Korean businesses. Discussions took place with POSCO International Corporation, interested in diversifying raw material supplies for high-tech industries, and BASE HD Co., an investment company active in energy, infrastructure, and industrial investments.

    “South Korea possesses unique technologies and engineering expertise,” emphasised Sergii Voitsekhovskyi. “We see immense synergy in combining Ukraine’s potential with the Republic of Korea’s industrial and scientific leadership. This is one of the strongest innovative economies globally – the leading country in terms of public investment in science (4.8% of GDP) and a top five nation for international patents. Collaborating with Korean partners offers an opportunity not only to attract technology but also to jointly create added value within Ukraine and foster a new economy where critical minerals are a catalyst for industrial breakthrough, not just raw materials.”

  • Chinese Firm East Hope Group to Invest in Major Green Aluminium Project in Kazakhstan

    Chinese Firm East Hope Group to Invest in Major Green Aluminium Project in Kazakhstan

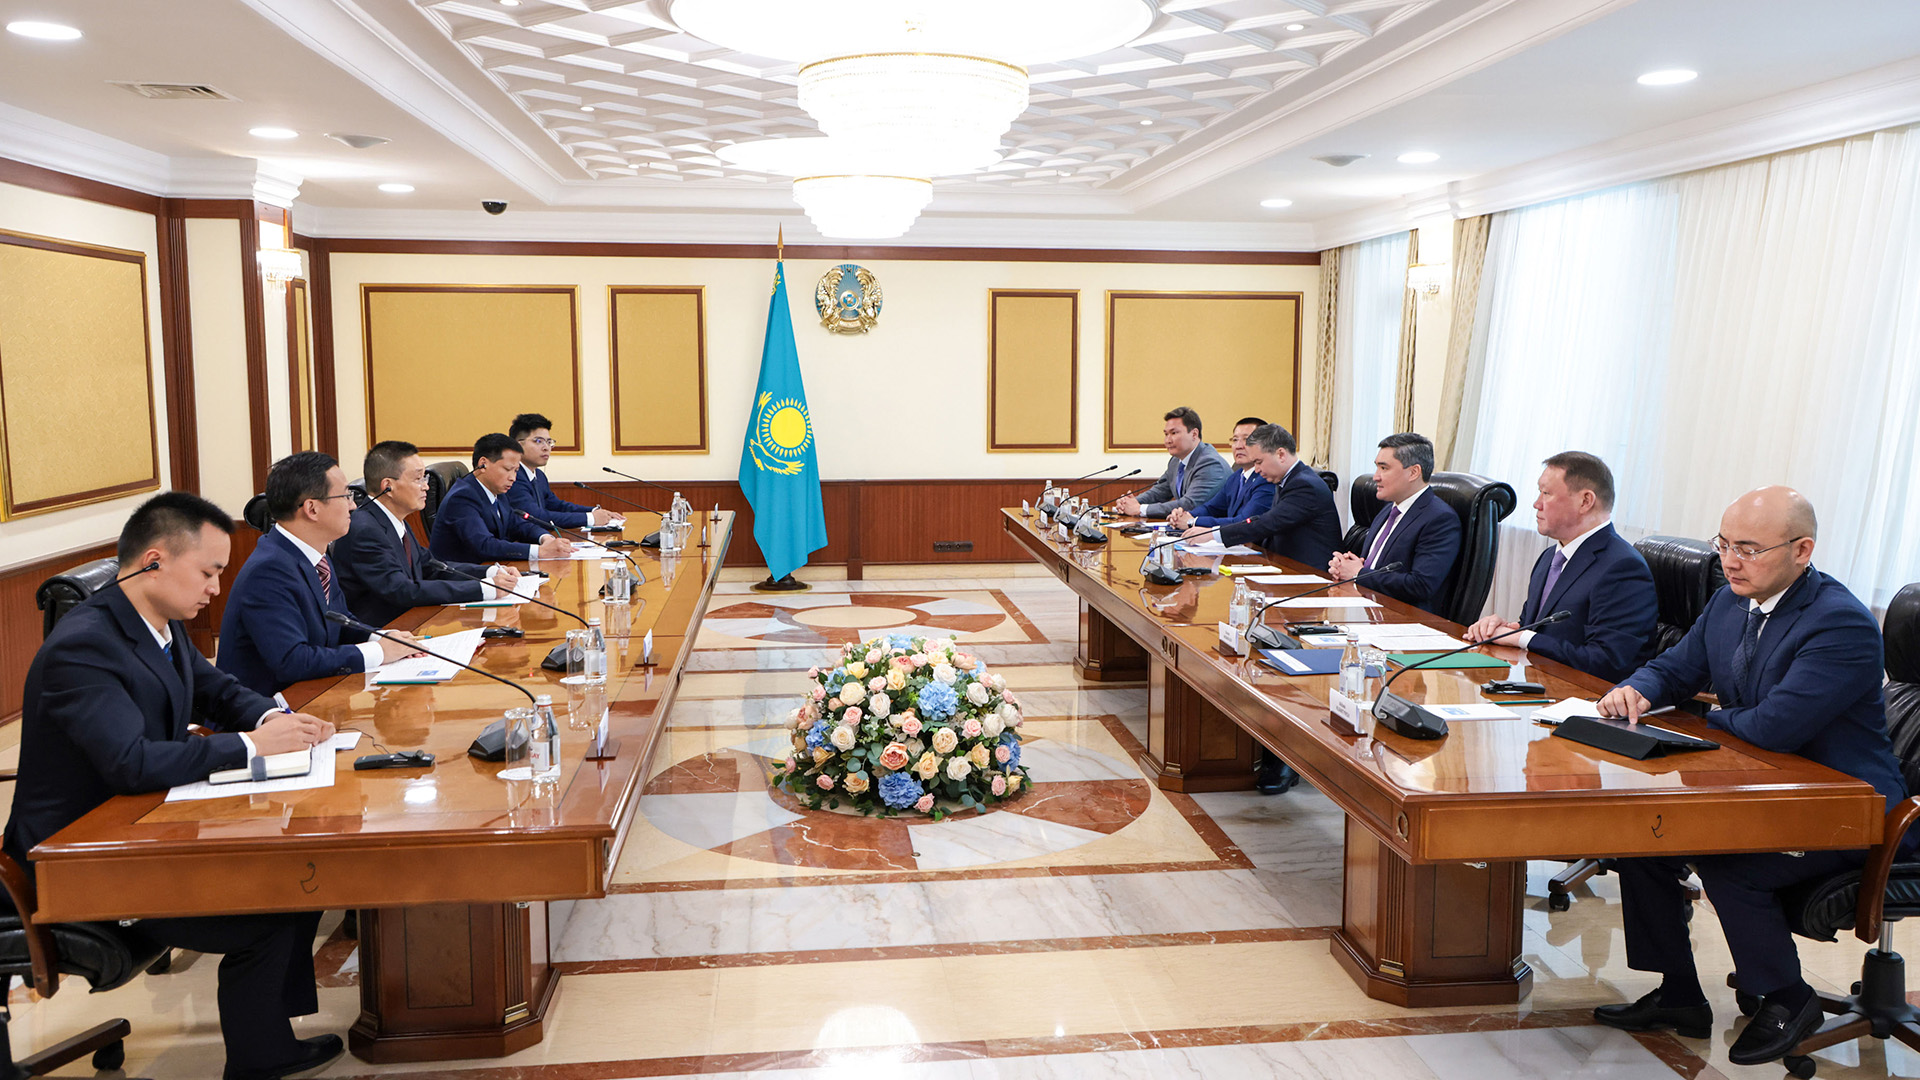
    Kazakhstan’s Prime Minister Olzhas Bektenov met with Liu Yongxing, Chairman of the Board for China’s East Hope Group, to discuss an ambitious project aimed at establishing a vertically integrated industrial park for “green” aluminium production in Kazakhstan. This initiative is designed around the principles of a circular economy, marking a significant step in the nation’s drive to diversify its economy.

    The proposed project encompasses the entire production cycle of “green” aluminium, from raw material extraction to the deep processing of high value-added materials. The initial phase includes constructing an ore dressing plant capable of processing 2 million tonnes of alumina annually, alongside an electrolysis plant to produce 1 million tonnes of aluminium per year. Crucially, the plan integrates renewable energy sources for electricity generation. East Hope Group estimates the project will create over 10,000 permanent jobs.

    “President Kassym-Jomart Tokayev has set the task of building a more diversified and future-oriented economy,” stated Prime Minister Bektenov. “We are gradually reducing our dependence on the raw materials sector and developing high value-added production. The creation of a vertically integrated aluminium production in Kazakhstan is a unique project that will ensure the comprehensive development of this sector within our domestic industry. The Government of Kazakhstan is ready for long-term cooperation.”

    Liu Yongxing highlighted Kazakhstan’s strategic importance as a logistical hub in Eurasia, noting its unique geographical advantages and development potential within the context of the “Belt and Road” initiative. He emphasised that Kazakhstan’s rich mineral resources and ongoing industrial modernisation strategy align perfectly with East Hope Group’s global priorities in “green” aluminium, modern agriculture, and renewable energy.

    Following the meeting, relevant ministries were instructed to provide the necessary support for the project’s implementation. East Hope Group has committed to certain obligations, including the training of local personnel and a phased increase in the proportion of Kazakhstani workers.

    East Hope Group is a global leader in the aluminium industry and is also active in polysilicon, “green” energy, agribusiness, and high-tech sectors.

  • Kazakhstan Expands Uranium Exports to Bulgaria’s Nuclear Industry

    Kazakhstan Expands Uranium Exports to Bulgaria’s Nuclear Industry

    Kazakhstan is set to supply uranium to Bulgaria’s nuclear power stations, according to Nurlan Zhakupov, the head of the Samruk-Kazyna Fund, who spoke to journalists at the Akorda presidential residence.

    Bulgaria operates a nuclear power plant with two 1,2 MW units, presenting a significant opportunity for cooperation in uranium supplies, Zhakupov explained. However, details regarding the volume of supplies remain confidential.

    Zhakupov also revealed that Kazakhstan Atomic Energy Stations (KAES), currently a subsidiary of Samruk-Kazyna, will transition to the newly established Agency for Atomic Energy. KAES will focus on the construction of nuclear power plants within Kazakhstan.

    Earlier reports indicated that Kazatomprom would supply uranium concentrate to the Czech Republic. This deal aligns with Kazatomprom’s global strategy to diversify its sales channels.

    Last year, Kazatomprom produced over 23,000 tonnes of uranium. Since 2022, Kazakhstan has been supplying uranium fuel to China’s nuclear power plants and, in December, completed a uranium shipment to Canada via the Trans-Caspian International Transport Route.

    In February of this year, Kazakhstan agreed to collaborate in the uranium sector with Jordan and to supply uranium to Switzerland.

  • Rio Tinto Shifts Oyu Tolgoi Mine Plan Due to License Delays

    Rio Tinto Shifts Oyu Tolgoi Mine Plan Due to License Delays

    Rio Tinto has announced adjustments to its underground development plan at the Oyu Tolgoi copper-gold mine in Mongolia. While the company remains committed to its target of 500,000 tonnes of copper production per year from 2028 to 2036, development in the Entrée Resources joint venture (JV) area has been paused due to delays in license transfers to the mine’s operating entity.

    This decision allows Rio Tinto to prioritise development in the more accessible Panel 2 South, ensuring the project stays on track.

    However, the delay in the Entrée JV area has caused concern for Entrée Resources, which expressed disappointment over the holdup, highlighting its potential impact on the project’s timeline, cost, and their financial position.

    Despite these challenges, Rio Tinto maintains its 2025 copper production guidance and underscores the importance of Oyu Tolgoi, one of the world’s largest known copper-gold resources, for both its growth strategy and Mongolia’s economic development.

  • Galantas Gold enters JV to relaunch Omagh mine in Northern Ireland

    Galantas Gold enters JV to relaunch Omagh mine in Northern Ireland

    Galantas Gold Corp. (TSX-V, LSE-A: GAL) has entered into a pivotal joint venture agreement with Ocean Partners UK to revive underground mining operations at the Omagh gold project in Northern Ireland.

    Under the binding agreement, Ocean Partners will convert approximately $14 million in existing loans into an 80% stake in Galantas subsidiaries Flintridge Resources and Omagh Minerals, which together control the Omagh asset. Galantas will retain a 20% stake, with an option to exchange it for a royalty interest at a later stage.

    Ocean Partners will also provide an initial $3 million to finance exploration activities, mine restart planning, and administrative costs over the first year. During this period, Galantas will be carried at no cost but may elect to contribute proportionally to future funding rounds, including a potential follow-up investment of $5 million. Ocean Partners will serve as the project operator, with a drilling campaign planned to target high-grade zones such as the Joshua and Kearney veins.

    According to Galantas CEO Mario Stifano, this deal is a “turning point” for the company, improving its financial position while enabling it to benefit from renewed gold production at Omagh. If Galantas’ interest drops below 10% or if it chooses to convert its holding, its stake will automatically convert to a net smelter return royalty of 1.5% to 3%, with Ocean Partners retaining certain buyback rights.

    The transaction, which requires shareholder approval, marks a fundamental shift in Galantas’ operations as it effectively transfers control of its main asset. The company also plans to advance its Gairloch gold-copper project in Scotland, with a maiden resource estimate and drilling scheduled.

    The Omagh project, located about 110 km west of Belfast, has a history of both open-pit and underground mining, though commercial production has not yet been achieved. Previous development was hindered by security and funding challenges, but the new joint venture aims to overcome these setbacks and capitalize on favorable gold market conditions.

  • Zijin’s Shadow: Villagers in Serbia and Tajikistan Bear Brunt of Chinese Mining Expansion

    Zijin’s Shadow: Villagers in Serbia and Tajikistan Bear Brunt of Chinese Mining Expansion

    In the hills of eastern Serbia and the valleys of western Tajikistan, villagers say they’re paying the price for China’s global mining ambitions. The Chinese-owned Zijin Mining Group, operating major copper and gold projects in both countries, stands accused of polluting the air, poisoning rivers, and displacing communities—while receiving strong political backing under the umbrella of Beijing’s Belt and Road Initiative (BRI).

    In Bor, Serbia, residents near Zijin’s Cukaru Peki copper mine complain of worsening air quality, arsenic, and fine particulate matter still lingering in the atmosphere despite the company’s reported $259 million investment in environmental improvements.

    “You used to see the smoke,” says Violeta, a Bor resident. “Now you don’t—but it still stinks.”

    In Krivelj, just outside Bor, Milos Bozic says the dust has made farming impossible. Professor Snezana Serbula of the Bor Technical Faculty confirms that PM particles and arsenic persist in the air. Meanwhile, residents like Dragoslav Stanculovic in nearby Ostrelj refuse to sell their properties. “What am I supposed to do—sell my dignity?” he asks.

    Despite environmental alarms, the Serbian government has doubled down on its support for Zijin, with Chinese companies now Serbia’s top exporters, surpassing $1 billion in trade by 2024.

    In Tajikistan, the story echoes Serbia’s. In Khumgaron and Shing, villagers say Zijin’s Zarafshon gold mine, where the company owns a 70% stake, has brought choking air and poisoned water. “Thick smoke covers the village in the morning,” says Abutolib Mukhtorov.

    Local residents in both countries report broken promises of relocation, inadequate compensation, and police intimidation of those who speak out. In Tajikistan, women who protested in Panjakent were detained. Firuza Kahorova recalls collapsing during the protest and being mocked by authorities: “They said, ‘Don’t give her water—give her dirt.’”

    Zijin claims 98% of Serbian land was acquired voluntarily and insists its projects meet environmental laws, branding Cukaru Peki as Serbia’s first “green mine.” In Tajikistan, Zijin has been fined, but continues operating with 20-year plans and strong support from the government, which highlights tax revenues and economic benefits.

    But for many residents, those benefits are illusory. “Peaches don’t grow. Cucumber flowers fall off. The river’s poisoned,” says Asadulo Rahmonov in Tajikistan. “It’s not progress. It’s survival.”

  • EU Weathers ‘Severe Market Disruption’ as China’s Antimony Controls Spark 170% Price Surge, Commission Finds

    EU Weathers ‘Severe Market Disruption’ as China’s Antimony Controls Spark 170% Price Surge, Commission Finds

    The European Union is well-positioned to weather, and potentially even benefit from, China’s new export controls on the critical raw material antimony, despite the measures causing a massive shock to global markets. A new policy brief from the European Commission’s Joint Research Centre (JRC) reveals that the EU’s strategic diversification of its supply chain has largely insulated it from the direct impact of the controls, which sent prices soaring by more than 170%.

    The report, “China’s Antimony Export Controls: Risks and Opportunities for the EU,” analyzes the fallout from China’s decision, effective September 15, 2024, to require dual-use export licenses for antimony and its products. The material is vital for defense applications—including armour-piercing rounds and night-vision equipment—as well as flame retardants, electronics, and batteries.

    The announcement immediately roiled the market, with the price of antimony metal surging from approximately 38,000 per tonne in September. The report describes this dramatic price jump as a reflection of “severe market disruptions, supply chain concerns, and potential shortages.”

    However, the JRC analysis concludes that the EU’s exposure is limited, thanks to years of proactive efforts to reduce its dependency on China.

    Key findings from the report include:

    • Diversified Supply Chains: While the EU is 100% reliant on imports for antimony ore, its primary supplier is Turkey (77%), not China. For antimony metal, the EU has dramatically shifted its sourcing, with Tajikistan now providing 52% of its imports. China’s share of the EU’s metal imports has fallen from 40% in 2020 to just 18% in 2023.

    • The US is More Exposed: The report highlights that the United States is far more vulnerable to the new regulations. China supplies 44% of US imports of antimony oxides—a refined product used in flame retardants and catalysts—compared to just 5% of EU imports.

    • An Opportunity for EU Exporters: The EU is a net exporter of high-value antimony oxides, producing 28,000 tonnes annually. The report suggests that if Chinese supply to the US and other markets is disrupted, EU producers could step in to fill the gap. “If European producers can secure stable antimony metal supplies, the EU may have an opportunity to expand exports,” the brief states.

    The report concludes that the EU’s strategic foresight in diversifying its critical mineral sources has turned a potential supply chain crisis into a manageable situation with a potential upside. While the dramatic price increase will affect all global users, the EU’s direct reliance on China is minimal, placing it in a resilient position compared to other major economies.

  • To Jadar or Not to Jadar: Serbia’s Lithium Debate Reignites

    To Jadar or Not to Jadar: Serbia’s Lithium Debate Reignites

    The long-dormant debate surrounding the controversial Jadar underground lithium mining project in Serbia has been thrust back into the spotlight following the European Union’s decision on 4 June 2025, to include it on its keenly anticipated (and for some, dreaded) list of 13 Strategic Projects located outside the Union’s borders. This move is set to trigger a fresh wave of intense discussions across Serbia and beyond.

    The Flemish newspaper De Standaard sought expert opinion on the matter, turning to Peter Tom Jones, Director of the KU Leuven Institute for Sustainable Metals and Minerals, whose insights, published in the 6th June printed edition by Pascal Sertyn, align fully with the narrative presented in the new documentary, “Europe’s Lithium Paradox.”

    In “Europe’s Lithium Paradox,” the filmmakers emphasize the urgent need for a robust democratization process in Serbia, a sentiment echoing the demands of the student movement. As a potential pathway out of Serbia’s entrenched lithium dilemma, the documentary also highlights the crucial role that independent third-party auditing organizations, such as the Initiative for Responsible Mining Assurance (IRMA), could play. The integration of such bodies, Jones argues, would be instrumental in rebuilding trust and ensuring adherence to the strictest Environmental, Social, and Governance (ESG) standards. The guiding principle, in the poetic words of Subcommandante Marcos, is “To make haste slowly.”

    Quotes from the De Standaard article (translated from Dutch):

    “Jones is convinced that the #Jadar lithium project is a unique opportunity to extract large volumes of this critical raw material with much smaller environmental disadvantages than those of many existing lithium mines. But Europe must realize that attempts to become more self-sufficient should not lead to uncritical support for autocratic regimes in the countries where these extraction projects are to take place, he says.”

    “According to Jones, the prospects for the lithium project in #Serbia are still not favorable, even though the European Commission considers it strategic to supply the EU with critical raw materials. He states that a far-reaching #democratization process is needed in Serbia before effective European support for the Jadar project can be greenlit. Collaboration with a third party, such as the Initiative for Responsible Mining Assurance, which imposes very strict ecological and social standards on #mining projects, could restore confidence, he says.”

    The inclusion of Jadar on the EU’s strategic list has been met with mixed reactions. While proponents, including Rio Tinto and some Serbian officials, claim it signals adherence to the highest environmental standards and promises significant job creation, opponents view it as a disregard for public opposition and a troubling sign of “colonialist relations” where Serbia is expected to sacrifice its environment for Europe’s industrial needs. The project has faced years of fierce resistance from environmental groups and local communities concerned about potential impacts on water sources, fertile land, and overall environmental degradation. The Serbian government had previously revoked the project’s licenses in 2022 following mass protests, though a local court later reinstated Rio Tinto’s permit.

    The Jadar project is now the sole lithium and boron project among the 13 newly designated strategic projects outside the EU, which also include sites in Canada, Greenland, Kazakhstan, Norway, Ukraine, Zambia, New Caledonia, Brazil, Madagascar, Malawi, South Africa, and the United Kingdom.

    Can Stakeholders Bridge the Divide in this War of Attrition?

    The question remains whether the diverse stakeholders involved in the Jadar project – including the Serbian government, local communities, environmental activists, Rio Tinto, and now the European Union – can break the current stalemate and move beyond the “lithium trenches” of this ongoing war of attrition. The calls for a genuine democratization process in Serbia, coupled with the implementation of robust, independently verified ESG standards through organizations like IRMA, suggest a potential path forward.

    For those eager to delve deeper into the complexities of the #Jadar project in #Serbia and other #lithium EU Strategic Projects in Portugal, France, Finland, and beyond, “Europe’s Lithium Paradox” and its companion documentary “Not In My Country: Serbia’s Lithium Dilemma” offer comprehensive insights into this highly contested mining and refining project.

  • Lumina Metals Advances Major Copper Project in Poland, Eyes Warsaw Stock Exchange Listing

    Lumina Metals Advances Major Copper Project in Poland, Eyes Warsaw Stock Exchange Listing

    Canadian mining company Lumina Metals is moving forward with plans to develop one of Europe’s largest copper mines at the Nowa Sol deposit in western Poland, after receiving C1 category classification and a five-year exclusivity for mining licence application. In an interview with PAP Biznes, CEO Jordan Pandoff confirmed that the company is now entering the permitting phase and considering a Warsaw Stock Exchange (WSE) listing to attract local investment.

    Described by Pandoff as “the largest copper discovery in Europe since the 1950s” and ranked globally among the top three in scale and grade, the Nowa Sol project forms part of Lumina’s broader Polish portfolio, which includes around 20 million tonnes of copper resources across three sites. To date, the company has invested PLN 500 million (EUR 117 million) in Poland, with expectations for far higher spending over the next five years.

    The mine, once permitted, is expected to take 3–4 years to construct. Although exact production figures have not yet been released, Lumina anticipates becoming one of Europe’s top copper producers, with output split roughly 70% copper and 30% silver, and potential for cobalt, platinum, and gold recovery pending further testing.

    Pandoff also expressed openness to collaborating with KGHM, Poland’s state copper giant, particularly by leveraging its smelting infrastructure rather than building a new facility. “KGHM, as a national champion, will benefit,” he said.

    While global demand for copper remains strong—driven by military, AI, energy, and EV sectors—Pandoff highlighted that Poland’s current mining tax regime discourages investment. He called for tax reform to align Poland with other successful mining jurisdictions. “At an 80% tax rate, no industry is viable,” he said, noting Canada, Australia, and parts of the U.S. typically cap total tax burdens between 30–50%.

    In a promising move for the sector, Poland’s government announced plans to reduce copper taxation starting in 2026, with draft legislation expected in June. According to EY, the reforms could boost Poland’s copper output to over 1 million tonnes annually, fueled by PLN 27 billion (EUR 6.3 billion) in greenfield investment from Lumina Metals and The Electrum Group.

    Meanwhile, Lumina is considering an IPO on the Warsaw Stock Exchange, potentially ahead of the mining licence approval. Pandoff views Warsaw as a natural hub for European resource developers. “If the WSE tailored its standards for mining, it could become a central resource exchange for the EU,” he noted.