The Tethyan Belt, one of the world’s most prospective mineral regions, is attracting renewed attention from exploration companies as activity accelerates across its underexplored eastern European segment.
Stretching across 34 countries from Western Europe to Southeast Asia and covering approximately 7.7% of the Earth’s land area, the belt hosts a significant share of global mineral wealth. According to MinEx Consulting, around 685 major deposits have been identified along the belt, representing 6.6% of known global deposits. These include an estimated 555 million ounces of gold, 293 million tonnes of copper, 16.6 million tonnes of nickel, 245 million tonnes of zinc-lead and 470000 tonnes of uranium.
Despite its scale, the Tethyan Belt remains relatively underexplored. Over the past two decades, it has attracted $9.8 billion in exploration spending—just 3.4% of global expenditure—yet delivered 143 new discoveries, accounting for 7% of global finds during that period.
The western end of the belt, particularly across Eastern Europe, has proven to be the most fertile area for discoveries. The region has seen 99 significant deposits identified over the past 40 years, including nine in the last decade alone. Countries across this segment collectively host substantial resources, including 216 million ounces of gold and 63.9 million tonnes of copper.
Serbia has emerged as a leading jurisdiction within this trend, supported by strong exploration success and active investment from major players such as Zijin Mining. The country has also attracted Australian-listed explorers seeking to replicate recent successes, including Strickland Metals, which has defined an 8.6 million ounce gold equivalent resource at its Rogozna project.
A wave of ASX-listed junior companies has entered the region in recent months. Regener8 Resources has acquired the Srebrenica North project in Bosnia and Herzegovina, targeting polymetallic mineralisation including silver, copper, zinc and antimony in a historically productive district that has seen little modern exploration since the 1970s.
Bindi Metals has secured a majority stake in the Ravni gold project in Serbia, where high-grade surface mineralisation and porphyry copper-gold potential have been identified. The company is advancing drilling plans following recent approvals and is targeting multi-million-ounce discoveries.
Meanwhile, MinRex Resources is progressing a merger with Electrum Discovery Corp to create a well-funded explorer focused on Serbian assets, including the Tlamino gold project and the Timok East copper-gold project. Planned drilling campaigns aim to expand resources and test new targets identified through geophysical surveys.
Middle Island Resources has also expanded its footprint in Serbia through the acquisition of Konstantin Resources, securing a large prospective land package. Early drilling and soil sampling programs have identified encouraging gold, silver and base metal anomalies, with further exploration planned for the 2026 field season.
Industry analysts note that declining discovery rates globally have increased the attractiveness of underexplored regions such as the Tethyan Belt. With favourable geology, existing mining infrastructure and growing investor interest, Eastern Europe is increasingly viewed as a key frontier for future mineral discoveries.
Lithium is increasingly being treated as a strategic resource in Europe, prompting efforts to develop domestic mining and processing capacity and reduce reliance on China’s dominant position in global supply chains.
China currently accounts for roughly two-thirds of global refined lithium production, a concentration that has raised geopolitical and industrial concerns within the European Union. With demand for lithium expected to grow significantly by 2030, driven by electric vehicles, energy storage and digital technologies, European policymakers are seeking to strengthen supply security.
Mining companies are advancing lithium projects across several European countries, including Portugal, Germany and Serbia. Portugal’s Barroso project has been designated as “strategic” under the EU’s Critical Raw Materials Act (CRMA), with production potentially starting later this decade. However, the project has faced opposition from local communities and environmental groups.
Serbia’s Jadar project, located outside the EU but of strategic interest to the bloc, is considered one of the most significant lithium developments in Europe. Industry estimates suggest it could supply a substantial share of regional demand, though progress has been delayed by political uncertainty and environmental concerns.
Germany is also exploring lithium extraction from geothermal brine resources, which could offer a lower-impact alternative to conventional mining methods. Recent discoveries in Saxony-Anhalt have been described by analysts as potentially significant, though further validation is required.
In parallel with mining development, European officials are considering broader policy measures, including the potential creation of strategic stockpiles of critical raw materials. The approach mirrors existing systems for oil and gas reserves.
The Critical Raw Materials Act, adopted in 2024, is central to the EU’s strategy. The legislation aims to accelerate permitting and investment in projects deemed strategic, including mining, processing and recycling. A significant proportion of the projects identified under the framework involve lithium.
Despite these efforts, industry experts note that Europe’s main challenge lies in building sufficient processing and refining capacity. Without this, domestically mined lithium may still need to be processed abroad, limiting the effectiveness of supply chain diversification.
Recycling is expected to play an increasingly important role in meeting future demand, particularly as battery waste volumes grow.
The push to secure lithium reflects broader concerns about supply chain resilience and industrial competitiveness. As global demand for battery materials continues to rise, Europe’s ability to develop a fully integrated lithium value chain will be a key factor in its energy transition and long-term economic strategy.
Australia’s Core Lithium has secured approximately $205 million in funding to fully finance the restart of its Finniss lithium project, with the company’s board approving a final investment decision to proceed.
The funding package comprises a $70 million convertible note from Glencore’s Australian unit and InfraVia, a $50 million senior secured debt facility from Nebari, and an equity raising of A$120 million (approximately $85.3 million) before costs. The placement will be priced at A$0.21 per share, representing a 4.5% discount to the company’s previous closing price.
Core Lithium stated that the financing will support construction activities and provide working capital during the ramp-up phase. The company is targeting first production of spodumene concentrate from the Finniss project in the September quarter.
Additional liquidity is expected from a binding agreement signed in February with Glencore International AG for the sale of the project’s remaining spodumene concentrate stockpile at a price of $2023 per tonne. Proceeds from this sale are intended to support the restart and early-stage operations.
The restart decision comes amid early indications of stabilisation in lithium markets following a prolonged period of price declines driven by weaker-than-expected electric vehicle demand and oversupply.
Other producers have also signalled potential production increases. Pilbara Minerals has announced plans to restart output at its Western Australia operation, while Liontown Resources is reviewing a possible expansion of its Kathleen Valley project in anticipation of improved market conditions.
Core Lithium’s decision reflects a broader trend among producers positioning for a potential recovery in lithium demand, particularly in battery and energy storage markets.
ASX-listed Vulcan Energy has secured a key regulatory milestone for its Lionheart project, receiving a lithium production licence in Germany’s Upper Rhine Valley Brine Field.
The licence, granted in the state of Rhineland-Palatinate, is the first of its kind issued in the region. Known as LiThermEx, it covers Vulcan’s Insheim geothermal production area, where renewable heat and electricity are already being generated.
The permit has been awarded for an initial six-year period, with the company planning to extend it in line with the project’s targeted 30-year operational life.
⚡ Lithium meets geothermal power Lionheart is not a typical mining project. It blends lithium extraction with geothermal energy production, creating a hybrid model where hot underground brines are used both to generate renewable energy and extract lithium.
The project is designed to produce around 24000 tonnes per year of lithium hydroxide monohydrate — a key battery material used in electric vehicles — while simultaneously supplying electricity and heat to local communities.
CEO Cris Moreno described the licence as a major step forward.
“Securing the first lithium production licence within the Lionheart project marks another important milestone,” he said, adding that the project supports Europe’s ambition to build a fully domestic lithium supply chain powered by renewable energy.
💶 De-risked and funded The licence further de-risks the project, which is already fully financed and under construction following a €2.2 billion funding package completed in December.
Vulcan expects additional production licences to be granted across the broader project area as development progresses.
🧭 Strategic timing With Europe racing to secure battery raw materials and reduce dependence on external suppliers, projects like Lionheart sit at the crossroads of energy transition and resource security.
Production is currently targeted to begin in 2028 — when lithium demand is expected to be even more electrified, quite literally.
London-listed ACG Metals is pursuing an ambitious expansion strategy, targeting up to 10 copper mine acquisitions as it seeks to rapidly scale production and position itself as a Western supplier of the strategic metal.
The company confirmed it is in active discussions over several assets, many of which are located along the Tethyan Copper Belt — a vast mineral-rich corridor stretching from southeastern Europe through Türkiye and into South Asia.
ACG is focusing on producing or near-production assets, allowing it to accelerate output rather than wait years for greenfield development. The strategy reflects a broader shift across the mining sector toward faster, acquisition-led growth.
🚀 From gold to copper growth engine ACG completed its first major deal in 2024 with the $300 million acquisition of the Gediktepe gold and silver mine in western Türkiye. The company plans to begin copper production at the site this year and is using it as a launchpad for broader expansion.
Its long-term ambition is bold: scale annual copper output to 300000 tonnes through a series of global acquisitions.
Founder and CEO Artem Volynets said market volatility could actually support dealmaking.
“Volatility always presents opportunities,” he noted, adding that while higher spot prices can complicate negotiations, they also create windows for strategic acquisitions.
📈 Copper’s magnetic pull Rising demand for copper — driven by electrification, renewable energy, and the explosive growth of AI data centres — is reshaping the mining landscape and fuelling consolidation.
Recent industry developments highlight the trend:
Ongoing discussions around mega-mergers between major mining players
Intensifying competition for high-quality copper assets globally
Copper prices have already climbed above 13000 per tonne, with long-term expectations pointing toward further increases despite short-term fluctuations.
Volynets described the outlook as a “stepwise climb,” with prices likely moving in waves toward the 13000–15000 range over time.
🌍 Geopolitics meets geology ACG is positioning itself as a Western-aligned supplier, with copper from its Turkish operations expected to feed European smelters.
For now, the company is prioritising assets close to its operational base in Türkiye and Eastern Europe — regions offering relatively lower costs and less competition compared to more saturated markets.
Africa and Latin America remain on the radar for future expansion, though Volynets acknowledged that Africa in particular is becoming a geopolitical battleground for control over critical minerals.
⚙️ Cost discipline as survival tool Despite bullish long-term fundamentals, ACG is keeping a sharp focus on cost control — the quiet survival skill of mining.
“Regardless of what prices are doing, miners should focus on cost of production,” Volynets said, noting that ACG’s operations currently sit in the lowest quartile of the global cost curve for gold.
While copper is the main growth driver, the company continues to produce gold, silver and zinc. Gold, in particular, may remain supported by geopolitical uncertainty, acting as a financial anchor while copper builds momentum.
Engineering and project delivery firm Ausenco has been awarded a contract to lead the feasibility study for the Ikkari gold project in northern Finland, owned by Rupert Exploration Finland Oy.
The project is located about 45 km from Sodankylä in the Lapland region and represents a significant grassroots gold discovery made in 2020. Following the completion of a Pre-Feasibility Study in early 2025, the project is now advancing toward development as a staged 3.5 million tonne per year mining operation with a planned mine life of around 20 years.
The development strategy предусматривает запуск открытой добычи в течение первых десяти лет, после чего проект перейдет на подземную разработку методом long-hole open stoping на оставшийся срок эксплуатации.
Ausenco will deliver a bankable feasibility study from its Perth office, integrating specialists from its teams in Australia and Canada. The company says the collaborative structure will combine global technical expertise with experience designing and delivering gold mining projects in remote and challenging environments.
Rupert Resources CEO Graham Crew said the appointment marks an important step in advancing the project toward development.
“The appointment of Ausenco represents an important milestone in advancing the project towards development,” Crew said. “Their proven ability to integrate teams from Australia and Canada in close collaboration with our project team and local partners ensures the delivery of a world-class study aligned with our strategic objectives.”
The feasibility study will cover value engineering, project implementation planning and detailed design of the processing plant and supporting mine infrastructure.
The study will be prepared to AACE Class 3 standards, providing capital and operating cost estimates with an accuracy of approximately ±15%. Ausenco will also act as the Qualified Person responsible for the NI 43-101 technical report.
The company plans to incorporate energy-efficient technologies and design features aimed at reducing the project’s carbon footprint, supporting Rupert Resources’ broader carbon-neutral targets.
Reuben Joseph, President for APAC and Africa at Ausenco, said the company looks forward to applying its experience in gold recovery technologies and energy-efficient project design.
“We are excited to partner with Rupert Resources on their Ikkari project,” Joseph said. “By leveraging our global gold study and project delivery experience, we are well positioned to deliver a robust study that supports Rupert’s operational, environmental and local community goals.”
Ausenco also emphasised the importance of working with local communities and regional organisations as the feasibility study progresses. The company said it will develop a project delivery framework that incorporates local expertise and aligns with regional standards, aiming to create long-term benefits for the surrounding region.
Ukraine’s Verkhovna Rada Committee on Economic Development has established a working group to address key operational challenges facing mining companies, with the situation at the Poltava Mining and Processing Plant — part of the Ferrexpo group — becoming the first issue under review.
According to Member of Parliament Oleksiy Movchan, the group held its initial meeting online with participation from representatives of the Ministry of Economy, the National Bank of Ukraine, the Ministry of Justice, the State Tax Service, industry associations, and management of the Poltava and Yeristovo mining and processing plants.
Several major issues affecting the Poltava operation were discussed, including electricity shortages and high power costs, blocked VAT refunds, and outstanding foreign currency payments owed by the parent company.
One of the most pressing challenges is the non-refund of value-added tax due to sanctions imposed on the company’s ultimate beneficiary, businessman Kostyantyn Zhevago.
Dmytro Mospan, manager of legal support for financial activities at Poltava Mining and Processing Plant, said more than UAH 3 billion in VAT refunds remains blocked for the company.
According to Mospan, the lack of access to these funds has forced the company to reduce the working week, cut social programmes, lower maintenance spending and scale back mining operations.
The State Tax Service said the situation is governed strictly by the Tax Code of Ukraine. Under Article 200.4, VAT refunds cannot be issued to taxpayers whose ownership structure includes individuals under sanctions.
Even in cases where courts have ruled in favour of the company, payments remain blocked. Funds are currently held by the State Treasury pending enforcement of court decisions but cannot be transferred due to provisions under Article 200.12 of the tax code.
One court ruling alone has frozen approximately UAH 230 million related to the plant.
The working group plans to further examine the company’s ownership structure at future meetings following additional reports from tax authorities.
Energy supply is another major challenge for the enterprise. Company representatives said limited availability of electricity and high power prices are making operations increasingly unprofitable. However, officials noted that electricity costs are a broader issue affecting Ukraine’s entire mining and metallurgical sector.
The matter is expected to be discussed further with the Ministry of Energy during upcoming sessions of the working group.
Movchan also said Ferrexpo AG owes the Poltava operation more than $500 million in unpaid foreign currency proceeds.
“This debt has been confirmed by international arbitration decisions and the figures have been verified by representatives of the National Bank,” he said.
The issue will also be examined in subsequent meetings.
Earlier this month, Ferrexpo announced it had restarted pellet production at the Poltava Mining and Processing Plant after suspending operations in January 2026. The restart was made possible by improvements in electricity supply and lower energy costs.
According to GMK Center, Ukraine’s iron ore exports fell by 8% in 2025 compared with the previous year, totaling 30.99 million tonnes. In January–February 2026 exports declined even further, dropping 40.9% year-on-year to 3.31 million tonnes, the lowest level recorded since 2023.
The United States, Japan and the European Union are preparing to announce plans for a new trade framework aimed at strengthening supply chains for critical minerals and reducing dependence on China, according to people familiar with the discussions.
The initiative is expected to lay the groundwork for a broader plurilateral trade agreement covering key minerals used in electric vehicles, clean energy technologies and advanced manufacturing. Negotiations are being led by the Office of the US Trade Representative (USTR) in coordination with officials in Brussels and Tokyo.
Officials involved in the talks say the framework may include coordinated trade policies such as price floors, tariffs and other market mechanisms designed to counter price distortions linked to Chinese supply. A price floor would establish a minimum market price for selected minerals, encouraging investment in mining and processing projects while preventing cheaper imports from undercutting producers participating in the agreement.
The Defense Advanced Research Projects Agency (DARPA) is reportedly assisting US trade officials in developing pricing models for the mechanism.
Global efforts to diversify critical mineral supply chains intensified after China introduced export controls on several rare earth elements and strategic minerals last year. The restrictions were widely seen as a response to sweeping tariffs imposed by the United States on imported goods.
Although supply pressures have eased since their peak last year, manufacturers in Europe, the United States and Japan continue to report shortages and delays in receiving critical mineral shipments from Chinese suppliers.
USTR is expected to begin formal negotiations with the European Union and Japan in April, shortly after the close of a public consultation period for industry stakeholders on March 19.
The announcement may coincide with Japanese Prime Minister Sanae Takaichi’s visit to the White House scheduled for March 19. European officials are also coordinating closely with Washington and Tokyo on the initiative, although the timing of Brussels’ announcement has not yet been finalized.
The concept is also expected to feature prominently at the upcoming Group of Seven summit.
Earlier this year, the United States signed a similar action plan with Mexico aimed at coordinating policies on critical mineral supply chains. The agreement includes provisions to examine border-adjusted price floors for mineral imports and to explore joint trade policies supporting secure supply.
Officials say the proposed framework between the US, EU and Japan will likely mirror many elements of the US–Mexico agreement. Potential areas of cooperation include investment screening, research and development in mineral processing technologies, coordinated stockpiling strategies and support for downstream supply chains.
While the exact list of minerals covered has not yet been finalized, officials are considering starting with a limited group of strategic materials before expanding the agreement to include a broader range of critical minerals.
The initiative reflects growing concern among Western economies about supply concentration in global mineral markets. China currently dominates the processing and refining of many critical materials, including rare earth elements, graphite and several battery metals.
Recent drilling results from the Korsnäs rare earth project in Finland are drawing attention to Europe’s geological potential in critical minerals, but they also highlight a deeper challenge for the continent: the lack of domestic processing capacity.
Exploration company European Resources reported its strongest rare earth intercept to date at the project, including a 31.5-metre interval averaging 4,902 parts per million total rare earth oxides (TREO). The mineralisation also contains a relatively high proportion of neodymium and praseodymium (NdPr), accounting for roughly 28–30% of the rare earth mix.
While encouraging, the results represent only an early stage of resource development. The next phase will require additional drilling and modelling to confirm the continuity and scale of the deposit.
NdPr is particularly important because it forms the foundation of permanent magnets used in electric vehicles, wind turbines, defence systems and other advanced technologies. These magnet rare earth elements are considered among the most strategically important minerals for Europe’s industrial and energy transition.
However, experts note that discovering deposits alone does not guarantee supply security. In the rare earth sector, the most complex and capital-intensive stage of development typically occurs after mining, during chemical processing, separation and waste management.
The Korsnäs project benefits from its location in Finland, a country with strong mining institutions, established infrastructure and relatively stable regulatory systems. This reduces certain development risks compared with projects in more uncertain jurisdictions.
Early mineralogical studies suggest the deposit contains monazite and apatite minerals, which can support certain processing routes. However, monazite often contains trace amounts of thorium or uranium, which can introduce stricter regulatory requirements related to residue handling and environmental protection.
Industry analysts say processing plants typically account for the largest share of capital expenditure in rare earth projects, often exceeding the cost of the mining operation itself. Complex processing flowsheets and environmental permitting requirements can significantly affect project economics and timelines.
European Resources has already begun metallurgical testing and downstream processing studies with the Australian Nuclear Science and Technology Organisation (ANSTO) to evaluate potential separation technologies and processing pathways.
Another notable feature of the Korsnäs results is the relatively high proportion of NdPr within the deposit. While TREO measures total rare earth content, economic value is usually concentrated in magnet elements such as neodymium and praseodymium, with smaller contributions from dysprosium and terbium. Deposits dominated by cerium and lanthanum, which are more abundant but less valuable, often face weaker economics.
The development of projects such as Korsnäs also intersects with broader European industrial policy. Under the EU’s Critical Raw Materials Act, the bloc aims by 2030 to extract at least 10% of its annual demand for strategic minerals domestically, process 40% within the EU and source 25% from recycling.
Achieving those targets will require major investment not only in mining but also in separation facilities, refining plants and downstream manufacturing. At present, China dominates the global rare earth processing sector, giving it significant influence over supply chains.
Analysts say that even if Europe develops new mines, the continent will remain vulnerable to supply disruptions unless it builds domestic separation and refining capacity.
The Korsnäs discovery therefore represents more than a geological milestone. It highlights Europe’s growing recognition that securing critical mineral supply will depend not only on discovering deposits, but also on developing the industrial infrastructure needed to process them.
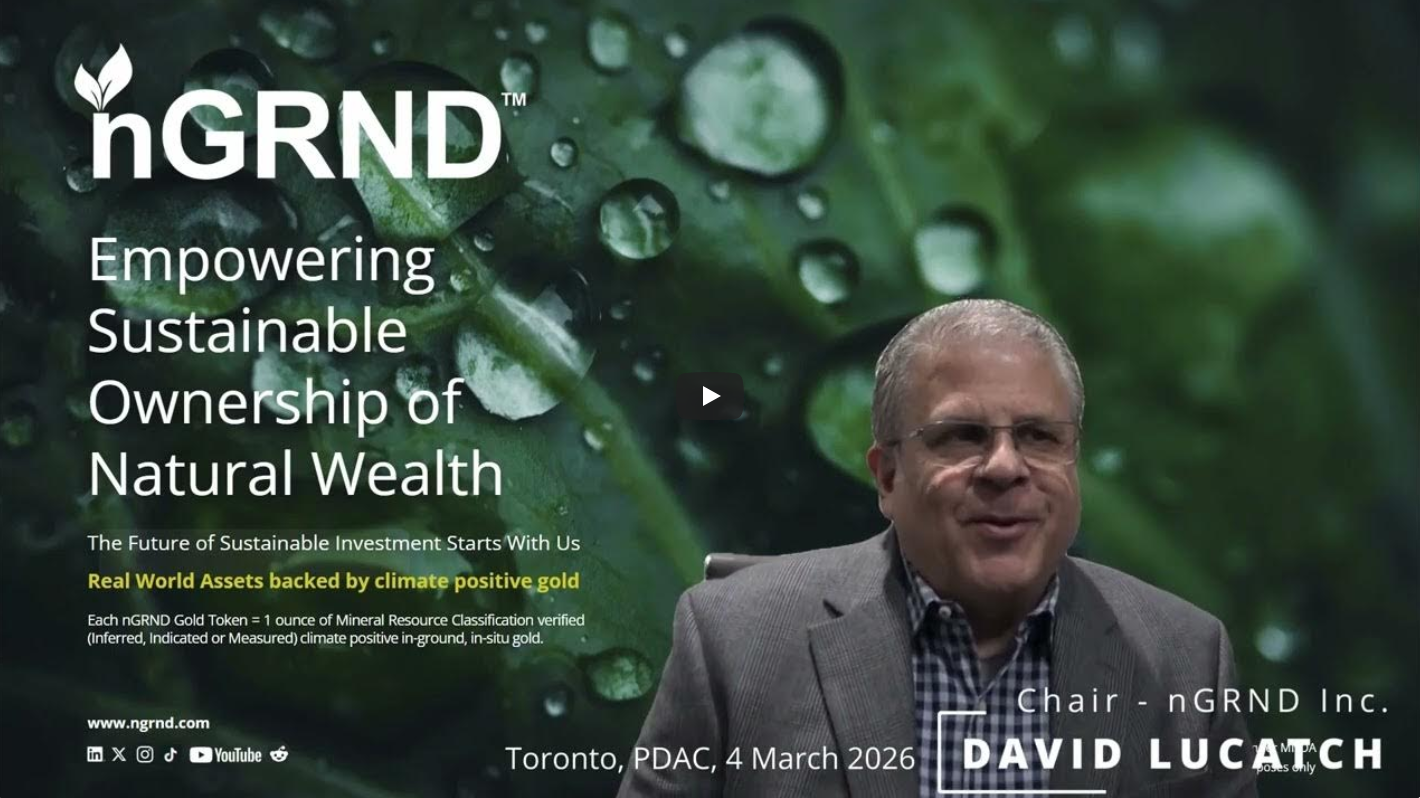
MINEX Forum Spotlights nGRND’s Vision for Sustainable Mining Finance at PDAC 2026
As a PDAC media partner for Europe and Central Asia, MINEX Forum continued to highlight innovations that can attract investment and accelerate the adoption of best-in-class technologies for sustainable mining. In its recent interview with David Lucatch, Chair of nGRND Inc., MINEX Forum explored a business model that challenges one of mining’s oldest assumptions: that value can only be unlocked by extracting metal from the ground.
nGRND, short for “in-Ground,” is advancing a novel concept built around the securitisation and tokenisation of verified in-ground gold reserves. The company’s vision is bold and deliberately provocative: to become “the world’s biggest resource company that doesn’t mine.”
A new way to unlock mineral value
In the interview, David Lucatch explained that nGRND is a land management and sustainability company working with gold discovery and exploration firms to monetise verified in-ground gold resources without physically mining them.
The company uses recognised technical documentation, such as NI 43-101 reports and other verified geological reports, to confirm the existence of gold resources. It then purchases those verified in-ground ounces from site owners and transforms them into a digital asset proposition for investors.
What makes the model distinctive is that it does not stop at the mineral resource itself. nGRND also seeks to integrate carbon, ESG and avoided mining programmes, creating an additional sustainability layer around the asset. In effect, the company aims to combine the enduring value of gold with the measurable benefits of reduced environmental disturbance, carbon impact mitigation and biodiversity protection.
This approach positions nGRND at the intersection of mining, environmental finance and blockchain-enabled asset structuring.
“We don’t just digitise gold — we redefine it”
nGRND describes itself as a company that is redefining how the world perceives, values and provides democratised access to natural wealth. Its proposition is centred on tokenising verified climate-positive in-ground gold reserves while integrating benefits from avoided mining and environmental restoration frameworks.
The company’s message is clear: gold can be reframed not merely as a mined commodity, but as a climate-positive, real-world asset. That framing is captured in its positioning:
Responsible innovation – Real-world value – Climate positive verified impact
This is a significant departure from the traditional mining investment thesis. Rather than focus solely on extraction, production growth and commodity cycles, nGRND is attempting to create value from preservation, optionality and sustainability.
Why gold, and why now?
David Lucatch made the case that gold is the ideal starting point for this model. He noted that roughly 93% of all gold is ultimately used as stored value—whether in jewellery, coins, bullion or central bank holdings—while only a small proportion is consumed for industrial or trade purposes. In his view, this makes gold uniquely suited to a system where the asset’s value can be recognised and monetised without immediate extraction.
For nGRND, the long-term opportunity is substantial. Lucatch said the company’s ambition is to monetise nearly 250 million ounces over the next decade.
That ambition reflects broader shifts in the global mining and investment landscape. Juniors and mid-tier explorers often hold significant resource inventories but struggle to convert those ounces into market value. Many trade at a fraction of the implied value of their resources, and raising capital to advance projects often leads to repeated equity dilution. nGRND’s model is designed to address precisely that problem.
Non-dilutive capital for explorers and developers
One of the strongest themes in the interview was the potential for nGRND to provide non-dilutive capital to exploration and mining companies.
Mr. Lucatch pointed out that many public companies may hold large resource bases while trading at only a few dollars per ounce in the ground. The more they raise through conventional financing, the more dilution they create for existing shareholders. By contrast, nGRND’s programme is intended to generate revenue by purchasing in-ground ounces and layering in future carbon and ESG value, thereby placing revenue on a company’s books without altering its capital structure.
That could be especially relevant for:
discovery and exploration companies
brownfield or retired assets
stranded deposits
projects that are currently uneconomic or inaccessible
properties constrained by environmental, geographic or regulatory factors
David Lucatch was clear that nGRND is not trying to interfere with active producers whose business depends on mining and selling gold. Rather, the company sees opportunity in assets where extraction may not make sense now—or for decades.
This opens an intriguing pathway for projects located under sensitive areas, near protected land, or in settings where mining would face high environmental or logistical barriers. In such cases, keeping the gold in the ground may itself become part of the value proposition.
The importance of jurisdictional stability
The success of such a model depends not only on geology, but also on geopolitics. Since nGRND’s premise is to keep resources in the ground over long time horizons—Lucatch referred to agreements of around 30 years with renewal features—the company must be confident that control over those resources can be maintained.
For that reason, nGRND is prioritising geopolitically stable jurisdictions. He noted that even previously attractive mining regions can become more uncertain over time, citing recent examples of nationalisation risk. For a company whose asset thesis depends on long-term preservation rather than near-term extraction, legal certainty and jurisdictional continuity are essential.
At present, nGRND is looking at opportunities involving Canadian, American, European, Australian, South American and South African companies, while remaining open to additional jurisdictions where the business model can be executed securely.
Global investor access through regulated token issuance
Another key part of the nGRND proposition is access to capital through digital markets. Lucatch said the company plans to launch its in-ground gold token to investors globally, excluding the United States and restricted jurisdictions. The investor base is expected to include both institutional and retail participants.
According to the interview, nGRND’s token issuance and generation partner is regulated in Dubai, and the structure is blockchain-based. The company believes this gives it a compliant route to market while offering broad international reach.
This matters because nGRND is not simply creating a mining finance instrument. It is attempting to build a bridge between real-world mineral assets, sustainability-linked value creation and digital finance infrastructure.
No direct competitor—yet
David Lucatch suggested that nGRND’s model is highly differentiated. While there are already businesses involved in tokenising physical gold, he argued that nGRND has not identified a direct competitor offering the same combination of:
verified in-ground gold monetisation
avoided mining and sustainability integration
compatibility with both private and publicly listed companies
non-dilutive financing potential
That combination could appeal to a market increasingly focused on ESG alignment, capital efficiency and alternative asset structures.
Relevance for Europe and Central Asia
For MINEX Forum audiences across Europe and Central Asia, the concept may be especially timely. The region includes a wide range of mining jurisdictions with large undeveloped or stranded mineral inventories, as well as governments and companies seeking new ways to attract investment while minimising environmental impact.
Lucatch indicated that Central Asia is still a new area for nGRND, but one the company is open to exploring. That leaves the door open for future engagement in a region where resource development, sustainability policy and foreign investment priorities increasingly intersect.
If the model proves scalable, it could offer a new option not only for companies seeking capital, but also for governments interested in balancing resource monetisation, environmental protection and long-term land stewardship.
A different future for mineral wealth
The significance of the MINEX Forum interview lies in the fact that nGRND is not merely proposing another financing instrument. It is proposing a different philosophy of resource ownership and value creation.
Instead of asking how quickly a gold deposit can be extracted, financed and sold, nGRND asks a different question: can the value of that resource be realised while leaving it in the ground?
That idea will undoubtedly attract scrutiny. Questions remain around market adoption, valuation frameworks, regulatory treatment and long-term execution. But the concept is difficult to ignore, particularly at a time when the mining sector is under pressure to decarbonise, reduce land disturbance and find more creative funding pathways.
For MINEX Forum, whose long-term objective is to promote investment and best-in-class technologies for sustainable mining, the conversation with David Lucatch reflects precisely the kind of innovation now reshaping the industry’s horizon.
nGRND’s ambition is striking, but its proposition is simple at its core: natural wealth does not always have to be extracted to be valuable.
If that idea gains traction, “the world’s biggest resource company that doesn’t mine” may become more than a slogan. It may become a new category in global mining finance.