Website: Europe.com

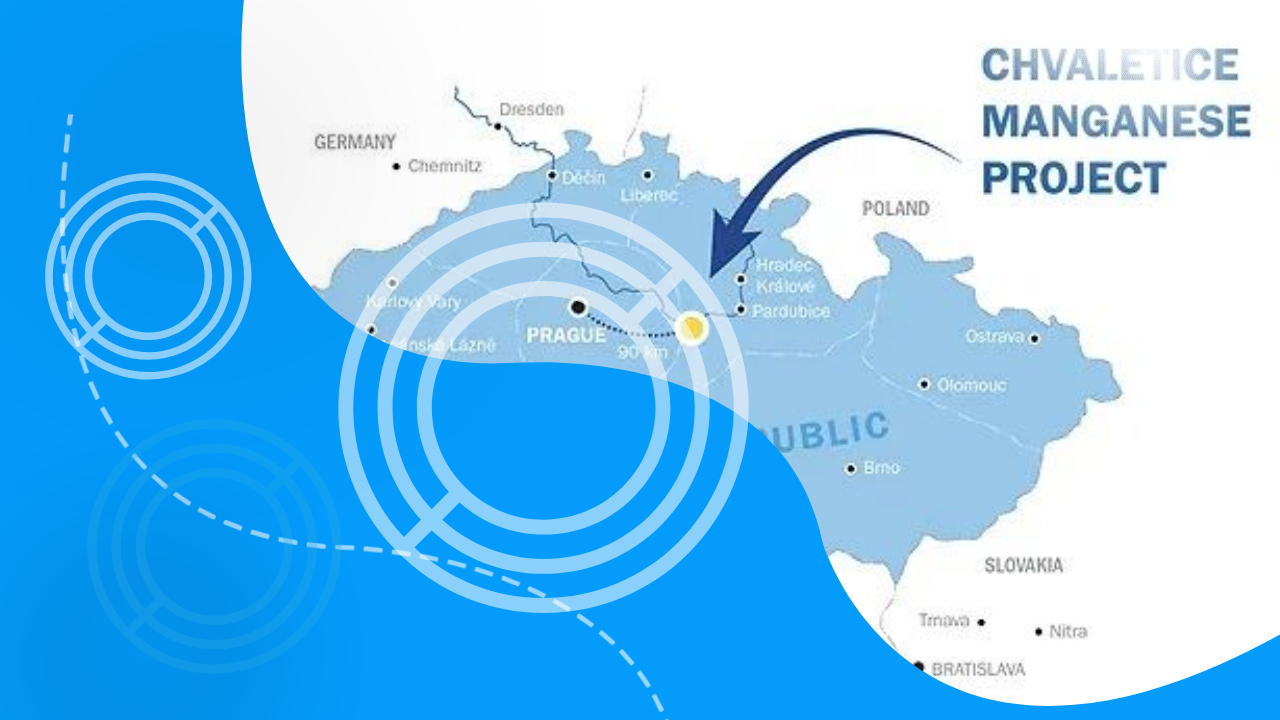
  • Euro Manganese has attained the endorsement of the Environmental and Social Impact Assessment (ESIA) for its Chvaletice Manganese Project.

    Euro Manganese has attained the endorsement of the Environmental and Social Impact Assessment (ESIA) for its Chvaletice Manganese Project.

    The Company has received a positive ESIA binding statement from the Czech Ministry of Environment, which approves the environmental and social conditions set out in the ESIA. This is the culmination of a four-year process, where 14 separate government authorities were required to provide a positive opinion on the Company’s ESIA, after which the ESIA was open to a public commentary period. No comments were received from the public, NGOs or regional municipalities during this period, demonstrating the excellent stakeholder engagement processes managed by the Company’s local Czech team.

    The approval of the ESIA is the key gating permit from which subsequent permits can follow, including the Land Planning Permit and the Construction Permit. Receipt of the ESIA also allows the Company to progress to the final determination of the Mining Lease for the Project.

    Euro Manganese is a battery materials company focused on becoming a leading producer of high-purity manganese for the electric vehicle industry. The Company is advancing development of the Chvaletice Manganese Project in the Czech Republic and pursuing an opportunity to produce battery-grade manganese products in Bécancour, Québec.The Chvaletice Project is a unique waste-to-value recycling and remediation opportunity involving reprocessing old tailings from a decommissioned mine. It is also the only sizable resource of manganese in the European Union, strategically positioning the Company to provide battery supply chains with critical raw materials to support the global shift to a circular, low-carbon economy.Euro Manganese is dual listed on the TSX.V and the ASX, and is also traded on the OTCQX.Authorized for release by the CEO of Euro Manganese Inc.Neither TSX Venture Exchange nor its Regulation Services Provider (as that term is defined in the policies of the TSX Venture Exchange) or the ASX accepts responsibility for the adequacy or accuracy of this release.

  • Ukrainian Iron Ore Industry Shifts Towards High-Quality Concentrate Production

    Ukrainian Iron Ore Industry Shifts Towards High-Quality Concentrate Production

    Amidst the global push for green steel production, Ukrainian mining and processing plants are urged to enhance the quality of iron ore concentrate, transitioning to higher iron content levels, reports UAprom. This call to action was underscored during the “Iron Ore Deposits of Ukraine: Current Problems and Development Prospects” international conference held at the Taras Shevchenko National University of Kyiv on March 21-22, where leading scientists and industry representatives convened.

    Yelena Belan, an expert on iron ore production at Metinvest Group, emphasized the importance of meeting market quality requirements to avoid losing opportunities for product sales and enterprise capacity.

    Ensuring consistent high-quality products with elevated iron content positions Ukrainian enterprises to lead the green modernization of Europe and integrate into the global green metallurgy system.

    Despite the use of low-grade ores with approximately 30% total iron content, Ukrainian iron ore industry relies on extensive processing methods such as crushing, grinding, magnetic separation, flotation, and dewatering to upgrade these ores. The resultant magnetite concentrate with 64-68% iron content undergoes fundamental qualitative changes, making it significantly different from the original ore, noted experts from the Institute of Geology at Taras Shevchenko National University of Kyiv.

    Concerns regarding the tax treatment of deep processing were also addressed, with experts asserting that magnetite concentrate represents a distinct product compared to the original ore. This sentiment was echoed by scientists from the Semenenko Institute of Geochemistry, Mineralogy, and Ore Formation of the National Academy of Sciences of Ukraine, emphasizing the need to reconsider rent taxation policies.

    Ukraine witnessed a substantial reduction in iron ore exports in 2023, down by 26% compared to 2022, with raw material exports plummeting by 60% compared to pre-war 2021 levels. Revenues from iron ore exports for Ukrainian companies also experienced a significant decline.

    Major iron ore producers in Ukraine include Ingulets GOK, Kryvyi Rih Iron Ore Plant, Poltava Mining, Northern GOK, Central GOK, Southern GOK, ArcelorMittal Kryvyi Rih, and Sukha Balka.

  • Ussuri Capital Plans $1 Billion Investment for Carbon-Neutral Steel Mill in Romania

    Ussuri Capital Plans $1 Billion Investment for Carbon-Neutral Steel Mill in Romania

    Ussuri Capital, a Turkish investment firm, has unveiled plans to invest up to 960 million euros ($1 billion) in constructing a carbon-neutral steel mill in Romania. Completing the feasibility study and business plan in March, the company is now engaged in due diligence on potential land plots for plant location and exploring the project’s capital structure, as stated in a recent press release.

    The project’s initial phase, valued at 160 million euros, will involve installing a push-pull pickling line, a cold rolling mill, and a hot-dip galvanising line, along with a colour coating line. This phase is slated for commissioning in 2027, utilizing hot rolled coils imported from non-EU countries as the initial feedstock.

    The subsequent phase, estimated between 715 to 800 million euros, will encompass constructing an electric arc furnace and a continuous casting module, expected to be completed by 2030.

    Upon operationalization, the Romanian plant aims to annually produce 400,000 tonnes of pickled coils, 250,000 tonnes of cold-rolled coils, and 250,000 tonnes of hot-dip galvanised coils.

    Revenue projections from downstream operations are anticipated to hit 324 million euros, with an EBITDA of 38 million euros within two years post the first phase’s commissioning, yielding an EBITDA margin of roughly 12%.

    Ussuri Capital, headquartered in Istanbul, focuses on green steel investments, commodities, metals, and mining.

  • ArcelorMittal Zenica to Close Coke Oven Battery Due to Maintenance Costs and Decreasing Demand

    ArcelorMittal Zenica to Close Coke Oven Battery Due to Maintenance Costs and Decreasing Demand

    ArcelorMittal Zenica, a steel plant based in Bosnia and Herzegovina and a subsidiary of global steelmaker ArcelorMittal, has announced its decision to shut down its coke oven battery. This move comes amidst escalating maintenance expenses for the unit and dwindling demand for its products, as stated in a press release on the company’s website.

    The coke plant in Zenica has been in operation for over 40 years, with operations suspended from 1992 to 2008. Despite significant modernization efforts over the past decade, the company has deemed further investments unjustifiable from an economic standpoint, citing an inability to meet stringent environmental standards.

    Nikhil Mehta, CEO of ArcelorMittal Zenica, expressed the company’s commitment to minimize the closure’s impact on the local economy, stating, “This is a difficult day for the company…We plan to try to transfer a significant number of employees from this plant to other units in Zenica.”

    While the coke oven battery closes, the company will maintain steel production by procuring coke from external suppliers.

    ArcelorMittal Zenica concluded 2023 with a loss of BZN 159 million ($88.2 million), influenced by reduced steel demand, a 20% year-on-year surge in electricity prices, and a decline in global steel prices, as reported by GMK Center.

    Zenica Steel, which employs 2.2 thousand people and produces approximately 700 thousand tons of steel annually, specializes in rebar, wire rod, mesh, and grating.

  • Germany Shuts Down Seven Coal-Fired Power Stations Over Easter

    Germany Shuts Down Seven Coal-Fired Power Stations Over Easter

    Over the Easter weekend, Germany closed seven coal-fired power stations, according to statements from power generators RWE and LEAG on Sunday. The government’s decision to reactivate five plants during the winter due to a gas supply shortfall, coupled with its efforts to decrease reliance on Russian gas, led to this action.

    Five of the shut-down plants were situated in the Rheinish mining district near Cologne, Western Germany, including sites like Grevenbroich-Neurath and Bergheim-Niederaussem. This move results in decommissioning approximately 2,100 megawatts (MW) of lignite capacity, as stated by operator RWE. Additionally, two plants in Jänschwalde, Brandenburg, near Berlin, were shut down after being brought back online recently.

    The decision to keep coal plants operational stemmed from Germany’s strategy to address climate change, which faced challenges following Russia’s invasion of Ukraine in February 2022. In response to the war and subsequent energy price spikes, Germany opted to extend the lifespan of some coal-fired plants and temporarily restart others. This strategy also involved delaying the closure of several nuclear power plants as a contingency measure.

    Despite concerns, Germany’s grid operator assured the public that the shutdown of coal plants wouldn’t impair power supply security following the end of the 2023/4 winter season. However, the decision to delay closures necessitates a review by the Economy Ministry to assess the increase in greenhouse gas emissions and propose offsetting measures by the end of June.

    The move to close coal-fired power plants was praised by Green Party lawmaker Kathrin Henneberger, who emphasized its significance in combating the climate crisis and achieving climate goals.

  • Austria’s RHI Magnesita to buy US-based alumina producer Resco

    Austria’s RHI Magnesita to buy US-based alumina producer Resco

    RHI Magnesita, a Vienna-based manufacturer of fireproof materials, intends to acquire Resco Group, a US-based company specializing in alumina and refractories, for an enterprise value of up to $430 million, as announced by both companies. This acquisition, according to RHI Magnesita, aligns with their strategy of localized production, enhancing their range of products for US customers while streamlining supply chains and improving responsiveness. The cash consideration for the acquisition is anticipated to be approximately $324 million, with a potential upper limit of about $342 million if the completion extends beyond 18 months post-signing. The funding for this acquisition will come from RHI Magnesita’s existing liquidity and a new committed facility of 200 million euros ($216 million). Resco reported unaudited revenues of $252 million in 2023 with a profit before tax of $20 million. Following the acquisition, synergies will be realized through the restructuring of the combined supply chain, a process expected to take about two years with one-time costs estimated at 60 million euros, including restructuring activities at non-US plants. The acquisition is contingent upon customary closing conditions, including approval from merger control authorities, and is projected to be finalized in the latter half of this year. Once completed, the combined entity will encompass 15 production sites spanning the United States, Canada, and Mexico. Resco Group, currently owned by Balmoral Funds, a California-based private equity firm managing approximately $1.5 billion in assets, issued a statement confirming these details.

  • Northvolt AB initiates €5 billion battery plant construction in Northern Germany

    Northvolt AB initiates €5 billion battery plant construction in Northern Germany

    Northvolt AB has embarked on the construction of a €5 billion ($5.4 billion) battery plant in northern Germany, marking a significant milestone in its endeavor to supply electric cars. This project marks the culmination of an intensive lobbying effort, facilitated by the newly relaxed European Union state aid rules.

    The construction of the plant, located near the town of Heide, is bolstered by just over €900 million in subsidies and guarantees from Germany. This support played a crucial role in preventing the project from being relocated to the United States. Chancellor Olaf Scholz emphasized that the factory will contribute to securing the country’s future as a manufacturing hub.

    “The production of quality cars beyond the combustion engine remains the cornerstone of our industrial sector,” stated Chancellor Scholz during an opening ceremony on Monday. “For this, we require battery cells made in Germany, made in Europe.”

    In a strategic move to enhance competitiveness against the US, the European Union relaxed its rules on state subsidies last year. This move aimed to attract investments by offering similar incentives to those in the US, where generous tax relief and aid for climate technologies are driving significant investments. Northvolt, Europe’s sole major home-grown EV battery manufacturer, counts Volkswagen AG and BMW AG among its clientele and is also advancing its presence with a site in Canada.

    Northvolt’s Heide plant, powered by wind energy, is expected to employ approximately 3,000 individuals and commence operations in 2026. With an annual capacity target of 60 gigawatt-hours, making it Germany’s largest, the plant is poised to supply batteries for approximately 1 million electric vehicles. Initial construction estimates for the Heide facility were projected at €4.5 billion.

  • Italy has offered Metinvest, owned by Rinat Akhmetov, the opportunity to rebuild a steel plant in Taranto.

    Italy has offered Metinvest, owned by Rinat Akhmetov, the opportunity to rebuild a steel plant in Taranto.

    The Metinvest mining and metallurgical group intends to build a plant in Piombino in the Italian region of Tuscany as one of the most technologically and environmentally advanced of its kind, which will become a pilot for our future investments of the company in Ukraine, Metinvest CEO Yuriy Ryzhenkov said in an interview with La Repubblica, one of Italy’s largest newspapers. According to him, the new plant in Piombino will produce “green steel.”

    The CEO said during a war the company devotes its greatest efforts to support the country on its path to victory. “For our Group, this means continuing to pay taxes, providing humanitarian aid and helping the Ukrainian army. Despite the loss of two steel mills, as well as the coking plant in Avdiivka, Metinvest remains the largest employer in Ukraine and the largest donor to the Ukrainian army. We have allocated significant funds to support the Ukrainian armed forces and provide humanitarian aid to Ukrainians,” the CEO said.

    Answering a question about the financial results for 2023, the company’s CEO said the net loss was $118 million, “but we have stabilised the business while cash flow is positive, which means we are back on the right track. And this is very important.”

    Regarding plans to build a plant in Piombino, Ryzhenkov said the group currently already owns two plants in Italy but intends to construct a third plant.

    “Metinvest committed to build a new green steel plant in Piombino as part of a programme agreement with the Italian Minister of Enterprises and Made in Italy. This is the result of the cooperation of many institutions, including regional and municipal ones. We hope to finalise the agreement within the next three to four months and to have a precise action plan,” the CEO said.

    “If we finalise the programme agreement by the middle of this year, we could start the plant’s construction towards the end of 2024. The construction itself will take two to three years. In an ideal scenario, we should start production in Piombino in 2027,” Ryzhenkov said.

    He said Italy imports about 6 million tonnes of steel products. And thanks to the production that the company plans to launch, this deficit can be significantly reduced. The plant will become a pilot project for future company investments in Ukraine when the country begins to recover.

    Ryzhenkov also explained plans to build a plant in Italy were made long before the invasion. Then the idea was to use semi-finished products from Azovstal for further processing in Italy. Now there is no Azovstal, but in Ukraine we have iron ore enterprises producing high-quality iron ore, which can be used to make DRI/HBI (direct reduced iron). So now the idea is to build a plant that will use iron ore from Ukraine to produce steel in Italy.

    Responding to a question about the concerns of Italian manufacturers about a possible shortage of scrap due to the future construction of the plant in Piombino, the company’s CEO said in Italy there is no shortage of raw materials, there is competition, like in other countries. Raw materials can also be delivered by sea. And he emphasized that the steel plant in Piombino will receive raw materials from Ukraine.

    “At the moment, we are identifying a location for the construction of the DRI plant, and we know that we are not the only ones, other Italian steelmakers are doing the same. Some are considering building DRI plants outside of Italy, where gas prices are lower. In any case, Metinvest will contribute to this process by supplying raw materials to DRI plants to be built in Italy, just as we will supply them to our DRI plant, which may be built in Ukraine or somewhere else, from which raw materials will be supplied to the Piombino plant,” the CEO said.

    Touching on the topic of some Italian manufacturers purchasing cheaper Russian slabs, he pointed out that the holding in Italy produces coils as finished products, buys about 1 million tonnes of semi-finished products for the production of coils, but not a single ton is supplied from Russia.

    “We buy slabs both in Italy, from Adi in Taranto, and from other European producers such as ThyssenKrupp, Galati or U.S. Steel in Košice. And on the wider market, also in China and Brazil. And it all remains profitable,” Ryzhenkov said.

    He called on Italian manufacturers not to buy metal from Russia, since “it’s like shooting yourself in the foot.”

    Answering a question about Metinvest’s alleged intention to acquire the assets of the former Ilva company, Ryzhenkov said Italian Minister Urso asked the company to pay attention to the plant in Taranto and consider the possibility of restoring it.

    “We have set up a dedicated task force to analyse the situation and scenarios. We are providing our support by supplying raw materials to Taranto. In addition, we are supplying technical specialists to help optimise the use of our raw materials and purchase semi-finished products from Taranto. With this in mind, we are currently focusing on Piombino. But we are continuing to analyse ways in which Metinvest can do more to help the plant in Taranto, even if there are no announcements about this for the time being,” Ryzhenkov said.

    According to him, if by the end of the year the Italian government puts the former Ilva sites up for auction, then Metinvest’s participation will primarily depend on the results of due diligence, after which it will consider the terms of the tender, its restrictions and the level of government support.

    “In general, there are many things to verify before a group like Metinvest can say whether it is interested in an investment of this scale. At the moment, I can only confirm that we are analysing the situation, we can make proposals, but it is up to the government, as it is the one that has to create the conditions for taking further steps. We also know that some other groups in the industry are looking at the former Ilva plant, so we will see what happens next,” the CEO said.

    Metinvest consists of mining and metallurgical enterprises located in Ukraine, Europe and the United States. Its main shareholders are the SCM group (71.24%) and Smart Holding (23.76%), which jointly manage it.

    Metinvest Holding LLC is the management company of the Metinvest group.
  • Ferrexpo Seeks Resumption of Exports Through Temporary Corridor Amid Reduced Capacity and Losses

    Ferrexpo Seeks Resumption of Exports Through Temporary Corridor Amid Reduced Capacity and Losses

    Ukrainian iron ore miner Ferrexpo aims to restart exports via the Black Sea amid risks posed by Russian attacks on ships leaving the port of Odesa. Since Moscow terminated a pact ensuring the safe transport of Ukrainian grain, Kyiv has established a provisional passage for vessels to enter and exit. However, Russia considers all cargo ships headed for Ukraine as potential targets.

    Ferrexpo, producing iron ore pellets, has utilized only half of its four pellet lines due to decreased export capacity. Chairman Lucio Genovese intends to restore exports via the route, acknowledging the challenging circumstances brought about by Russia’s invasion of Ukraine. This predicament has significantly limited shipping opportunities to the Middle East and Asia.

    In related articles, Ferrexpo ranks among the FTSE 350’s poorest performers of 2023, grappling with declining profits and revenue due to the impact of the war on its operations. Additionally, 34 employees have lost their lives in the conflict, while 754 others serve in Ukraine’s military.

    Despite these challenges, Ferrexpo shares experienced a 6.6 percent surge, gaining 5.55p to close at 90.25p. Meanwhile, the London stock market witnessed a premature closure on the final trading day of the year, with the FTSE 100 increasing slightly by 0.1 percent and the FTSE 250 dropping 0.2 percent.

  • Moody’s confirms Metinvest’s ratings, changes outlook from negative to stable

    Moody’s confirms Metinvest’s ratings, changes outlook from negative to stable

    The international rating agency Moody’s Investors Service has confirmed the corporate rating (CFR) of Metinvest B.V. at the “Caa3” level, the default probability rating “Caa3-PD” and the national scale rating “Caa3.ua.”

    The outlook for Metinvest’s ratings has been improved from negative to stable, the agency said in a statement.

    The rating action explains that the affirmation of Metinvest’s ratings and the change in outlook from negative to stable reflects Moody’s expectation that the company will continue to generate positive free cash flow (FCF) in 2024 to generate higher cash balances, in specifically in its offshore accounts to support ongoing debt service and repayment of outstanding notes due June 2025.

    However, the ratings remain constrained by the Ukrainian government’s domestic and foreign currency ceiling, set at Caa3. In addition, Metinvest’s Caa3 CFR reflects the company’s operational and logistics risks associated with the ongoing war in Ukraine.

    Moody’s said the company has a significant portion of its assets in Ukraine and continues to face financial and operational challenges in the midst of Russia’s invasion of the country, including direct damage to its assets in 2022, labour shortages and limited access to the necessary infrastructure to freely export its goods in the current extremely tense circumstances. However, Moody’s states that the opening of the Black Sea corridor in the second half of 2023 has ensured an increase in export capacity.

    Despite these problems, Metinvest has demonstrated financial stability. The company’s 2023 revenue of $7.397 billion was down 11% from the previous year. Moody’s notes that the full-scale invasion of Ukraine affected the comparability of Metinvest’s 2023 results with the previous year, as 2022 results included almost two months of activity before the war.

    Lower selling prices contributed to overall revenue declines of 51% and 15% in the Mining and Metals segments in 2023, respectively, for sales and resale of steel, coke, iron ore and coking coal products. Price pressures were partly mitigated by higher sales volumes, particularly in the company’s mining segment, with strong growth in iron ore product sales (iron ore concentrate and pellets), while metals production volumes remained relatively flat, supported, among other things, by higher volumes production of Kametstal (billings) and re-rolling assets, as well as strengthening the resale of steel and coke.

    The increase in volumes was due, among other things, to the opening of the Black Sea corridor in the second half of 2023, providing additional export opportunities and opportunities to reach distant markets. Moody’s expects Metinvest to benefit from improved access to export markets during 2024, leading to higher capacity utilization and resulting higher sales volumes, which will more than offset projected lower average selling prices and lead to a moderate recovery arrived.

    At the same time, Metinvest experienced a significant decline in adjusted EBITDA (according to the company) to $861 million in 2023 from $1.873 billion in the previous year. The decline was mainly due to lower average selling prices and higher transportation costs, as well as a higher comparison base in 2022, where nearly two months of operations were unaffected by the war.

    Despite the decline in EBITDA, Metinvest generated significant positive free cash flow (calculated by the company as net cash from operating activities minus net cash used in investing activities) of $410 million in 2023, supported by favourable working capital movements following a reduction in steel and coal reserves products, as well as lower capex of $284 million focused on maintenance capex to preserve cash.

    Moody’s believes Metinvest will benefit from an adequate liquidity position over the next 18 months, supported by a cash balance of $646 million at year-end 2023, which is expected to increase in 2024 due to significant positive free cash flow generation.

    The rating agency suggests that about 75% of cash balances are held in offshore accounts, but some of this cash is subject to a requirement to repatriate foreign currency earnings from Ukrainian exports within 180 days under National Bank of Ukraine (NBU) restrictions. Although the amount of fully unrestricted offshore cash is unknown, the company has continued to meet its debt obligations since the start of the war, and liquidity is likely to be sufficient in 2024 and 2025 for Metinvest to fund its operations, service interest payments and coupon payments on its debt and will repay the outstanding amount of approximately EUR 234 million on the senior notes due June 2025.

    The outstanding amount of the senior notes due 2025 was reduced to EUR 234 million in early 2024 following the company’s repurchase of approximately EUR 61 million of the notes and their immediate repayment in January and February 2024.

    At the same time, Moody’s said that Metinvest will face significant debt maturities beyond 2025, including $494 million of outstanding senior notes due April 2026, which remain subject to increased risk of default in the absence of market access debt capital, as well as strong earnings and cash flow recovery.

    The stable outlook reflects Moody’s expectation that Metinvest will increase sales volumes in 2024, with the majority directed to exports to mitigate the decline in forecast prices, while maintaining sufficient levels of offshore cash balances to support the timely repayment of senior notes maturing in June 2025. The stable outlook also reflects the expectation that while the operating environment will remain challenging due to the ongoing war in Ukraine, the company will not experience a deterioration in its production and logistics capabilities.

    A rating upgrade at this stage is unlikely unless there is a change in sovereign ratings or ceilings, as Metinvest’s CFR is at the level of Ukraine’s country ceiling. Downward pressure on the ratings could come from a downgrade of the sovereign rating or further weakening of the company’s credit profile as a result of pronounced physical damage to assets, market and logistics disruptions, cash flow generation and reduced liquidity. Erosion of liquidity is likely to increase the probability of default, which could also lead to downward pressure, as can the expectation of lower recovery to bondholders in the event of default.

    Metinvest consists of mining and metallurgical enterprises located in Ukraine, Europe and the USA. Its main shareholders are the SCM group (71.24%) and Smart Holding (23.76%), which jointly manage it.