Month: May 2025

  • Firing the Starting Gun: Turning Insight into Action in the Race to 2030

    Firing the Starting Gun: Turning Insight into Action in the Race to 2030

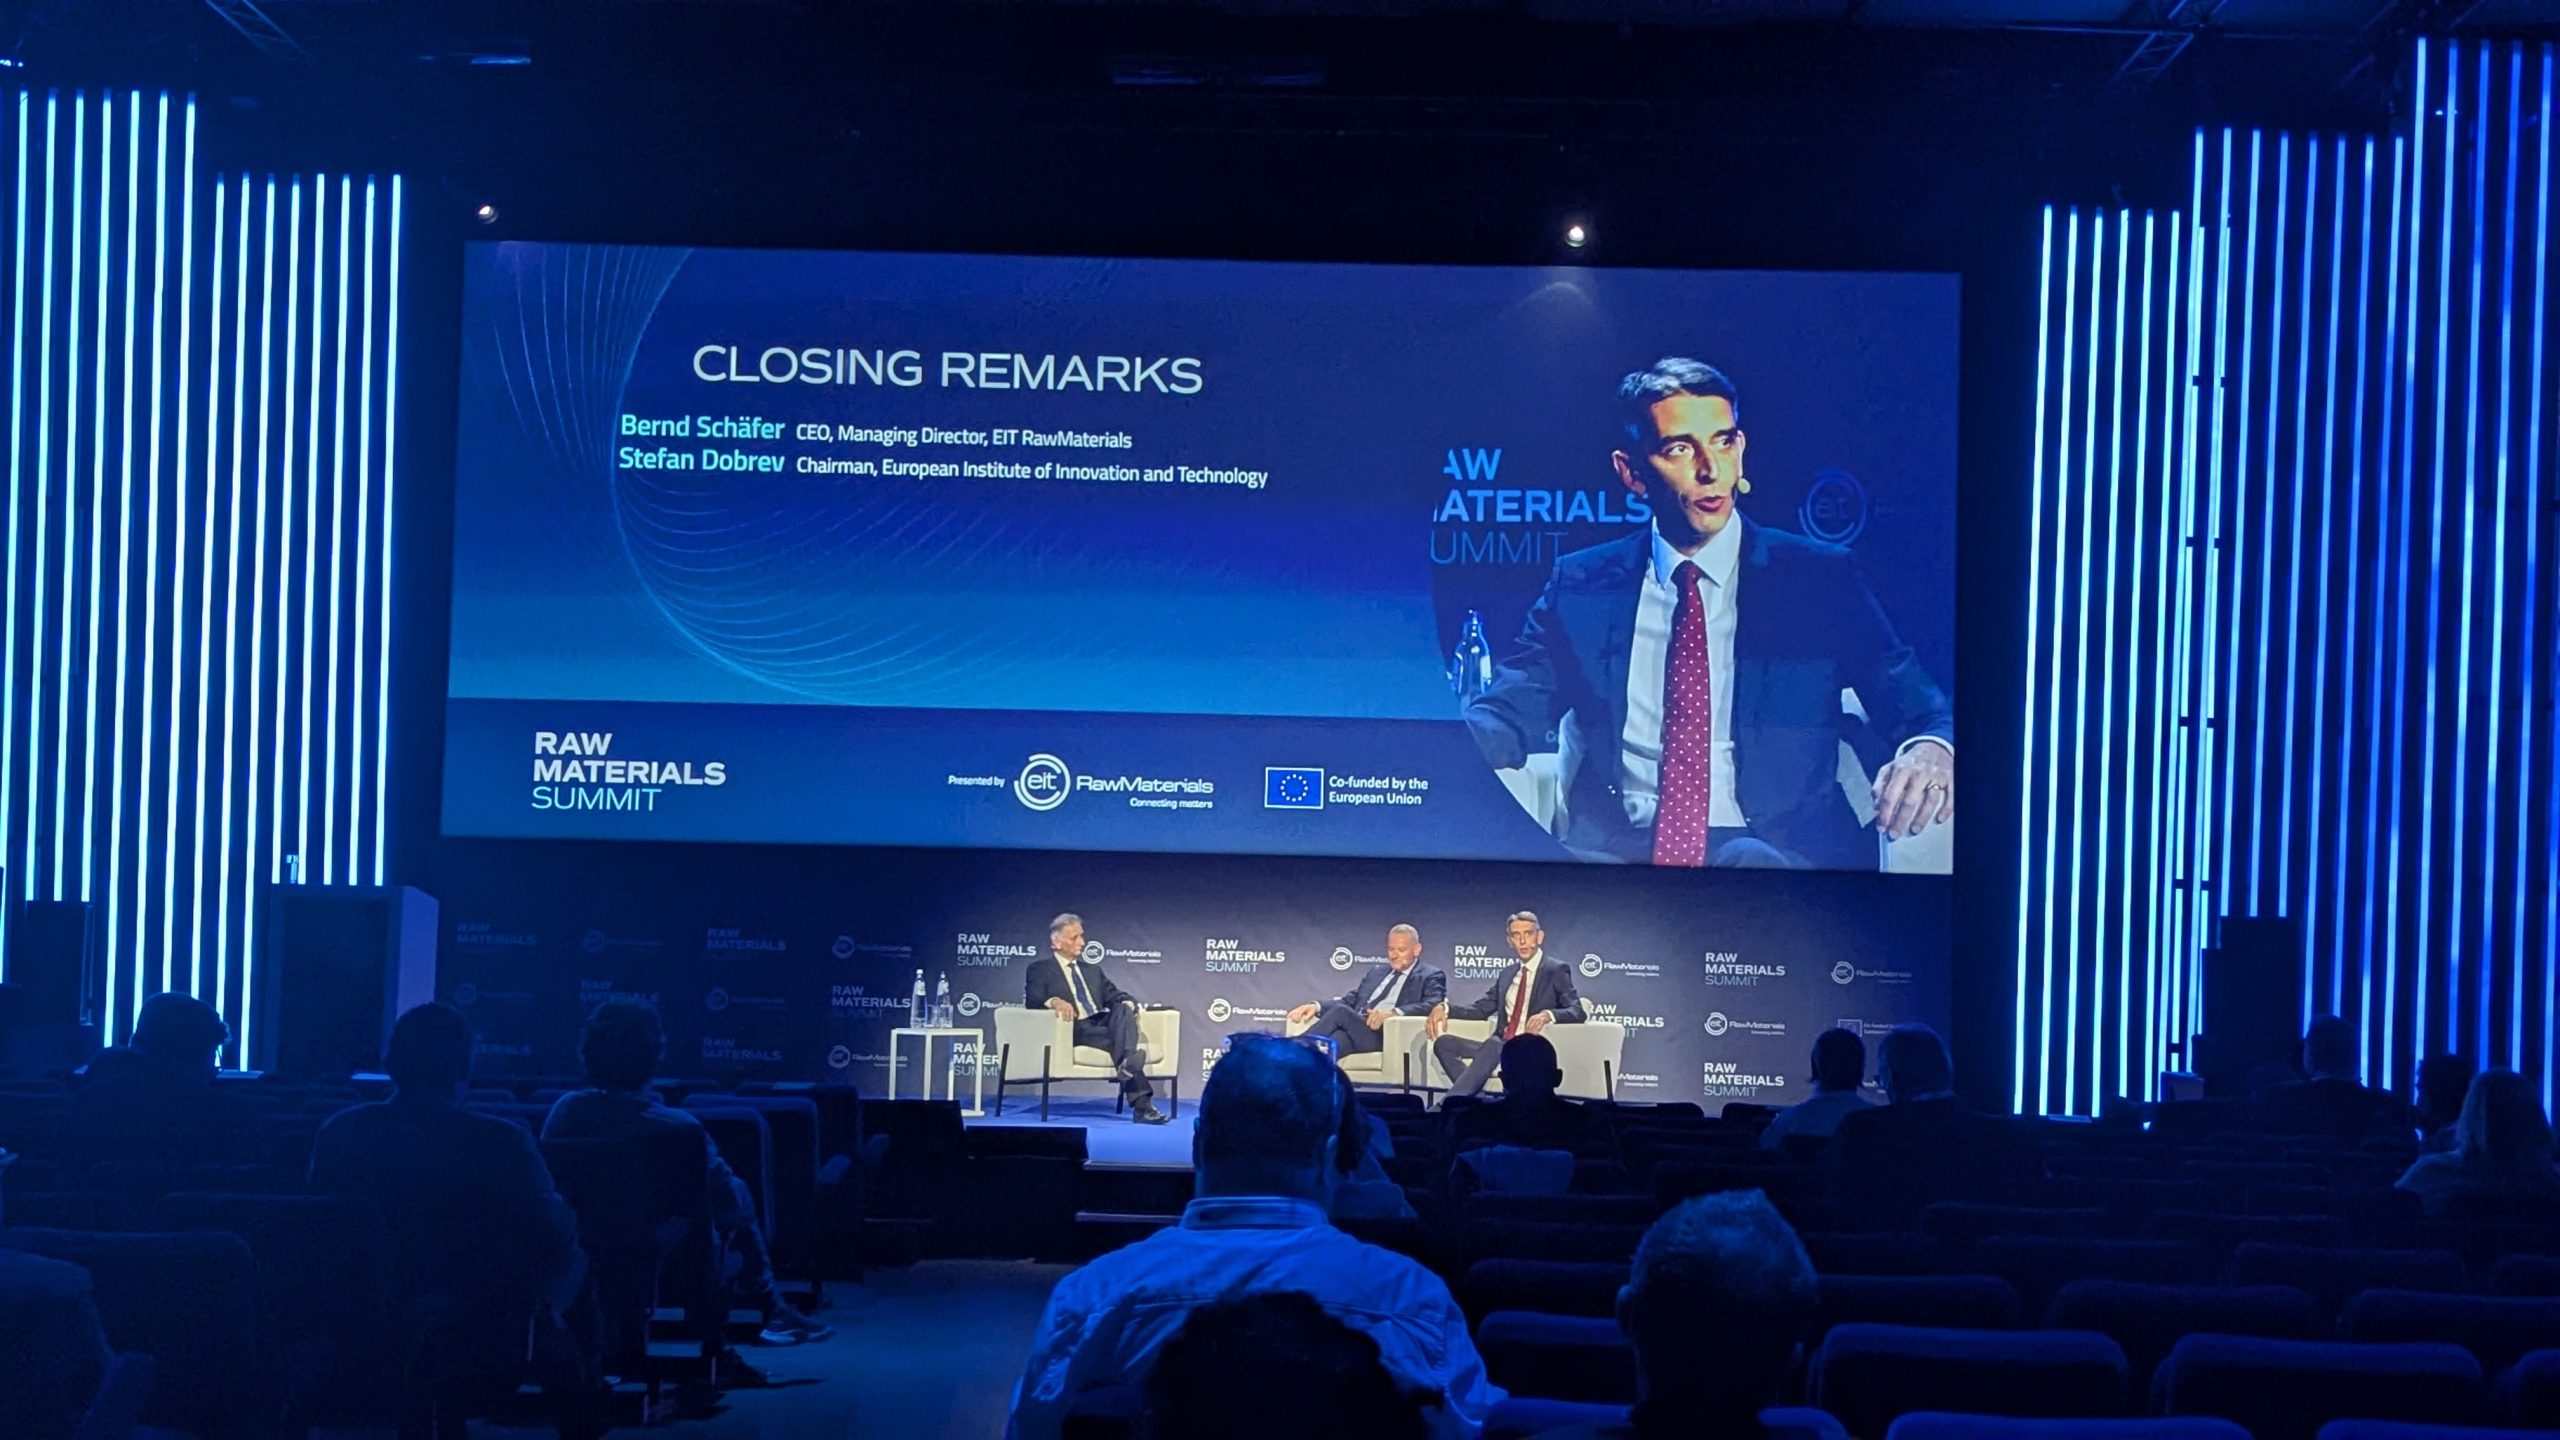
    As the seventh edition of the Critical Raw Materials Summit drew to a close in Brussels, a closing session posed a series of compelling questions to the audience—questions that go beyond policy declarations and dig deep into how Europe must act to secure its raw materials future.

    Moderated with thoughtfulness and energy by Peter Handley, the final panel brought together Stefan Dobrev (Chair, EIT Governing Board) and Bernd Schäfer (CEO, EIT RawMaterials) for a sharp and candid reflection. Here are some of the critical questions and takeaways that framed the conversation:

    -How do we turn knowledge into impact?
    Not just reports or roadmaps, but tangible benefits for citizens, companies, and Europe’s industrial resilience—transforming innovation into products, battery life, and economic value.

    -It’s time to rethink security not just in terms of weapons, but as a question of access—access to critical materials, supply chains, talent, and technology.

    -From cross-border partnerships to internal collaboration among stakeholders, building strong and flexible ecosystems emerged as a cornerstone for success.

    -Acting on foresight—rather than waiting for mandates—was framed as a key responsibility for innovation communities and industrial clusters.

    -Transparency, analytical rigour, and courage to act—especially when outcomes are uncertain—were named as critical success factors.

    -Redesigning supply chains, forging new international partnerships, and ensuring circularity demand risk-taking and creativity.

    Throughout the Summit sessions, a recurring theme was the call for courage—the courage to innovate, to collaborate, and to confront challenges with proactive solutions. Europe, it was said, must not wake up too late to the risks ahead. Strategic autonomy, competitiveness, and sustainability all depend on moving from insight to action.

    A few final reflections from the session:

    The Summit saw a stronger-than-ever presence from international partners and DGs across the European Commission. The CEO Roundtable with BloombergNEF marked a promising new format for high-level engagement on circularity.
     

  • Crossing the Valley of Death: Europe’s Raw Materials Start-up Ecosystem

    Crossing the Valley of Death: Europe’s Raw Materials Start-up Ecosystem

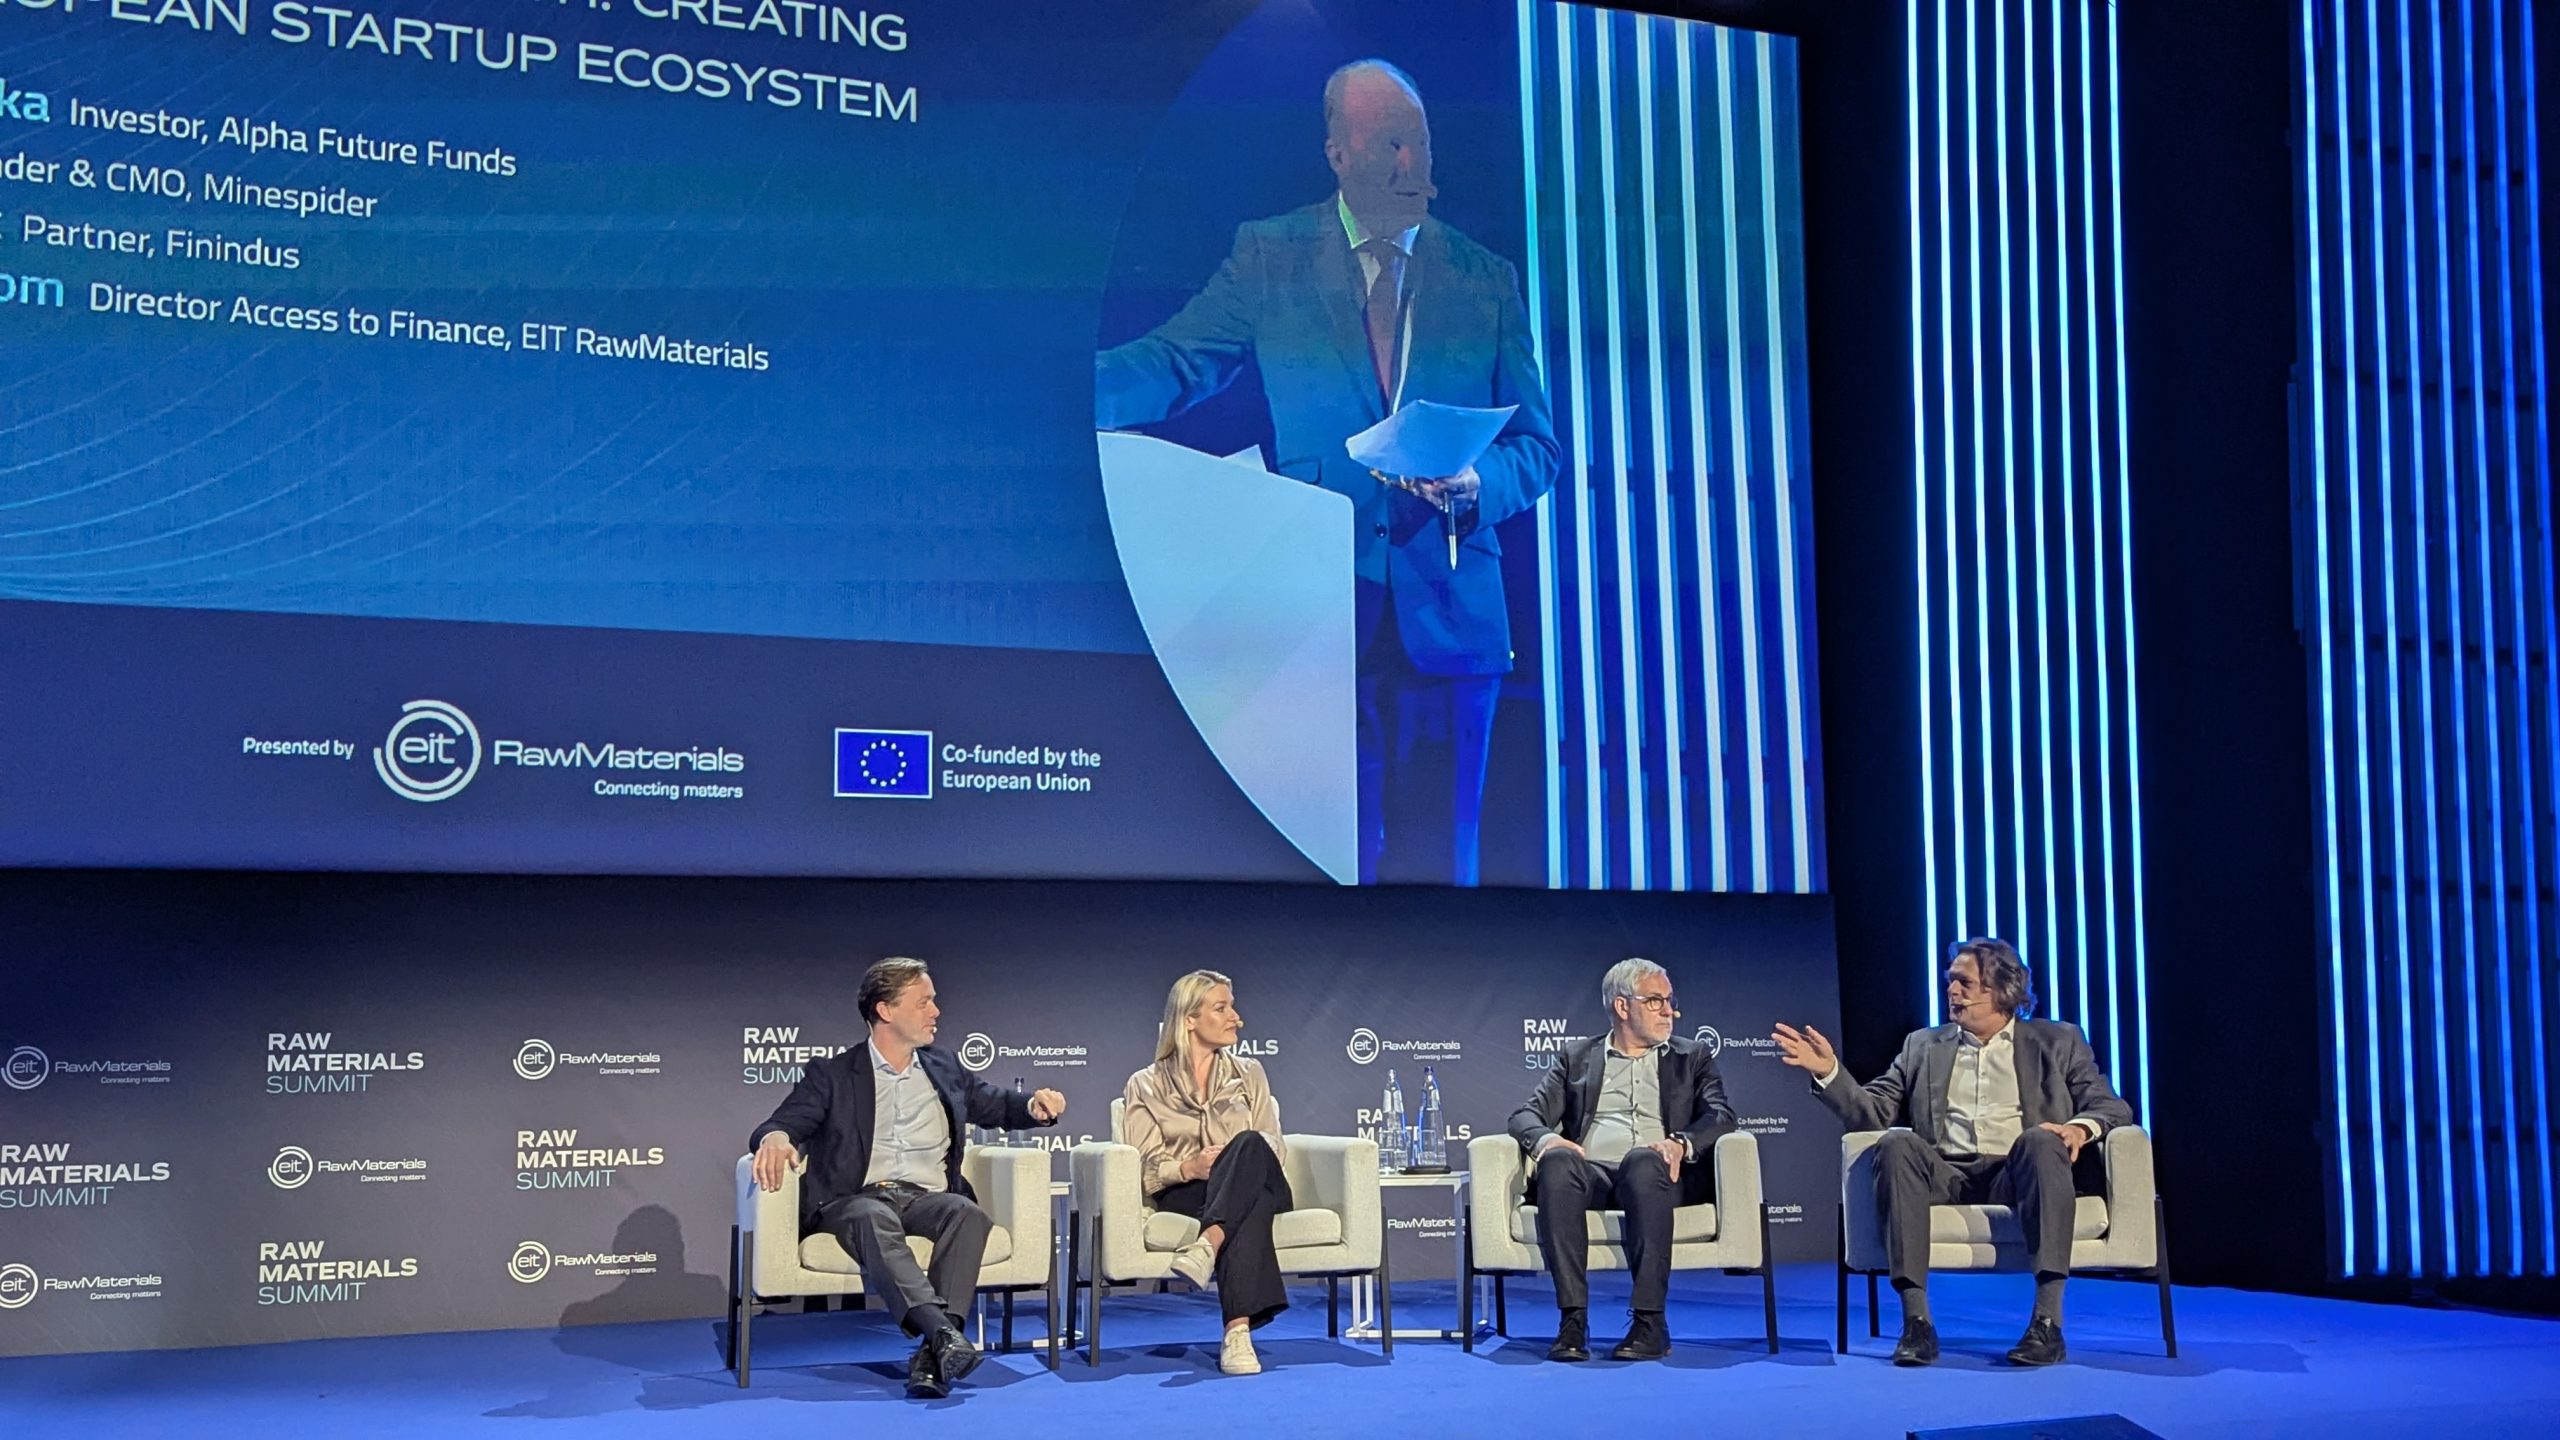
    At the EIT Critical Raw Materials Summit in Brussels on May 15, industry experts discussed the challenges facing Europe’s raw materials start-ups. The panel featured Antony Slotboom (EIT RawMaterials), Benedikt Sobotka (Alpha Future Funds), and Ella Cullen (Minespider), with David Eades moderating.

    Key insights included:

    – Europe has sufficient capital but lacks focus on the crucial development stage where start-ups are too small for banks but need more funding than typical VCs provide

    – The notorious “Valley of Death” affects many promising innovations that struggle to transition from early-stage development to market-ready solutions

    – Cultural differences with the US: European investors are more cautious, while US investors take bigger risks with larger funding tickets – “In the US, you might see a $27 million ticket from a family office – that’s not unusual”

    – Corporate partnerships are vital but challenging to secure: “It’s easier to get a cheque from a VC than a purchase order from a major corporate”

    – European start-ups must think globally from day one, seeking customers and investors internationally

    – The raw materials market is inherently global, with downstream clients often in Europe due to regulations, but upstream clients across Australia, Latin America, and Africa

    – Europe’s strength lies in collaboration networks between start-ups, corporates, and research institutions, but support must extend beyond initial phases

    Cullen shared Minespider’s experience: “We were fortunate to get Horizon 2020 and EIT RawMaterials funding, but the real challenge is scaling – building a fully functional solution and getting it to market.”

    Sobotka concluded: “We need to move beyond the mindset that every junior mining company must become a major. Sometimes, it’s about building a portfolio and accepting that not every venture will succeed – but the ones that do can pay for the rest.”

    The panel called for a more risk-tolerant investment culture and greater ecosystem collaboration to help European raw materials start-ups compete globally.

    hashtagEITSummit hashtagRawMaterials hashtagInnovation hashtagStartups hashtagVentureCapital hashtagSustainability

  • Europe’s Critical Raw Materials Race: 20 Years Behind, But Not Too Late.

    Europe’s Critical Raw Materials Race: 20 Years Behind, But Not Too Late.

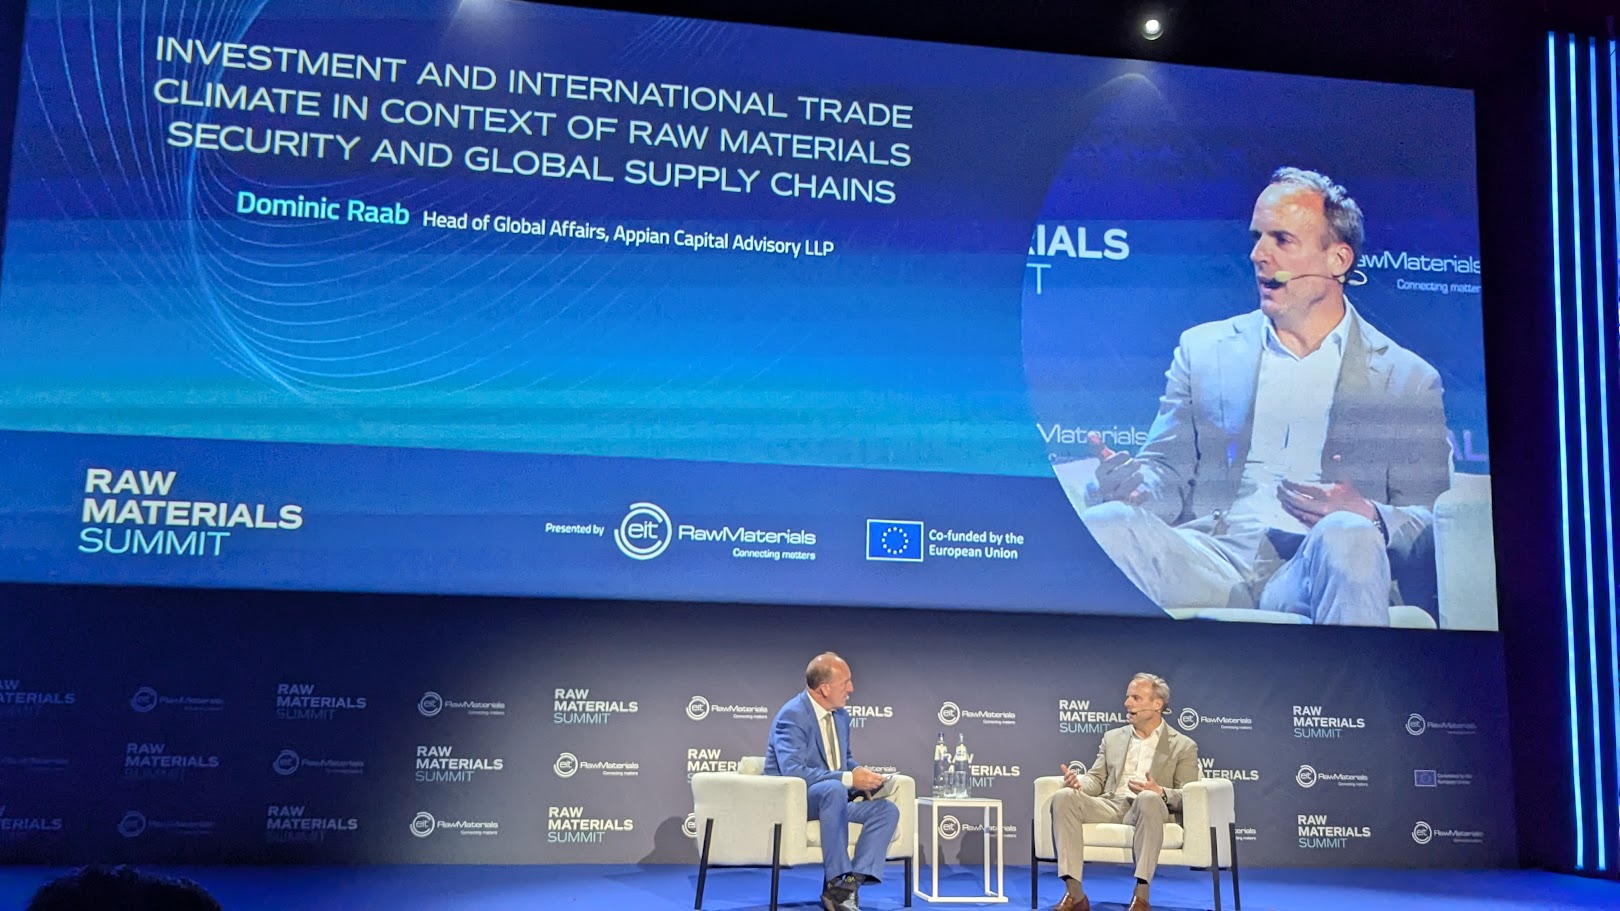
    On 14 May, MINEX Forum had an opportunity to attend a fireside chat with the Right Honourable Dominic Raab—former UK Foreign Secretary and Deputy Prime Minister—at the EIT Critical Raw Materials Summit in Brussels.

    Raab offered a frank and sobering assessment: Europe is two decades behind China in industrial strategy and supply chain resilience when it comes to critical raw materials.

    He pointed to China’s head start and dominant position in the critical minerals market—not only in extraction but across the entire value chain including processing, refining, and end-product manufacturing. In stark contrast, Europe remains highly fragmented, slow-moving, and unclear in governance when it comes to critical materials strategy.

    What stood out most? His call for “friendshoring.”

    Raab emphasised that the West—particularly Europe—must look beyond its borders and proactively build strategic partnerships with non-EU countries across Africa, South America, the Middle East, and Asia. These partnerships should not only secure access to raw materials, but also enable co-investment in local processing and infrastructure—an offer that goes beyond extraction and addresses shared economic development.

    He noted: “We’ve got to start making better offers. Because China already is.”

    Key takeaways from the session:

    The urgency is real. We are not only in a resource competition but a geopolitical one.

    Friendshoring isn’t charity—it’s smart economics and strategic security.

    Europe must move from policy poetry to delivery prose. Governance, coordination, and speed are now strategic assets.

    Creating clear points of contact and leadership across member states is essential to attracting investment and building trust with global partners.

    This is not a race we can afford to lose—and catching up demands bold, collaborative moves.

  • Uzbekistan Explores Cooperation with Utah in Mining and Geological Sectors

    Uzbekistan Explores Cooperation with Utah in Mining and Geological Sectors

    On May 16, 2025, First Deputy Minister of Mining Industry and Geology, O. Nasritdinhojaev, along with representatives from the Ministry, met with delegation from the U.S. state of Utah.

    During the meeting, the parties discussed the ongoing reforms in Uzbekistan’s mining sector, the investment opportunities being created, and explored prospects for cooperation in investments, advanced technologies, and scientific research, considering Utah’s economic potential and its advanced expertise in the mining and geological fields.

    Additionally, both sides exchanged views on improving the qualifications of lecturers and students of the University of Geological Sciences under the Ministry of Mining Industry and Geology. Discussions also included the possibility of opening branches of Utah-based universities specializing in geology and mining—such as the University of Utah and Utah State University—in Uzbekistan.

  • Kazakhstan Faces Geologist Shortage Due to Gap in Specialist Training

    Kazakhstan Faces Geologist Shortage Due to Gap in Specialist Training

    Kazakhstan is experiencing a severe shortage of geologists due to a long pause in the development of the profession. This was reported by Margulan Baibatyrov, Deputy Chairman of the Committee of Geology at the Ministry of Industry and Construction, according to Kazinform News Agency.

    According to him, despite the high salaries and the prestige of the profession, there was a period in Kazakhstan’s geological exploration history when the work of geologists was not in demand. This led to a significant gap of about 30 years between generations of specialists.

    The exact number of geologists currently needed in the country was not specified, but Baibatyrov noted that all graduates from universities specializing in this field are successfully employed.

    The issue of the shortage of qualified geologists was previously raised by Rashid Zhaksylykov, Chairman of the Board of the Association of Legal Entities “Union of Oilfield Service Companies of Kazakhstan.” In an interview with Kazinform in March 2025, he emphasized the need to intensify the training of specialists in this area.

  • Anglo Asian Mining Begins Production at Gilar Underground Mine in Azerbaijan

    Anglo Asian Mining Begins Production at Gilar Underground Mine in Azerbaijan

    Anglo Asian Mining PLC (AIM: AAZ) has commenced production at its Gilar underground mine, situated within the Gedabek site in Azerbaijan. The company targets an output of approximately 2,000 tonnes of ore per day, with expectations to ramp up to a monthly production rate of 50,000 to 60,000 tonnes.

    A maiden JORC mineral resource estimate released on December 11, 2023, revealed that the Gilar deposit holds 6.10 million tonnes of mineralisation. The average grades include 0.88% copper—equating to nearly 54,000 tonnes of copper—and 1.30 grams of gold per tonne, totaling over 255,000 ounces of gold.

    Following the announcement, shares of Anglo Asian Mining rose by 7% in London, bringing the company’s market value to £169.9 million ($226.9 million).

    In 2024, Anglo Asian produced 16,760 gold-equivalent ounces, although production faced disruptions due to a partial environmental shutdown. Operations resumed by the end of the year.

    The company plans to evolve into a multi-asset, mid-tier copper and gold producer by 2029, with copper becoming its primary product. As part of its growth strategy, Anglo Asian intends to bring four new mines into production between 2025 and 2029: Gilar, Zafar, Xarxar, and Garadag.

  • Navoi Mining Secures $500M Eurobond Placement Ahead of IPO

    Navoi Mining Secures $500M Eurobond Placement Ahead of IPO

    Navoi Mining & Metallurgical Company (NMMC) has successfully completed a $500 million corporate bond placement in London, marking a significant step in its financial strategy as it prepares for a stock listing.

    The Uzbekistan state-owned enterprise, ranked as the fourth-largest gold producer globally, operates its vast resources primarily from the Muruntau deposit in the Kyzylkum Desert, which holds an estimated 150 million ounces of gold.

    The newly issued bonds, backed by favourable capital market conditions, carry a five-year tenor with an annual coupon rate of 6.75%. The offering was made available under Regulation S and Rule 144A of the US Securities Act, ensuring broader investor participation.

    Leading financial institutions, including Citi, JP Morgan, Société Générale, and MUFG, acted as joint bookrunners and lead managers for the transaction. Demand for the notes was robust, peaking at over $2.3 billion, making the issue more than 4.6 times oversubscribed.

    “The success of this bond placement reflects strong investor confidence in Uzbekistan’s economic reforms and NMMC’s sustainable growth prospects,” the company said in a statement.

    The proceeds will be directed towards optimising and diversifying NMMC’s credit portfolio under improved terms, as it moves towards its planned initial public offering (IPO) later this year. The Uzbek government has proposed selling up to 5% of the company in the IPO, positioning NMMC for further expansion in international markets.

  • European Tungsten Prices Reach Highest Level Since 2013 Amid Chinese Export Curbs

    European Tungsten Prices Reach Highest Level Since 2013 Amid Chinese Export Curbs

    European tungsten prices have surged to their highest point since 2013, driven by China’s tightening restrictions on critical mineral exports. The price of ammonium paratungstate (APT)—a vital intermediate in tungsten metal production—has reached $400 per metric ton unit (mtu) on the European spot market, marking an 18% increase since February, according to Reuters.

    The spike follows China’s recent export curbs and quota reductions on key strategic metals, including tungsten, tellurium, molybdenum, bismuth, and indium. These measures, imposed in retaliation to US tariffs earlier this year, have intensified global supply concerns.

    China dominates global tungsten production, accounting for over 80% of the 81,000 tons produced worldwide last year, according to the US Geological Survey (USGS). Tungsten’s exceptional properties—such as its highest melting point of any element, extreme hardness, and excellent electrical and thermal conductivity—make it indispensable across various industries. Initially popularized in incandescent light bulbs, tungsten now underpins sectors ranging from aerospace and semiconductors to defense and industrial drilling.

    Tungsten carbide, second only to diamond in hardness, is crucial for metalworking tools and industrial drills, while tungsten crucibles facilitate the melting of other high-temperature materials. In the defense sector, tungsten is used for “penetrators,” armor-piercing projectiles currently in high demand amid the ongoing conflict in Ukraine.

    China’s Tightening Grip on Exports
    The global tungsten scarcity has been exacerbated by China’s export restrictions. The country’s first tungsten ore mining quota for 2024 was set at 58,000 tons—a 6.5% decrease from the previous year.

    “Since the Chinese export ban was announced, there has been an over-reliance on scrap supplies, but now those are running thin, and there’s growing panic over the inability to secure new primary tungsten material,” said Oliver Friesen, CEO of Guardian Metal Resources.

    The stakes are especially high for the United States, which ceased commercial tungsten mining in 2015 and remains heavily reliant on imports. A looming 2027 deadline mandates the US military to eliminate purchases of tungsten mined or processed in China or Russia—the latter being the world’s third-largest producer.

    North American Efforts to Secure Supply
    In response, Canada’s Almonty Industries recently announced an offtake agreement to provide tungsten oxide exclusively for US defense applications. The company operates tungsten mines in Spain, Portugal, and South Korea.

    “Almonty can produce enough tungsten for US/EU/Korea defense demand but not enough for the entire US/EU/Korea market—defense and civilian combined,” Almonty’s CEO Lewis Black stated. Shares of Almonty rose 4.6% in Toronto following the announcement, giving the company a market capitalization of C$688 million ($492 million).

    “Tungsten is a small market… But the industries that depend on it are exponentially bigger, which is why it is on everyone’s critical mineral list,” Reuters columnist Andy Home noted.

  • Kazatomprom and Romania’s SN Nuclearelectrica Discuss Expanding Uranium Supply Cooperation

    Kazatomprom and Romania’s SN Nuclearelectrica Discuss Expanding Uranium Supply Cooperation

    Kazatomprom, Kazakhstan’s national atomic company, held discussions with Romania’s Ministry of Energy and state-owned company SN Nuclearelectrica S.A. regarding the expansion of natural uranium supplies and the development of the beryllium industry.

    A key outcome of the talks was the discussion of terms for a ten-year contract to supply Kazakhstani natural uranium for Romania’s current and planned nuclear power plants. Kazatomprom anticipates that the contract will strengthen long-term cooperation between the two countries and provide reliable raw material supplies for Romania’s nuclear energy sector.

    Additionally, the Ulba Metallurgical Plant (UMP), a subsidiary of Kazatomprom, may begin processing Romanian beryllium. Romanian representatives expressed interest in scientific and technical cooperation with UMP and further exploration of processing beryllium raw materials from Romanian deposits. UMP specializes in processing beryllium and tantalum and exports its products globally.

    In Kazatomprom’s 2024 report, uranium production (proportional to its ownership share) reached 12.3 thousand tons, marking a 10% increase from 11.1 thousand tons in 2023 and 11.4 thousand tons in 2022. This growth was mainly driven by joint ventures Budenovskoye, Akbastau, and Karatau.

    However, production of beryllium products fell to 735.1 tons in 2024, down from 842.8 tons in 2023 and 1,295.4 tons in 2022. Tantalum production also declined, with 135.1 tons produced in 2024 compared to 153.8 tons in 2023 and 165.3 tons in 2022.

    Kazatomprom’s 2024 financial report stated that revenue reached 1.81 trillion tenge (up from 1.43 trillion tenge in 2023). The largest consumers of Kazakh uranium and other products included:

    • China: 663.7 billion tenge (522.5 billion tenge in 2023)

    • Kazakhstan: 336.6 billion tenge (182.6 billion tenge)

    • Russia: 253.2 billion tenge (215 billion tenge)

    • Canada: 164.9 billion tenge (131.1 billion tenge)

    • USA: 140.9 billion tenge (152.5 billion tenge)

    • France: 110.9 billion tenge (82.6 billion tenge)

    • United Kingdom: 44.7 billion tenge (40.6 billion tenge)

    • UAE: 29.3 billion tenge (no imports in 2023)

    Other countries purchased Kazakh products worth 69.2 billion tenge, down from 107.6 billion tenge in 2023. Although Romania was not among the largest consumers, Kazatomprom confirmed it continues to supply its products to the country.

  • Uzbekistan Focuses on Supporting Construction Material Producers

    Uzbekistan Focuses on Supporting Construction Material Producers

    A meeting was held with construction material producers of Uzbekistan under the leadership of Deputy Prosecutor General S.I. Samadov and Minister of Mining Industry and Geology B.F. Islamov. The event brought together representatives of responsible departments to address existing challenges in the sector.

    Key issues discussed included operational problems faced by producers, particularly in cement manufacturing, and strategies for overcoming these obstacles. A major point of concern was the availability of coal required for production.

    Officials informed entrepreneurs that coal deposits are actively being developed in the Surkhandarya region, presenting an opportunity for local coal fuel to be supplied to manufacturers. This initiative aims to improve the reliability and quality of fuel for construction material production, reducing dependence on external sources.

    The meeting underscored the government’s commitment to supporting local industries and enhancing the efficiency of Uzbekistan’s construction material sector.