Website: Europe.com

  • UK deepens engagement with Kazakhstan through green growth, critical minerals and people-to-people ties

    UK deepens engagement with Kazakhstan through green growth, critical minerals and people-to-people ties

    The United Kingdom is recalibrating its engagement with Kazakhstan, placing growing emphasis on green technology, critical minerals, education and cultural cooperation, according to UK Ambassador to Kazakhstan Sally Axworthy.

    In an interview with The Astana Times, Axworthy said London sees Kazakhstan as a key long-term partner as global supply chains shift and demand for sustainable growth increases. Rather than pressure or politics, the UK approach is built around practical cooperation, business links and human connections.

    She noted that the UK Embassy’s role extends well beyond traditional diplomacy, focusing on connecting Kazakh businesses with British expertise. This cooperation is already visible in Kazakhstan’s urban landscape, with major architectural landmarks designed by British firms. These include Khan Shatyr in Astana by Foster and Partners, the newly opened Almaty Museum of Arts by Chapman Taylor, and the Tselinny Center of Contemporary Culture by British architect Asif Khan.

    Beyond flagship projects, Axworthy stressed that small and medium-sized enterprises are a growing priority. Through the Green and Inclusive Growth Programme, the UK is supporting startups with financing and advisory services, particularly in green, digital and AI-driven sectors. She confirmed that a new venture capital fund is being set up to invest in startups, with a special focus on green technologies and women-led businesses.

    Digital innovation has also become a key area of cooperation. During the Digital Bridge forum, the UK Embassy supported an event where startups from across Central Asia pitched to investors, reflecting Kazakhstan’s ambitions in artificial intelligence and technology-led growth.

    On energy and climate policy, Axworthy said the UK’s own decarbonisation experience underpins its partnership offer. She noted that the UK now generates about half of its electricity from green sources and has cut emissions by nearly 50% since 1990 while expanding its economy by 80%. This, she said, aligns naturally with Kazakhstan’s net-zero target for 2060.

    Critical minerals are central to this cooperation. Axworthy outlined the UK’s updated Critical Minerals Strategy, which focuses on domestic production, financial infrastructure and resilient supply chains. While the UK is developing resources such as lithium and tin in Cornwall, she highlighted London’s role as a global financial hub and the importance of partnerships with resource-rich countries like Kazakhstan.

    She cited joint projects already under way, including rhenium recycling through a partnership between Maritime House and Zhezkazgan Redmet, with output expected to supply up to a quarter of global rhenium demand for uses such as aircraft turbines produced by Rolls-Royce. A vanadium project by Ferro-Alloy Resources could eventually meet up to 10% of global demand.

    Education and standards underpin these economic ties. Axworthy pointed to the opening of a branch campus of Cardiff University in Astana, offering courses in geological exploration, as well as cooperation on transparency standards through the Extractive Industries Transparency Initiative.

    Addressing geopolitics, Axworthy described Kazakhstan’s multivector foreign policy as logical given its geography and said the UK does not expect exclusive alignment. She recalled remarks by former UK foreign secretary David Cameron that partnership with Britain is about mutual security and prosperity, not choosing sides.

    Education and culture remain among the strongest pillars of bilateral relations. Nearly half of Kazakhstan’s Bolashak scholars have studied in the UK, and British universities such as De Montfort University, Coventry University and Cardiff now operate campuses in Kazakhstan. Axworthy also highlighted the role of the British Council and growing cultural links, from Kazakh language courses at Oxford University to increased interest from British creative industries.

    She added that Kazakhstan’s tourism and cultural potential is still under-represented in the UK, noting strong interest among British travellers and pointing to Almaty as a city with particular appeal.
  • European Commission seeks industry backing for ‘Made in Europe’ push ahead of Industrial Accelerator Act

    European Commission seeks industry backing for ‘Made in Europe’ push ahead of Industrial Accelerator Act

    The European Commission is urging business leaders to support and sign a French-led initiative aimed at increasing the share of industrial production based in Europe, as the EU prepares to unveil its Industrial Accelerator Act (IAA).

    According to a letter seen by Euronews, the Commission is calling on representatives from energy-intensive sectors such as steel and aluminium to back a stronger “Made in Europe” component in forthcoming legislation. The move is intended to revive Europe’s struggling industrial base amid mounting competition from China and the United States.

    The appeal comes days before the planned presentation of the Industrial Accelerator Act, which seeks to accelerate the decarbonisation of heavy industry while preserving the competitiveness of European production. The initiative builds on earlier EU legislation adopted in 2024 that prioritised domestic clean-technology manufacturing as part of the bloc’s goal to achieve climate neutrality by 2050.

    In the letter, European Commission Executive Vice-President Stéphane Séjourné warned that Europe faces a stark choice as global trade becomes increasingly shaped by tariffs, subsidies and export restrictions. Without an ambitious and pragmatic industrial policy, he argued, the EU risks a gradual erosion of its industrial capacity, technological know-how and economic sovereignty.

    Supporters say the IAA could significantly strengthen European competitiveness at a time when traditional sectors such as cement and steel, as well as emerging net-zero technologies, are grappling with weak demand and aggressive international competition. However, critics caution that the proposal could undermine competition within the EU’s single market, particularly disadvantaging member states with less developed industrial frameworks compared with countries like France and Germany.

    Several member states, including Czechia, Estonia, Finland, Ireland, Latvia, Malta, Portugal, Sweden and Slovakia, warned in December that the planned law could distort competition and affect prices, quality and business conditions across the bloc.

    Key elements of the proposal, including quotas for European-made products, financing mechanisms and state-aid rules, remain under discussion. EU officials have floated potential targets requiring 60% to 80% of certain products to be produced in Europe, with provisions to count output from non-European firms operating within the EU as “Made in Europe”.

    The Commission is also exploring ways to align supply and demand by creating so-called “lead markets” for low-carbon industrial products such as green steel and hydrogen, supported by demand-side measures. In parallel, state-aid rules may be loosened, potentially allowing member states to fund decarbonisation projects without prior notification to the Commission.

    European industry leaders have reacted positively, citing a record €350 billion trade deficit with China in 2025. In a separate letter, business representatives described the IAA as an act of economic independence, echoing warnings from former European Central Bank president Mario Draghi that Europe risks long-term decline if it fails to close the gap with global competitors.

    The Industrial Accelerator Act, initially delayed in December, is currently scheduled for presentation on 29 January, although further postponements remain possible.

  • Mkango opens UK’s first commercial rare earth magnet recycling plant in 25 years

    Mkango opens UK’s first commercial rare earth magnet recycling plant in 25 years

    Canadian rare earths company Mkango Resources has opened Britain’s first commercial facility in a quarter of a century to produce permanent magnets, marking a milestone in efforts to reduce Western dependence on China for critical minerals.

    The new plant, located in Birmingham and operated by Mkango’s subsidiary HyProMag, produces permanent magnets from recycled materials rather than newly mined ore. It uses a hydrogen-based recycling technology developed at the University of Birmingham, which enables rare earth magnets to be recovered from end-of-life products and converted into new magnetic material with significantly lower emissions than traditional mining and refining processes.

    The launch comes as Western governments seek to loosen China’s dominance in the rare earths supply chain. China currently accounts for around 70% of global rare earth mining and about 90% of refining, making alternative supply sources difficult to scale up quickly. Recycling has therefore emerged as one of the fastest ways to expand access to rare earth materials in the near term.

    Speaking to Reuters at the opening, UK Industry Minister Chris McDonald said breaking China’s grip on the supply chain was a strategic priority. The Birmingham plant supports Britain’s critical minerals strategy, which targets meeting 10% of domestic demand through local mining and 20% through recycling by 2035, supported by up to £50 million in government funding.

    The facility has an annual production capacity of 100 to 300 tonnes of permanent magnets, depending on shift patterns. According to Mkango, the plant is already attracting strong interest from automotive manufacturers. The company is also progressing plans to replicate the technology in the United States and Germany, expanding the recycling-based supply of rare earth magnets beyond the UK.

    Britain previously had magnet manufacturing capacity, but this disappeared roughly 25 years ago as production shifted overseas. The opening of the HyProMag plant represents a step toward rebuilding domestic capability in a sector seen as vital for electric vehicles, wind turbines and other clean energy technologies.

  • Ukraine selects U.S.-linked consortium to develop Dobra lithium deposit

    Ukraine selects U.S.-linked consortium to develop Dobra lithium deposit

    Ukraine has chosen a consortium that includes U.S.-connected investors as the preferred bidder to develop the Dobra lithium deposit in Kirovohrad Oblast, according to a report by The New York Times. The decision was taken on January 8 by a government commission and is expected to receive formal approval from the Cabinet of Ministers, though officials say the outcome is effectively settled.

    The winning consortium includes TechMet, an energy investment company partly owned by a U.S. government-backed investment agency, and billionaire Ronald Lauder, a long-time associate of U.S. President Donald Trump. Commission members cited the consortium’s strong technical and financial proposal, saying it met most of the tender’s criteria and denying allegations of favoritism.

    The Dobra deposit is one of Ukraine’s largest known lithium resources and is considered strategically important for technologies such as electric vehicle batteries. Development will take place under a production-sharing agreement, allowing investors to extract lithium in exchange for sharing output with the Ukrainian state.

    Under a broader U.S.-Ukraine minerals framework, half of the revenue generated for Ukraine from the project is to be channelled into a joint investment fund. Companies seeking to develop mineral deposits are also required to first present their projects to this fund, a mechanism designed to attract U.S. investment.

    While the minimum investment threshold for the tender was set at $179 million, officials indicated that the consortium’s pledged investment exceeds that figure. The agreement предусматривает spending at least $12 million on geological exploration and $167 million on launching extraction and processing, alongside compliance with environmental standards, use of Ukrainian labour and goods, and investment in local communities.

    Before mining can begin, the consortium must complete detailed geological studies to confirm the deposit’s commercial value and then finance the necessary infrastructure. Industry experts note that moving from exploration to full-scale production typically takes more than a decade.

    The Dobra project is expected to become one of the first initiatives implemented under the U.S.-Ukraine minerals partnership, following the launch of a joint reconstruction investment fund earlier this year.

  • Czech Republic to close its last black coal mine, ending more than 250 years of deep mining

    Czech Republic to close its last black coal mine, ending more than 250 years of deep mining

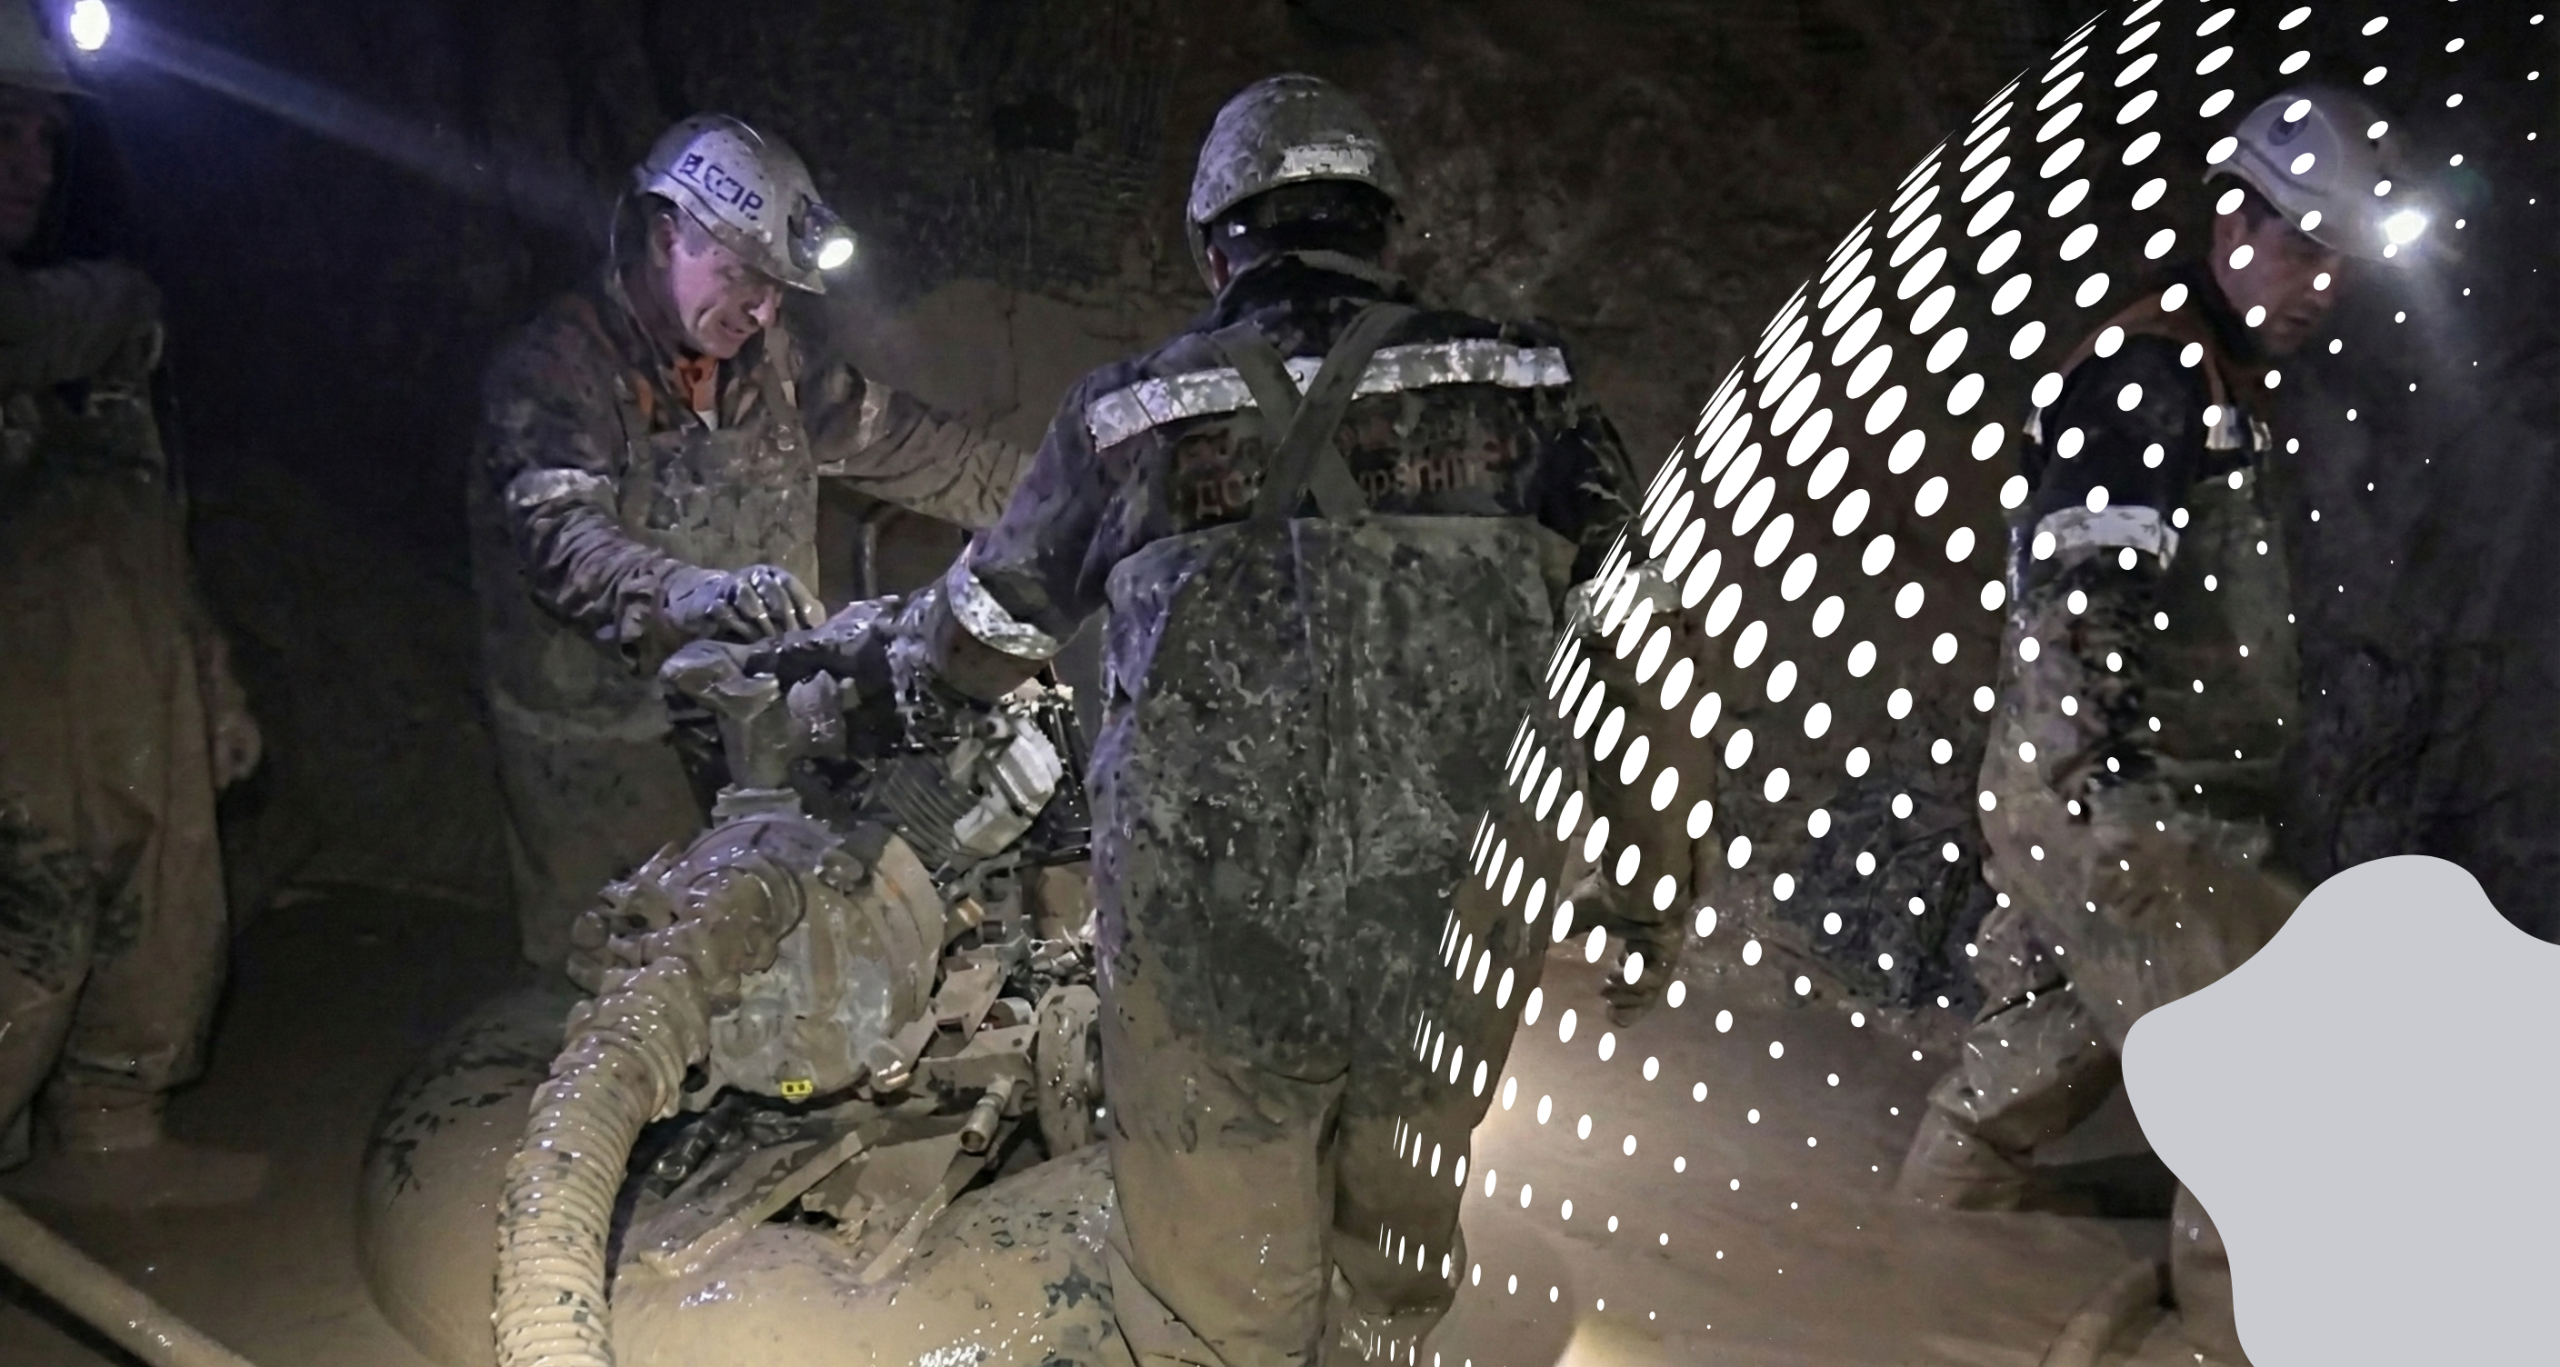
    The Czech Republic will shut its final black coal shaft at the end of January, marking the end of more than 250 years of deep coal mining that once underpinned the rise of heavy industry in Central Europe. The last coal is now being extracted from kilometre-deep shafts at the CSM mine in Stonava near the Polish border, as low global coal prices and Europe’s industrial and environmental transition erode demand.

    State-owned miner OKD had planned to close the operation three years earlier, but Russia’s full-scale invasion of Ukraine in 2022 temporarily boosted energy markets and extended the mine’s life. According to OKD director Roman Sikora, increasing mining depth has driven costs higher, making the operation uncompetitive amid weak prices.

    Coal mining in the Ostrava region began in the late 18th century, transforming the area into an industrial hub supported by railways, steelworks and large-scale infrastructure. Employment peaked in the 1980s with more than 100,000 miners and annual output of up to 25 million tonnes. Following the collapse of communist-era heavy industry after 1989, mines closed gradually and employment fell sharply. By October last year, OKD’s output had dropped to 1.1 million tonnes, with its workforce reduced to 2,300 and a further 1,550 jobs set to be cut.

    The region has since diversified its economy, supported by retraining programmes, foreign investment and EU funding. It is set to receive 19 billion Czech crowns from the EU’s Just Transition Fund to support post-coal redevelopment. OKD plans to remain active above ground through coal trading and new projects, including a battery park, data centre and a small methane-powered plant using gas from former shafts.

  • Critical Metals shares jump on Tanbreez upgrades and renewed US focus on Greenland

    Critical Metals shares jump on Tanbreez upgrades and renewed US focus on Greenland

    Shares of Critical Metals surged to their highest level in nearly three months after the company announced further upgrades to its flagship Tanbreez rare earth project in southern Greenland, amid renewed geopolitical attention on the Arctic territory from the United States.

    Earlier this week, the Nasdaq-listed company said it will acquire a fully integrated, mobile assay laboratory to support its Tanbreez project, which hosts one of the world’s largest known rare earth deposits. The laboratory, developed by mining solutions provider Bromet, will enable real-time, on-site geochemical analysis of drill core and pilot plant samples, strengthening data collection and accelerating decision-making as the project advances toward pilot-scale operations.

    Critical Metals CEO Tony Sage described the acquisition as a transformative step in moving Tanbreez from exploration into pre-mining development. The company is expected to pay around $1 million for the mobile laboratory. The move follows a recent decision to construct an Arctic-grade storage and pilot facility in Qaqortoq, scheduled for completion by mid-2026, and comes alongside potential logistics improvements linked to the planned opening of a new international airport near the project site.

    The upgrades are part of a modular, turnkey development strategy aimed at fast-tracking Tanbreez into production as early as this year. A preliminary economic assessment released last year outlined an initial production target of approximately 85,000 tonnes of rare earth oxides per year, with potential expansion to 425,000 tonnes annually. The assessment estimated a pre-tax net present value of about $3 billion and an internal rate of return of 180%, based on resources of at least 45 million tonnes within the largely underexplored kakortokite unit.

    Investor interest has also been boosted by rising geopolitical tensions surrounding Greenland. US President Donald Trump reiterated his desire for US control of Greenland this week, citing national security concerns, and senior US, Danish and Greenlandic officials held discussions in Washington on the issue. Analysts view Greenland’s vast untapped mineral resources, including rare earths, as a key driver behind Washington’s intensified interest.

    Following the announcements and geopolitical developments, shares of Critical Metals jumped as much as 35% in New York trading, lifting the company’s market capitalization to around $2.1 billion.

  • EU steps up critical minerals policy but risks falling behind the US and China

    EU steps up critical minerals policy but risks falling behind the US and China

    The European Union has intensified efforts to strengthen critical mineral supply chains that underpin the energy transition, but analysts warn that Europe is moving more slowly and offering weaker support than the United States, leaving it exposed to China’s dominant position in global markets.

    China already controls much of the global supply of solar power components and dominates processing capacity for key battery and clean energy materials, including lithium, nickel, cobalt, manganese, graphite, rare earths and permanent magnets. According to Eurostat, 95% of EU rare earth imports in 2024 came from just three countries: China, Malaysia and Russia. Data from Wood Mackenzie shows China accounts for 32% of global lithium production and controls a further 18% through overseas projects, while holding 81% of global critical minerals processing capacity.

    This concentration creates significant risks for European clean energy developers, as over-reliance on a small group of suppliers increases exposure to licensing delays, export controls and sudden supply disruptions. Industry experts note that despite growing awareness among policymakers, Europe’s response remains fragmented and underpowered.

    To accelerate investment, the EU adopted the ResourceEU action plan in December 2025. Backed by €3 billion from the Critical Raw Materials Act, the plan aims to expand domestic extraction and refining, promote recycling, reduce dependence on dominant suppliers, speed up permitting and restrict scrap exports. The EU has set targets to extract 10% of its critical minerals needs domestically, host 40% of processing capacity within the bloc and reach a 15% recycling rate by 2030.

    However, analysts say the funding and policy tools fall short of a fully fledged industrial strategy. Investment momentum has weakened amid low commodity prices, and existing regulations have not yet made most European projects sufficiently bankable. Several high-profile projects, including the Chvaletice manganese project in the Czech Republic, have stalled due to permitting delays and grid access issues, despite being labelled strategic.

    By contrast, the United States has adopted a more aggressive, security-driven approach. Through measures such as the Inflation Reduction Act, the One Big Beautiful Bill and the use of the Defense Production Act, Washington offers tax credits, grants, loans, price guarantees and offtake support to accelerate mine-to-battery and mine-to-magnet supply chains. As a result, the US is advancing diversification faster than Europe.

    While projects such as LKAB’s rare earth and phosphorus processing plant in Sweden signal progress, experts caution that Europe’s public tools for de-risking investments remain limited compared with those of the US and China. Without stronger financial instruments, streamlined permitting and a greater focus on processing and recycling, Europe risks remaining vulnerable in the global race for critical minerals.

  • Portugal aims to launch lithium prospecting tender in 2025 with focus on local benefits

    Portugal aims to launch lithium prospecting tender in 2025 with focus on local benefits

    Portugal’s government plans to launch a long-delayed tender for lithium prospecting licenses later this year, as part of efforts to strengthen Europe’s battery materials supply chain while addressing local opposition to mining projects. Environment Minister Maria da Graca Carvalho said the government is preparing a national mining strategy to be finalized by the summer, with an emphasis on community involvement and regional value creation.

    Portugal currently holds around 60,000 tonnes of lithium reserves and is Europe’s largest lithium producer, though output has traditionally been used for ceramics rather than battery-grade material. Expanding into battery-quality lithium is seen as critical for reducing Europe’s dependence on imports and supporting the continent’s clean energy transition.

    Carvalho told Reuters that future mining projects would prioritize keeping economic benefits within the country, sharing revenues regionally and creating local jobs. She added that the government is reviewing international best Reed practices while moving quickly to unlock investment. The original tender was first planned in 2018 but was repeatedly delayed due to political instability, including the collapse of several governments. The current minority administration took office in March 2025.

    Regulatory progress has already been made on specific projects. Portugal’s environmental agency APA has granted initial approval for lithium extraction at the Barroso mine, operated by Savannah Resources, as well as the Montalegre project developed by local firm Lusorecursos.

    Separately, Carvalho commented on ongoing talks between Portuguese energy company Galp and private equity-backed Moeve regarding a potential merger of their oil refining businesses. If completed, the deal would create one of Europe’s largest refining groups, with a combined capacity of about 700,000 barrels per day. The Portuguese state currently holds an 8% stake in Galp.

  • Greenland’s Kvanefjeld rare earth project highlights Europe’s late scramble for strategic minerals

    Greenland’s Kvanefjeld rare earth project highlights Europe’s late scramble for strategic minerals

    On Greenland’s southern tip, the Kvanefjeld mining project has become a symbol of both vast opportunity and prolonged paralysis. Beneath its icy terrain lies one of the world’s most significant deposits of neodymium and praseodymium, rare earth elements essential for wind turbines, electric vehicles and advanced military technologies. If developed, Greenland, a semi-autonomous territory within the Kingdom of Denmark, would become the first European source of these critical materials.

    The project is led by Energy Transition Minerals, which has long signaled readiness to move into production. However, progress stalled after the Greenlandic government imposed a ban on uranium mining in 2021, citing environmental and public health concerns. Because rare earths at Kvanefjeld are geologically associated with uranium, the ban effectively froze the project, triggering legal disputes that continue to delay development.

    Former Danish foreign minister Jeppe Kofod, now a strategic adviser to Energy Transition Minerals, said the case illustrates how regulatory uncertainty, geopolitics and high capital requirements can obstruct even strategically vital projects. Despite Greenland holding rare earth resources estimated to cover up to a quarter of global demand, alongside substantial oil, gas and other mineral potential, only two small mines are currently operating on the island.

    European interest has increased only recently. In 2023, the European Union signed a memorandum of understanding with Greenland to cooperate on mining projects, followed by the adoption of the EU Critical Raw Materials Act, which explicitly recognizes Greenland’s strategic importance. The European Commission has since committed funding to Greenland’s Malmbjerg molybdenum project to support defense-related supply chains.

    Analysts warn, however, that Europe may have moved too slowly. With the United States and China intensifying their focus on Greenland’s resources and U.S. President Donald Trump openly signaling aggressive ambitions toward the island, European policymakers risk being sidelined. Greenland’s harsh climate, limited infrastructure, small population and strict environmental rules further complicate development, even as climate change gradually improves access to previously icebound regions.

    While Brussels maintains that the future of Greenland’s resources rests solely with its people and elected authorities, growing geopolitical pressure suggests that external powers may play an increasingly decisive role in shaping the island’s mining future.

  • European Metals submits full EIA for Cinovec lithium project in Czech Republic

    European Metals submits full EIA for Cinovec lithium project in Czech Republic

    European Metals Holdings has submitted the full environmental impact assessment (EIA) for its Cinovec lithium project to the Czech Ministry of the Environment, marking a key regulatory milestone and meeting an important condition tied to EU funding. The EIA was formally lodged on 31 December, completing the two-stage environmental assessment process that began with an initial screening submission earlier in the year.

    The filing covers the entire Cinovec development and aligns with the recently completed definitive feasibility study, which outlined a mine life exceeding 26 years and forecast annual production of about 37,500 tonnes of battery-grade lithium carbonate. The ministry will now begin its formal review, with public consultations and hearings expected later in the quarter.

    The submission also satisfies a core requirement of the EU Just Transition Fund grant awarded to the project. In April, Czech authorities approved CZK 800 million, around $36 million at the time, subject to the EIA being filed by the end of 2025 and approved by mid-2026. European Metals said the project remains on track to meet the full timetable.