Website: Europe.com

  • Sweden Approves Zoning Plan for Nunasvaara South Graphite Mine Near Kiruna

    Sweden Approves Zoning Plan for Nunasvaara South Graphite Mine Near Kiruna

    Sweden has approved a zoning plan for the Nunasvaara South graphite mine near Kiruna, marking an important step in the country’s efforts to accelerate the development of domestic mining projects and strengthen Europe’s access to critical raw materials.

    The project is operated by Talga Group and is expected to produce about 100,000 metric tons of graphite ore annually. This output will be processed into roughly 20,000 tons of battery-grade anode material, primarily for use in electric vehicles and energy storage systems.

    Deputy Prime Minister Ebba Busch said the decision reflects Sweden’s strategic position within Europe’s critical minerals supply chain. She stressed that graphite plays a key role in steelmaking, battery production, and automotive manufacturing, adding that Swedish mining standards rank among the most sustainable globally.

    The decision aligns with the European Union’s broader strategy to expand domestic production of critical minerals and reduce dependence on imports from China and other suppliers, amid rising geopolitical tensions.

    Talga said it is currently focused on building its graphite processing facility in Luleå and expects mining operations at Vittangi to begin around 2029. According to company representatives, the zoning approval removes the most significant regulatory barrier, although several minor permits are still required before production can commence.

    Once operational, the Nunasvaara South mine is expected to supply around 2% of Europe’s projected graphite demand by 2030, with potential to scale up output in the future.

    Sweden is home to a wide range of mineral resources essential for green technologies, including batteries, magnets, telecommunications equipment, and defence applications. The country’s largest mining initiative is state-owned LKAB’s Per Geijer iron ore and rare earths project near Kiruna, which was designated a Strategic Project by the EU in 2025.

  • Allied Critical Metals Launches 20,000 m Drilling Campaign at Borralha Tungsten Project in Portugal

    Allied Critical Metals Launches 20,000 m Drilling Campaign at Borralha Tungsten Project in Portugal

    Allied Critical Metals has launched a fully funded 20,000 metre drilling programme at its wholly owned Borralha Tungsten Project in northern Portugal, marking the company’s most ambitious exploration campaign at the site to date.

    The 2026 programme is designed to build on strong drill results delivered in 2025 and to further define the scale and grade of tungsten mineralisation ahead of economic studies and potential resource expansion. Drilling will combine core and reverse circulation methods across several priority target zones within the Borralha licence area.

    The campaign will focus on step-out and infill drilling aimed at expanding and upgrading the existing mineral resource estimate, which was significantly increased in late 2025. Additional work will test extensions of the Santa Helena Breccia and other prospective zones identified during recent exploration, while also targeting the Venise Breccia north of Santa Helena, a historically recognised high-grade structure associated with wolframite and molybdenum mineralisation.

    Material collected during drilling will also be used for advanced metallurgical testing to support prefeasibility work and economic modelling. The programme is expected to generate key inputs for a Preliminary Economic Assessment that the company is targeting for completion in the first quarter of 2026.

    According to Allied, recent exploration has confirmed both bulk-style mineralisation and higher-grade corridors that could be suitable for future underground mining. The project has already passed several regulatory milestones, allowing it to advance through detailed engineering and permitting stages alongside ongoing drilling.

    The Borralha project is considered one of the more advanced undeveloped tungsten assets in Western Europe. Tungsten is classified as a critical raw material in both the European Union and the United States, highlighting the strategic importance of projects that can contribute to supply diversification away from dominant producers.

  • EU Backs Sweden’s Largest Rare Earth Project but Faces Legal Barriers of Its Own Making

    EU Backs Sweden’s Largest Rare Earth Project but Faces Legal Barriers of Its Own Making

    The European Union is channelling significant financial support into LKAB’s Per Geijer rare earth project in northern Sweden as part of its strategy to reduce dependence on China for critical raw materials. However, the same EU legal framework designed to protect the environment and Indigenous rights is emerging as a major obstacle to the project’s progress.

    The Per Geijer deposit near Kiruna has been granted Strategic Project status under the EU’s Critical Raw Materials Act (CRMA), making it eligible for EU-backed loans, guarantees and other de-risking instruments. The designation reflects the project’s importance to Europe’s green transition, defence capabilities and electric vehicle supply chains. Under the CRMA, the EU aims to mine at least 10% of its strategic raw materials domestically and process 40% within the bloc by 2030.

    To support these targets, Brussels is deploying financing through tools such as InvestEU, the Innovation Fund and European Investment Bank lending, with nearly €3 billion earmarked for mining, processing and recycling projects. Northern Sweden has been identified as a priority region, and Per Geijer is seen as a flagship initiative.

    Despite this political and financial backing, the project remains subject to Sweden’s Environmental Code and EU environmental legislation, including the Environmental Impact Assessment Directive and the Habitats and Birds Directives. These rules require extensive assessments of impacts on biodiversity, water resources, emissions and climate, and allow for legal appeals that can delay projects for years. Strategic status does not provide exemptions from these requirements.

    Additional complexity arises from Indigenous rights considerations. The Per Geijer deposit overlaps with traditional reindeer-herding land used by the Sami people, triggering legal obligations under Swedish law, EU law and international human rights conventions. Requirements for meaningful consultation and protection of minority rights sit uneasily alongside the CRMA’s push for faster permitting.

    Per Geijer is part of a broader LKAB value chain that includes rare earth extraction at Malmberget and processing facilities in Luleå, all of which have also received Strategic Project status. However, the European Commission retains the right to withdraw this status if sustainability criteria are not met or if projects fail to deliver.

    The case highlights a structural tension within EU policy. While Brussels is accelerating funding and political support to secure raw material autonomy, its environmental and rights-based legal framework gives courts and civil society strong tools to slow or block projects. The outcome in Kiruna is increasingly seen as a test of whether the EU can reconcile its industrial ambitions with the legal principles at the core of the Green Deal.

  • Ferrexpo Suspends Ukrainian Operations Again After Renewed Power Disruptions

    Ferrexpo Suspends Ukrainian Operations Again After Renewed Power Disruptions

    Ukrainian operations of Ferrexpo have been temporarily suspended after fresh disruptions to electricity supplies caused by renewed attacks on the country’s energy infrastructure.

    According to a statement cited by Ukrinform, further damage to power generation and transmission facilities has once again limited electricity availability at the company’s sites. Management has therefore decided to halt production and place part of the workforce on temporary leave until a stable and sufficient power supply can be secured.

    The suspension follows an earlier production stoppage announced on 8 November 2025, when Ferrexpo paused operations at the Yeristove and Poltava mining and processing plants in the Poltava region after similar power outages.

    The company confirmed that no employees were injured during the attacks and that its production assets were not physically damaged.

    Ferrexpo previously reported that iron ore output in 2025 declined by 9% year-on-year to 6.14 million tonnes.

  • Kazakhstan Embassy in Czech Republic deepens industrial cooperation with leading Czech companies

    Kazakhstan Embassy in Czech Republic deepens industrial cooperation with leading Czech companies

    Kazakhstan is stepping up efforts to strengthen industrial cooperation with the Czech Republic as part of its broader economic diplomacy agenda aimed at attracting foreign investment and advanced technologies.

    According to DKNews.kz, Kazakhstan’s Ambassador to the Czech Republic, Kairat Abdrakhmanov, has held a series of meetings with representatives of leading Czech industrial companies during his first official engagements with the country’s business community. The discussions involved major manufacturers including vehicle and machinery producers TATRA and ZETOR, mining equipment supplier FERRIT, industrial engineering firm ZVVZ Engineering, and glass industry equipment producer SKLOSTROJ.

    Czech business leaders expressed satisfaction with their existing partnerships in Kazakhstan and confirmed their interest in expanding cooperation. They were briefed on recent reforms aimed at improving Kazakhstan’s investment climate, introduced under the country’s ongoing modernization program led by President Kassym-Jomart Tokayev.

    The Czech side highlighted Kazakhstan’s continued attractiveness as a long-term industrial market, particularly for projects involving manufacturing, engineering, and technology transfer.

    Talks also focused on opportunities to localize production and establish joint manufacturing facilities in various regions of Kazakhstan. Kazakh diplomats were presented with updates on current projects and potential areas for deeper collaboration, with particular emphasis on advanced industrial and mining technologies designed to improve efficiency, operational reliability, and workplace safety.

    Following the meetings, the parties agreed to organize site visits to Czech production facilities, begin preparations for joint business forums, and maintain regular information exchanges on prospective investment and cooperation opportunities.

    Observers note that these engagements reinforce Kazakhstan–Czech industrial relations and lay the groundwork for new joint initiatives across manufacturing, technology, and investment sectors.

  • Poland’s central bank plans to boost gold reserves by 150 tonnes amid geopolitical risks

    Poland’s central bank plans to boost gold reserves by 150 tonnes amid geopolitical risks

    National Bank of Poland (NBP), the world’s largest reported buyer of gold, plans to increase its bullion holdings by a further 150 tonnes, lifting total reserves to 700 tonnes as it prepares for prolonged geopolitical instability.

    Management board member Artur Sobon told Bloomberg that the central bank recently approved the higher target, stressing that record-high gold prices would not deter purchases. Gold has surged to historic highs as investors seek safe havens amid rising tensions between the United States and Europe, including disputes over Greenland.

    “Our primary goal is to build an appropriate portfolio for these unstable geopolitical times, one that will guarantee Poland stability, security, and credibility,” Sobon said, adding that price considerations are secondary.

    At current market prices, acquiring 150 tonnes of gold would cost more than $23 billion. Central bank demand has been a major driver of gold’s rally, with prices doubling over the past 18 months. Buying accelerated globally after Russia’s reserves were frozen following its invasion of Ukraine, highlighting gold’s appeal as an asset that cannot be easily sanctioned.

    NBP purchased 100 tonnes of gold last year, the largest amount officially reported by any central bank. Analysts note that some countries, particularly China, may also be buying gold without fully disclosing their activity.

    Poland’s push to expand gold holdings has been led by central bank governor Adam Glapinski, with reserves standing at about 550 tonnes at the end of 2025. Until now, gold allocations were capped at 30% of total reserves, a threshold that soaring prices have brought close to being reached.

    Sobon said the timing and pace of future purchases would be determined by NBP traders and could vary month to month. Poland’s growing foreign-exchange reserves, bolstered by inflows of EU funds, give the country room to finance the expanded gold strategy. Total official reserves now stand at roughly $271 billion, compared with $36 billion when Poland joined the EU in 2004.

  • USA Rare Earth plans French metal and alloy plant alongside Carester oxide facility

    USA Rare Earth plans French metal and alloy plant alongside Carester oxide facility

    USA Rare Earth (Nasdaq: USAR), through its Less Common Metals (LCM) subsidiary, plans to build a rare earth metal and alloy production facility in France next to an oxide processing plant being developed by Carester.

    Carester is currently constructing a 1,600-tonne-per-year oxide processing facility in Lacq, with commissioning scheduled for late 2026. USA Rare Earth’s proposed plant, with a capacity of 3,750 tonnes per annum, will be co-located at the Caremag site, creating an integrated European platform for rare earth processing, metal and alloy production.

    The French government has committed to partially funding the project, including credits covering up to 45% of eligible equipment costs and support of up to €130 million for real estate, according to the company.

    Shares of USA Rare Earth jumped by double digits following the announcement, amid broader gains across the rare earth sector driven by rising geopolitical tensions between the United States and Europe over Greenland. By midday trading in New York, the company’s shares were around $20, valuing it at more than $2.7 billion.

    USAR CEO Barbara Humpton said the French development would strengthen the company’s integrated rare earth value chain and benefit the United States and its allies. In parallel, USA Rare Earth is advancing a domestic mine-to-magnet strategy in the US anchored by its Round Top project in Texas, alongside a magnet manufacturing plant in Oklahoma and processing facilities in Colorado.

  • Portugal awards €180m grant to Lifthium Energy for northern lithium refinery

    Portugal awards €180m grant to Lifthium Energy for northern lithium refinery

    Portuguese company Lifthium Energy has secured a €180 million ($210 million) non-refundable government grant to build a lithium refinery in northern Portugal, strengthening Europe’s push to localise electric vehicle battery supply chains.

    The funding was awarded under the European Union’s Temporary Crisis and Transition Framework, which allows member states to provide state aid to accelerate green and industrial transformation. Portugal, which holds around 60,000 metric tonnes of lithium reserves, is currently Europe’s largest lithium producer, though output has historically been directed mainly to the ceramics industry rather than battery applications.

    Lifthium, which is 85% owned by Portuguese conglomerate Jose de Mello with the remainder held by its subsidiary Bondalti, plans to construct the refinery in Estarreja, about 50 km south of Porto. Bondalti already operates chemical facilities in the area, providing existing industrial infrastructure for the project.

    The refinery is expected to begin operations by 2030 and is designed to produce up to 50,000 tonnes of lithium hydroxide per year, enough to supply batteries for around two million electric vehicles. Lifthium said the plant will use proprietary technology aligned with European environmental and industrial standards.

    Lifthium CEO Duarte Braga said the project was advancing cautiously amid a more challenging lithium market and tougher industrial conditions in Europe. He noted that while the public grant is significant, the company’s next priorities are securing a strategic partner and finalising market and financing arrangements before making a final investment decision.

    In addition to the Estarreja facility, Lifthium is also considering the construction of a second lithium refinery in Spain.

    The announcement comes as Portugal’s government prepares to launch a long-delayed tender for lithium prospecting licences, a move seen as critical to developing a domestic lithium value chain and reducing Europe’s reliance on imports, particularly from China.

  • Beyond Resources: How the UK–Kazakhstan Partnership Is Being Recalibrated

    Beyond Resources: How the UK–Kazakhstan Partnership Is Being Recalibrated

    Reflections from the FCDO Mining Roundtable and recent insights from Astana

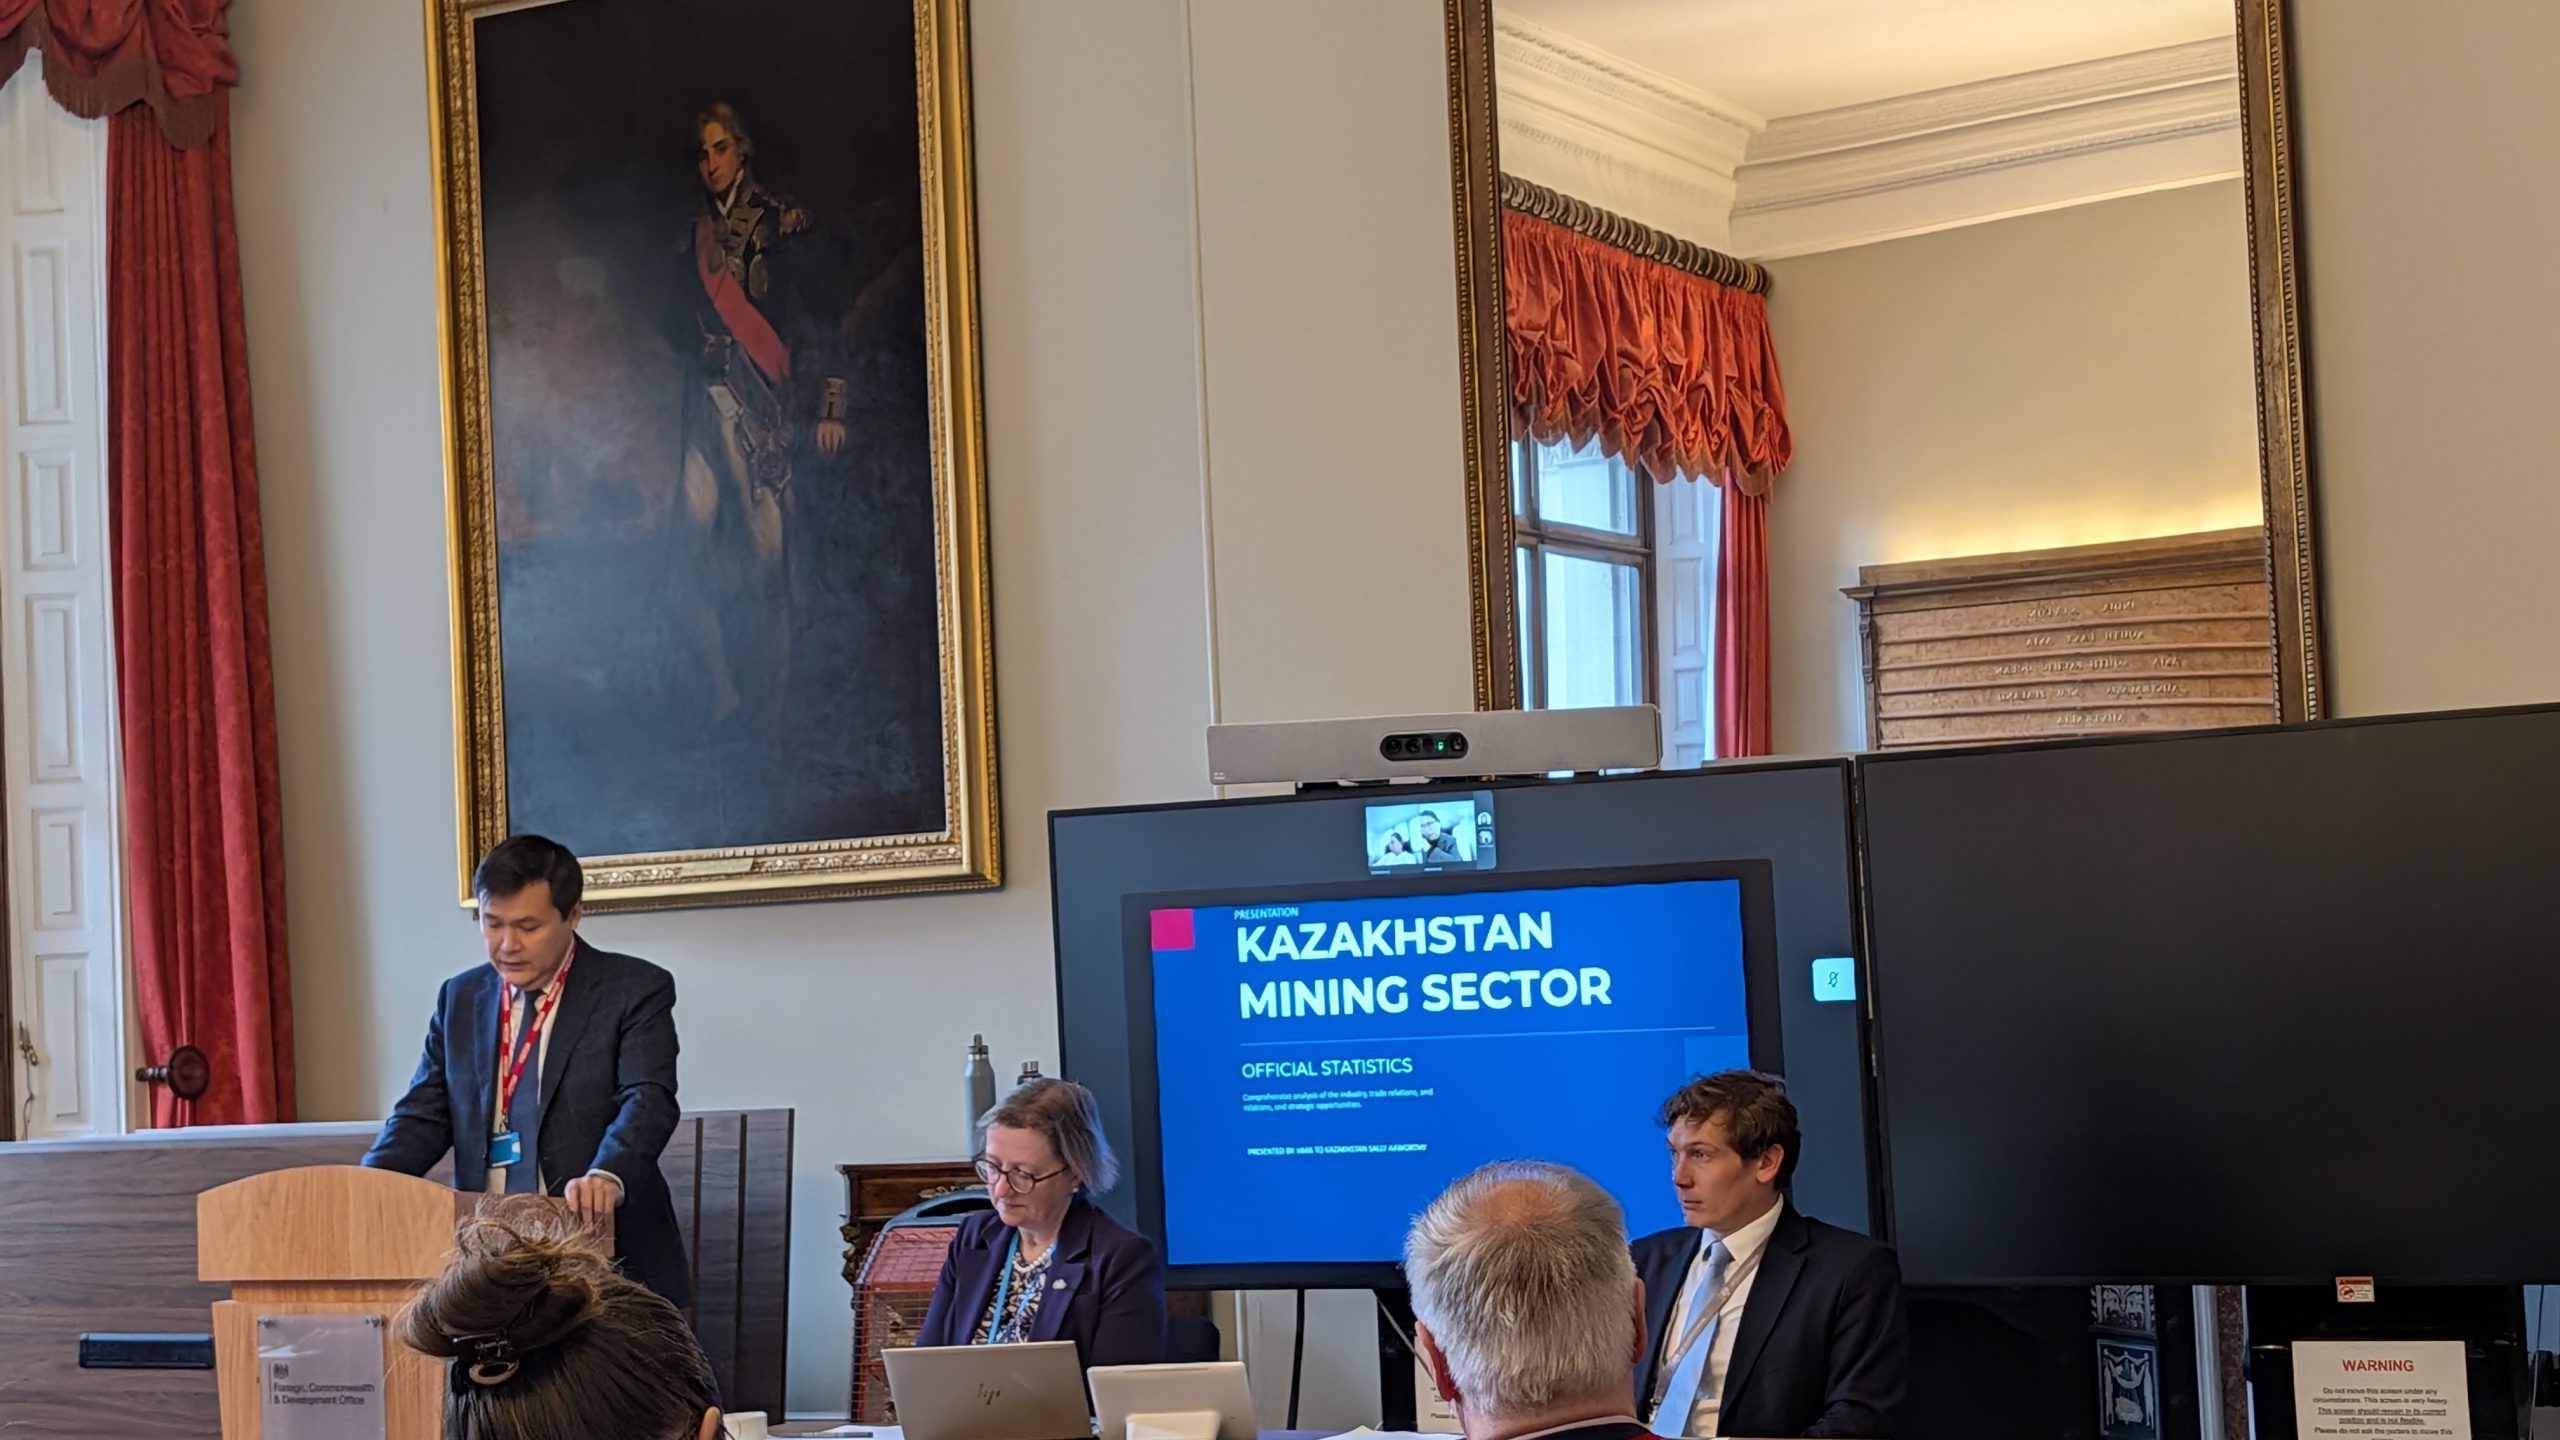
    “Beyond Resources.” That was the unspoken theme defining today’s discussions at the Foreign, Commonwealth & Development Office (FCDO) in London on 20 Jan. The question on the table was a trillion-dollar one: How does the UK secure the building blocks of its energy transition in an increasingly fractured world?

    The answer lies in the Central Asia’s steppes. But as the discussions revealed, the “frontier” days are over. Kazakhstan is no longer just a source of raw ore; it is rapidly becoming the strategic linchpin of the UK’s industrial future. From the race for rare earths to the rise of the “Middle Corridor,” here is an inside look at how the partnership is being recalibrated—and why 2026 marks the shift from potential to execution.

    Recalibrating the UK-Kazakhstan relationships in the critical raw materials race

    The UK-Kazakhstan relationship has undergone significant transformations since independence, with bilateral cooperation growing stronger every year. Critical minerals are a crucial aspect of this relationship, with the UK seeking to establish a reliable supply chain for technology and investment.

    The Mining reinforced a message that is becoming increasingly clear: the UK–Kazakhstan relationship is no longer defined solely by extraction, but by systems, standards, and shared strategic ambition.  it is evident that Kazakhstan has shifted from a “frontier market” to a strategic necessity for the UK’s energy transition. With 99 of the 118 periodic elements available in-country, Kazakhstan is the linchpin of the UK’s Critical Minerals Strategy. However, the UK faces an “execution gap” as China and the US deploy more aggressive, state-backed capital to secure off-take agreements.

    This broader recalibration was also powerfully articulated in a recent interview by The Astana Times with UK Ambassador to Kazakhstan, HMA Sally Axworthy, whose remarks provided important context for today’s discussion on mining and critical minerals.

    Taken together, the roundtable and the interview point to a partnership that is evolving well beyond resources.

    Current Market Landscape

    Kazakhstan’s “winning combination” of resource wealth and a modernizing regulatory framework (2018 Mining Code) is attracting unprecedented global interest.

    • Key Assets: 11% of global Titanium (Boeing/Airbus supply), 40% of global Uranium, and significant deposits of Rhenium, Beryllium, and Rare Earth Elements (REEs).
    • Legal Security: The Astana International Financial Centre (AIFC), operating under English Law, remains the primary vehicle for de-risking UK investment.

    Risks and Mitigations

    • Nationalisation Concerns: There is a trend toward increasing state control and preferential treatment for local investors.
      • Mitigation: Utilise AIFC protections and UK Export Finance (UKEF) to wrap projects in sovereign-level guarantees.
    • Supply Chain Diversification: Dependence on Chinese-controlled logistics remains a threat.
      • Mitigation: Invest in the “Middle Corridor” logistics nodes to ensure independent market access.

    From raw materials to value creation

    Kazakhstan’s extraordinary endowment of critical minerals — from uranium and chromium to vanadium, rhenium and rare earths — is well understood. What is changing is how Kazakhstan wants to participate in global value chains.

    As Ambassador Axworthy emphasised, Kazakhstan is seeking not only to supply raw materials, but to process, refine and add value domestically. This aligns closely with UK priorities under its Critical Minerals Strategy, which focuses on:

    • supply-chain resilience,
    • diversification away from single-country dependencies, and
    • embedding high environmental, social and governance standards.

    Concrete examples already exist. Joint ventures such as Maritime House with Zhezkazgan Redmet on rhenium recycling, supplying Rolls-Royce turbines, and Ferro-Alloy Resources’ vanadium project, expected to meet up to 10% of global demand, show how UK technology, finance and standards can combine with Kazakhstan’s resource base.

    These are not abstract ambitions — they are working models.

    The Competitive Challenge: Speed vs. Standards

    The UK is currently being outpaced in “time-to-market” by global rivals who offer more lucrative, less regulated entry paths.

    Competitor Strategy Competitive Advantage
    China “Infrastructure-for-Minerals” swaps. Speed: Immediate state-backed financing and dominant control of 70% of current exports.
    USA Geopolitical “Friend-shoring” via the Defence Production Act. Access: Massive capital injections to secure REEs and bypass Chinese processing hubs.
    United Kingdom Technical consultancy and ESG-led investment. Quality: High technical standards and legal transparency, but perceived as “slow” and “risk-averse.”


    Navigating Geopolitical Realities: Multivector Diplomacy

    Ambassador Axworthy reaffirmed that the UK views Kazakhstan as a strategic partner, not a zero-sum competitor:

    • Multivector Approach: Kazakhstan’s diplomatic flexibility (balancing ties with EU, China, and the US) ensures no single power dominates.
    • Alignment on Sovereignty & Multilateralism: Kazakhstan’s support for the UN, SDGs, and conflict resolution aligns with UK priorities.
    • Strategic Partnership Agreement (SPA): The UK’s SPA with Kazakhstan (currently being ratified) provides a legal framework for joint projects in energy, defence, and critical minerals.

    Key Challenges & Solutions:

    Challenge UK’s Strategic Response
    China’s Dominance in Critical Minerals UKEF’s guarantees and London’s financial hub position the UK as a competitive alternative.
    Talent Shortages UK universities (Durham, Birmingham) train Kazakh engineers for AI and automation.
    Regulatory Complexity EITI alignment and joint processing projects reduce risks.
    Competition from the US/EU First-mover advantage in SME funding and digital innovation.


    Finance, technology and standards as strategic enablers

    A key takeaway from today’s roundtable was that finance is as strategic as geology.

    UK Export Finance demonstrated how long-tenor, sovereign-backed guarantees can unlock projects across mining, processing and infrastructure, particularly where capital intensity and risk have historically slowed investment. This complements the UK’s strength as a global financial hub — including the role of the London Metals Exchange — highlighted by Ambassador Axworthy in Astana.

    Equally important is the role of technology and data. Several participants pointed to the need for:

    • digitalisation of legacy geological data,
    • AI-ready datasets,
    • Improved mine safety systems, and
    • Smarter, more sustainable operations.

    These are precisely the areas where UK firms — from engineering and digital mining to ESG advisory and geoscience — can play a decisive role.

    Skills, education and people-to-people ties

    One of the most candid discussions today centred on skills shortages, particularly engineers and geoscientists. This challenge is not unique to Kazakhstan — it is global — but it reinforces why education is such a critical pillar of the bilateral relationship.

    As outlined in The Astana Times, the UK’s educational footprint in Kazakhstan is expanding:

    • British universities including Cardiff, Coventry and De Montfort now operate campuses in-country.
    • Geological exploration and mining-related disciplines are part of this offer.
    • Nearly half of Bolashak scholars have studied in the UK, creating a deep reservoir of shared professional culture.

    Education, transparency initiatives such as the Extractive Industries Transparency Initiative, and English-law institutions like the Astana International Financial Centre are not peripheral — they are central to investor confidence.

    Partnership, not pressure, in a competitive landscape

    Kazakhstan sits at the crossroads of Europe and Asia, and competition for its critical minerals is intense. China, the EU, the US, Japan and Korea are all active.

    Yet a recurring theme — both today and in Ambassador Axworthy’s interview — was that this is not a zero-sum game.

    The UK’s approach is deliberately pragmatic:

    • partnership over pressure,
    • long-term engagement over transactional deals,
    • respect for Kazakhstan’s multivector foreign policy.

    As former UK Foreign Secretary David Cameron put it during his 2024 visit: the UK is not asking Kazakhstan to choose — but to partner for mutual security and prosperity.

    Beyond mining: a multidimensional relationship

    What makes the recalibration particularly compelling is that mining and critical minerals sit within a much wider ecosystem of cooperation:

    • Green startups and venture capital,
    • AI and digital innovation,
    • Architecture and urban development,
    • Culture, education and tourism.

    From British-designed landmarks in Astana and Almaty, to venture capital funds backing green and women-led startups, to growing cultural and academic exchanges, the relationship is increasingly people-driven.

    2026 Outlook: The Transition from “Quarry” to “Hub”

    Based on the strategic pillars discussed today, here is what the mining landscape in Kazakhstan will look like by 2026:

    1. The Value-Add Mandate

    By 2026, the era of simply exporting raw ore will be ending. The Kazakh government is pivoting toward in-country processing. We expect to see a surge in “Midstream” projects—refineries and metallurgical plants—where UK technology in chemical engineering and automation will be the primary currency of trade.

    1. Digitalisation and the “Green” Mine

    The 2026 mining code will likely reward “Smart Mines.” As Kazakhstan moves toward its 2060 Net Zero goals, British expertise in AI-driven geological mapping and carbon-neutral extraction will shift from “nice-to-have” to “license-to-operate.”

    1. The Middle Corridor Reality

    By 2026, the Trans-Caspian International Transport Route (TITR) will be the primary artery for critical minerals moving to Europe. UK firms in logistics, insurance, and port infrastructure will play a silent but vital role in ensuring these minerals reach the West without geopolitical interference.

    Final reflection

    Critical minerals may be the catalyst, but trust, standards, skills and shared ambition are the real foundations of the UK–Kazakhstan partnership.

    The “winning combination” mentioned by HMA Sally Axworthy—UK expertise and Kazakh resources—is powerful, but it is not guaranteed. To win in 2026, UK firms must match their technical excellence with a more aggressive commercial posture and faster capital deployment.

    Today’s FCDO roundtable made clear that the opportunity ahead is not simply about securing supply — it is about co-creating resilient, sustainable and technologically advanced value chains that serve both countries’ long-term interests.

    The minerals are there. The roadmap is signed. The challenge now is execution — and the momentum is clearly there.

    Continuing the conversation: MINEX Kazakhstan 2026

    The themes discussed at today’s roundtable—regulatory reform, multi‑vector foreign policy, critical mineral security, green transition, and technological modernisation—will continue at the MINEX Kazakhstan 2026: 16th Mining & Exploration Forum, taking place on 15–16 April 2026 in Astana.

    For those who are interested in the future of Kazakhstan’s mining and critical minerals sector—and in the broader UK–Kazakhstan partnership—this Forum will be an ideal platform to continue today’s discussion, share expertise, and shape the next wave of projects and collaborations.

    MINEX has long provided a platform where government, industry, investors, financiers and technology providers can engage in open, practical dialogue on the future of Kazakhstan’s mineral sector. For those involved in critical minerals, mining reform, processing, finance and downstream integration, it will be a timely opportunity to deepen discussions that are already well underway.

    🔗 https://2026.minexkazakhstan.com/
     

  • Sibanye-Stillwater completes assessment of Keliber lithium project, confirms staged start-up plan

    Sibanye-Stillwater completes assessment of Keliber lithium project, confirms staged start-up plan

    Sibanye-Stillwater has completed a multidisciplinary assessment of its Keliber lithium project in Finland, confirming the project’s technical readiness and outlining a staged approach to commissioning amid current market conditions.

    The Keliber project is regarded as the European Union’s most advanced fully integrated lithium development, with planned production of around 15,000 tonnes per year of battery-grade lithium hydroxide monohydrate over a mine life exceeding 18 years. It is also one of the few lithium hydroxide refineries outside China and has been designated a strategic project under the EU’s Critical Raw Materials Act, reflecting its importance to the bloc’s battery supply chain.

    According to Sibanye-Stillwater, construction of the fully integrated mine, concentrator and refinery remains on track, with completion of the construction phase and cold commissioning expected in the first quarter of 2026. The total capital investment required to complete construction is estimated at approximately €783 million.

    Following the assessment, Sibanye-Stillwater and its strategic partner, Finnish Minerals Group, have agreed that a staged start-up represents the most prudent path forward. Under this approach, initial commissioning will focus on achieving operational readiness at the mining and concentrating stages before determining the timing for commissioning the refinery.

    The company said this phased strategy is intended to reduce ramp-up risks while preserving financial flexibility, allowing certain capital expenditures and refining ramp-up costs to be deferred depending on lithium market conditions. Finnish Minerals Group is preparing to contribute additional funding on a pro rata basis in line with its 20% equity stake to support the project through the ramp-up period.

    Sibanye-Stillwater CEO Richard Stewart said the agreed approach balances technical readiness with market realities, ensuring the project advances in a responsible and commercially disciplined manner while remaining positioned to supply locally produced lithium into the EU battery value chain.