Poland, the Czech Republic, Slovakia and Hungary are each developing distinct approaches to Europe’s critical minerals challenge, but all four face the same structural limitation: the real competition for strategic value lies in processing, refining and advanced manufacturing — stages where China maintains decisive advantages and where none of the Visegrad countries has yet established a compelling position.
The urgency has sharpened since China tightened export controls on critical materials and permanent magnets in 2025, exposing Europe’s continued vulnerability across automotive manufacturing, wind energy and defence production. For the Visegrad Group, the question is whether Central Europe can move beyond its traditional role as a manufacturing base into the higher-value segments of emerging supply chains — a transition that will require more than attracting foreign factories.
Hungary has pursued investment attraction most aggressively, becoming one of Europe’s largest battery manufacturing hubs by drawing major Asian producers including CATL, Samsung, LG and SK On through subsidies and state support. The strategy has delivered factories and jobs, but critics argue that much of the value creation remains outside the Hungarian economy: foreign manufacturers operate within their own supply networks, limiting domestic integration into strategic parts of the battery value chain. Environmental controversies surrounding major projects have also fuelled local opposition.
The Czech Republic is centred on the Cínovec lithium deposit — designated as strategic under the EU’s Critical Raw Materials Act and planned to eventually support battery production for more than one million electric vehicles annually. But mining is not expected to begin until around 2030, and analysts warn that extraction alone will generate limited strategic benefit if downstream processing and recycling take place elsewhere. With one of Europe’s most important automotive sectors, Prague’s real challenge is building the industries that come after the mine.
Slovakia faces similar downstream concerns. Geological surveys suggest lithium and antimony resources exist, but Bratislava remains focused on deposit mapping and assessing potential secondary sources from historical mining sites. Slovak experts identify the absence of active cathode material producers as a critical gap. The country’s exclusion from the first wave of CRMA strategic projects has raised concerns about its ability to benefit from emerging European investment mechanisms without a more assertive industrial strategy.
Poland is taking an unconventional approach, treating mining waste as a critical minerals resource. Coal-bearing formations, spoil heaps and historical mining residues contain germanium, gallium, cobalt and certain rare earth elements that were long discarded. Warsaw has launched a national programme to identify and develop such secondary resources, and plans for a rare earth processing facility in Puławy could strengthen Poland’s position in European supply chains — an approach that reflects the EU’s growing emphasis on recycling and secondary materials alongside primary mining.
Despite differentiated strategies, a common structural weakness runs through all four countries. The European Court of Auditors recently warned that many CRMA objectives lack binding force and could be delayed by permitting procedures that routinely stretch for years — a gap between Brussels’ legislative ambition and on-the-ground implementation that affects Central Europe as much as any other region.
Serbia has opened a public consultation process for amendments to its Law on the Use of Renewable Energy Sources, seeking to align the legislation with European Union directives while meeting reform obligations necessary to access EU grants under the Growth Plan for the Western Balkans.
The Ministry of Mining and Energy is inviting written proposals and suggestions from interested parties until 7 July at oie@mre.gov.rs. The amendments aim to align Serbian legislation fully with the EU’s Renewable Energy Directive RED2 and partially with RED3, while also incorporating Serbia’s Integrated National Energy and Climate Plan and the country’s obligations under the EU Reform and Growth Facility’s reform agenda.
The proposed changes cover several key areas. On permitting, the amendments envision establishing contact points to guide applicants through approval procedures and streamlining permitting deadlines — addressing one of the most persistent barriers to renewable energy project development in the Western Balkans. A new framework for renewable acceleration areas would enable spatial and energy mapping to designate priority zones for renewable development through planning documents, with environmental protection rules maintained.
The guarantees of origin system would be expanded beyond electricity to cover renewable gases including biomethane and hydrogen, as well as energy for heating and cooling including waste heat. The incentive system for renewable electricity generation is to be strengthened around principles of transparency, competitiveness, non-discrimination and cost-effectiveness, with auctions aligned to power system stability needs and market price signals.
The legislation would also improve the regulatory framework for prosumers — formally termed buyers-producers in Serbian law — clarifying rights to generate for self-consumption, store electricity, use net billing for surpluses and sell excess output on the market. The amendments would address jointly acting prosumers in shared buildings and the role of third parties in ownership, management and maintenance of generation and storage facilities. The framework for renewable energy communities, including participation by households and local authorities, would also be upgraded.
District Metals has commenced diamond drilling at the Österkälen mineral licence in central Sweden, marking the company’s first drill programme specifically targeting Alum Shale mineralisation across its Swedish exploration portfolio.
The programme will test a MobileMT conductive anomaly identified in 2025 that extends approximately 8 kilometres in length and up to 3.5 kilometres in width. The geophysical feature coincides with geochemical soil anomalies interpreted as indicating favourable Alum Shale stratigraphy. The target area has not previously been tested by drilling.
District Metals CEO Garrett Ainsworth said the large dimensions of the anomaly are consistent with a district-scale target. “By integrating geophysical, geochemical and geological datasets, we have identified a high-priority target that has never been previously drill tested. This programme is designed to determine whether the Österkälen target hosts the characteristics of a Viken-style mineralised system while continuing to demonstrate the significant exploration upside across our Alum Shale properties,” he said.
The number of holes and total metres drilled will be guided by geological observations and uraniferous radiometric measurements collected during drilling. The Österkälen programme forms part of District Metals’ approved 2026 exploration budget, under which the company plans to drill approximately 5,000 to 7,000 metres across its Viken and Alum Shale properties during the year.
District Metals’ primary asset is the Viken property, which hosts what the company describes as the world’s largest undeveloped uranium mineral resource estimate.
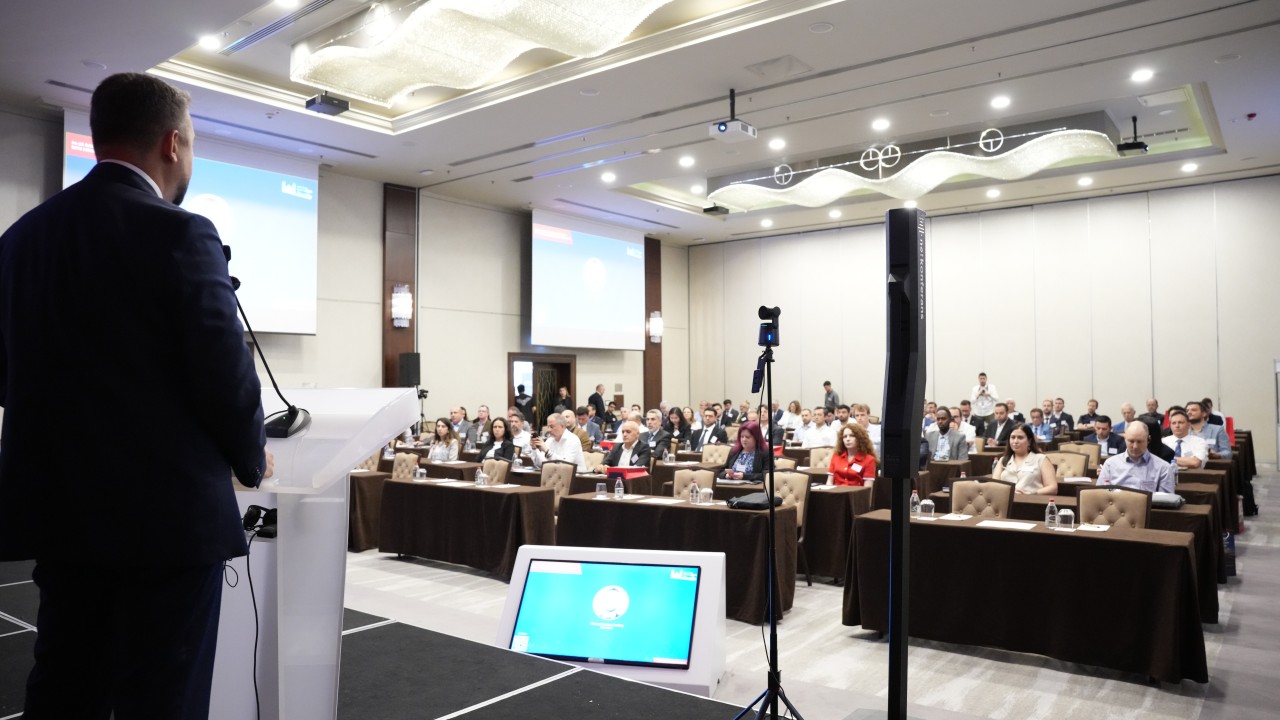
Over 140 delegates from 18 countries gathered at the MINEX Asia Forum in Ankara on Wednesday. The room was senior, the agenda substantive, and the conversation rarely left the strategic layer.
Why this moment matters: the demand imperative
Ibrahim Halil Kirsan TOBB Turkey Mining Council President, ÇIFTAY Board Member Mining Council, TOBB, ÇİFTAY
İbrahim Halil Kırşan, President of the TOBB Türkiye Mining Assembly, opened with the global frame and did not soften it. Drawing on IEA data, he put the stakes plainly: by 2040, mineral utilisation in renewable energy will increase four-fold under the Sustainable Development Scenario and six-fold under Net Zero. On a commodity-specific basis, lithium demand alone is projected to surge 42-fold under the SDS. Electric vehicles, wind turbines, defence systems, smartphones, fibre optic networks: the slide mapping how much metal goes into each clean energy technology was not background material. It was the case for why everyone in the room was in Ankara on a Wednesday morning. Ayhan Yüksel of the Chamber of Mining Engineers picked up the regulatory thread, tracing Türkiye’s mining legislation from the 1954 Mining Law through seven amendments to the 2025 revisions — a progression from state-dominated extraction toward an investment-oriented framework that nonetheless preserves strategic sovereign control over mineral assets.
Türkiye’s REE ambition: the numbers behind the claim
The most forensically detailed presentation of the morning came from Dr Hüseyin Çaldırak of TENMAK’s Rare Earth Elements Research Institute, and it moved the Beylikova story from political ambition to technical specificity.
Ayhan Yüksel of the Chamber of Mining Engineers
The deposit: 694 million tonnes of resource at approximately 2% NTE grade, containing an estimated 12.5 million tonnes of potential rare earth reserves — widely described as the world’s second-largest REE reserve after China’s Bayan Obo, with a planned full-scale facility targeting 570,000 tonnes of ore per year and projected annual revenues of approximately $220 million. China currently controls approximately 70% of world NTE production and over 90% of processing and magnet manufacturing capacity. Demand will grow more than 60% by 2030, with EV motors as the primary driver — REE demand from electric vehicle motors has risen from less than 1% of total magnet NTE demand in 2015 to 9% today, projected to reach approximately 18% by 2030. minexasia
The domestic arithmetic is striking. With a 2035 national energy target of 48GW of wind capacity from 15GW today, Türkiye will need approximately 3,461 tonnes of NTE just for its own wind turbine fleet. At 10,000 tonnes per year, Beylikova covers that domestic requirement entirely — and still exports. The Western response to Chinese dominance is correspondingly large: a $12 billion US DoD partnership with MP Materials, NdPr offtake agreements at a $110/kg floor price, and a US National Defense Industrial Strategy that from January 2027 will prohibit SmCo and NdFeB production involving China, Russia, Iran or North Korea at any stage. The technology gap for Türkiye remains real: China controls export licences for all products containing Chinese-origin REEs, and Beylikova’s separation technology is still under development. But the strategic window has rarely been wider.
The $13.5 trillion question: four countries, four trajectories
The invisible foundation: data, laboratories and bankability
Abdullah Buhur of ARGETEST made what might have seemed like a narrower technical argument — but it ran directly to the financing panel that followed. In modern mining, he argued, you must extract the data from the ore before you extract the ore itself. Incomplete or inaccurate geochemical and metallurgical data leads to wrong process designs and facilities that cannot operate. Reliable end-to-end data generation is what makes CRIRSCO, JORC and UMREK-compliant reporting possible — and compliant reporting is what makes a project financeable. ARGETEST, founded in Ankara in 2012 and now holding ISO/IEC 17025 ILAC accreditation, has already opened its first international laboratory in Tashkent, with three further countries in active planning. The message to Central Asian and Caucasus projects represented in the room: the laboratory infrastructure that underpins bankable feasibility studies is arriving regionally, not just in London or Perth.
The Tethyan Belt — geology mapped, execution pending
EBRD’s Deputy Head of Türkiye, Mehmet Uvez
EBRD’s Deputy Head of Türkiye, Mehmet Uvez, reframed the Middle Corridor precisely: not a transport route, but a platform for trade resilience and industrial value chains. The numbers behind the commitment: €24.4 billion in cumulative EBRD investment in Türkiye, a record €2.7 billion across 54 projects in 2025 alone, and up to €500 million in sovereign lending for the INRAIL Istanbul North Rail Crossing — a missing link for the Trans-Caspian route. The OECD presented EU-funded research on connectivity and CRM export potential across Central Asia. The USGS gave a frank country-by-country assessment: the region holds 39% of global manganese ore reserves, 31% of chromium, 20% of lead, and significant shares of zinc, titanium, copper and cobalt — the endowment is not in question; investability is. Discovery Alert
Simon Glancy of Strategic Solutions brought the most granular data of the session. Uzbekistan possesses over 29 types of rare and rare earth metals, but only copper and tungsten are being developed at scale, with UzTMK’s exports forecast to reach $80 million by 2030 — just 3% of total industry output. For nearly every strategic mineral in the region, Chinese investors are already the dominant or sole significant foreign presence. His core proposal — a Central Asian CRM alliance structured around hub processing facilities in Kazakhstan and Uzbekistan, with Kyrgyzstan, Tajikistan and Turkmenistan feeding in semi-processed material — was the most concrete regional architecture offered on the day.
Key takeaways:
The demand case is irrefutable: a 42-fold lithium surge and a 6-fold increase in total mineral use for renewables by 2040 under Net Zero are the operational context for every investment decision in this room
Beylikova’s significance rests not on reserve size alone but on arithmetic: at 10,000t/yr NTE, Türkiye covers its domestic wind energy mineral needs and becomes a net exporter to allies seeking diversification from China
Laboratory infrastructure — accredited, internationally recognised — is a prerequisite for bankability; its regional arrival is an enabling condition, not a detail
Turkish companies have a specific and underexploited opportunity as providers of engineering, processing technology, lab services and advisory capacity across the Central Asian CRM ecosystem
Who is funding the future — and how fast?
The financing session assembled the most concentrated group of development finance institutions seen at a MINEX event: EIB, EBRD, IFC, ADB, UKEF, KfW IPEX-Bank, the Türkiye Wealth Fund and BORG Capital Insights, moderated by Han Ilhan of Catalis Strategies. Hogan Lovells opened with the political risk framing: investment treaties, investor-state arbitration and export credit insurance are not bureaucratic formalities — they are the mechanism that makes Western private capital competitive with Chinese state finance. The ADB’s CMM Value Chains Initiative presented a holistic approach: diversified and resilient supply chains, domestic value addition, ESG standards as competitive advantage rather than compliance burden.
Han Ilhan, Co-Founder and Managing Director Catalis Strategies
Then came the baseline that set the terms for the panel’s candour. In 2023 alone, Chinese firms invested more than $120 billion in overseas mining and processing; China now controls approximately 60% of lithium processing, more than 70% of cobalt refining, and over 90% of battery material manufacturing. Against that, Western institutional capital’s pace and structural flexibility were scrutinised without diplomatic cover. The headline conclusion: the institutions are present, the mandates are real, the appetite exists — but speed, flexibility and first-loss willingness on frontier projects remain the decisive variables. Kazakhstan’s tungsten makes the point exactly: the country’s entire 2025 export volume — roughly 3,700 tonnes — went to a single destination: China. The mineral wealth is there. The offtake relationships are not. ENERPO JOURNALEast Asia Forum
Key takeaways:
Five multilateral development banks in one session signals intent; coordinated deployment, not just parallel presence, is the next requirement
Political risk instruments are the mechanism that makes Western private capital competitive with Chinese state finance on frontier projects
The US DoD’s $12bn MP Materials partnership and the 2027 prohibition on Chinese-stage REE production in defence supply chains mark the clearest shift yet from policy to procurement
Türkiye imported over 170 tonnes of gold in 2024 while producing just 32 tonnes domestically — a country with $3.5 trillion in reserves running a gold trade deficit is a measure of the distance between geological wealth and industrial policy China Population Density Map
The Turkish industrial offer
DAMA Engineering traced four decades of Turkish mining advancement — from Atatürk’s 1935 founding of MTA and Etibank on the same day, pairing geological discovery with production capacity, through the arrival of global majors following the 1985 Mining Law, to the UMREK reporting code and modern integrated processing plants. The arc: Türkiye absorbed international best practice and is now in a position to export that capability eastward along the Middle Corridor.
Devrim Aksu closed with the challenge that cuts across every projection of regional growth. Global talent shortages in geologists and mining engineers, scarce digital mining skills, the absence of remote operations workforce models at scale: her presentation put the question plainly — “Who Will Build the Workforce Behind the Critical Minerals Boom?” — and left it unanswered, because it is genuinely unanswered. Women remain a structurally underutilised reserve in mining talent pipelines across the region; the business case is now as compelling as the equity case.
The day’s through-line
If one argument ran through every session on Day 1, it was this: the strategic case for the Middle Corridor as a global critical minerals supply line is no longer being made — it is being assumed. The debate has moved to execution. Who finances, who processes, who certifies the data, who builds the workforce, and who captures the value — these are the questions that will define the next decade.
A jurisdiction that ranked 104th in global mining investment attractiveness a decade ago now sits in the global top ten — not because its geology changed, but because its framework did. Türkiye has more mineral wealth, a better geographic position, four decades of engineering capability, and direct access to European markets. Kazakhstan produces 38% of the world’s uranium and has the majors already in country. Uzbekistan has the momentum of a country that has been closed and is now opening fast. The room in Ankara on Wednesday contained many of the institutions that could unlock all three. Whether the urgency matches the opportunity is the question Day 2 will not answer either — but it will sharpen it.
The evening closed at the British Embassy, hosted by the Department for Business and Trade. Day 2 continues tomorrow.
President Kassym-Jomart Tokayev has proposed a new model of cooperation with the European Union in the mining and metallurgical sector, offering access to Kazakhstan’s rare and rare earth metals in exchange for European investment and technology transfer, at the Kazakhstan–EU Round Table in Brussels.
Tokayev highlighted that Kazakhstan’s subsoil users are already capable of supplying 21 of the 34 minerals on the European Union’s critical raw materials list, while significant untapped reserves of lithium, nickel, vanadium and cobalt remain undeveloped. He said the most effective mechanism for unlocking this resource potential would be offtake-based cooperation — arrangements under which buyers guarantee the purchase of a defined volume of future production — as this model would stimulate the development of rare metal ore processing and the production of higher value-added products.
Kazakhstan also renewed its proposal to establish a Regional Research Centre on Rare Earth Metals in Astana. The centre would provide prospective investors with current information about available deposits across Central Asia and the technologies available for their development.
The round table underscored Kazakhstan’s role as one of the EU’s key energy partners, with Kazakhstani crude oil’s share of the EU market growing to 13% in 2025. The event concluded with the signing of new commercial agreements with a combined value of nearly $1 billion.
Kazakhstan has signed a package of strategic agreements with leading Belgian universities and European innovation bodies during President Kassym-Jomart Tokayev’s official visit to Belgium, establishing new research partnerships in critical materials, sustainable metallurgy, artificial intelligence and computational engineering.
The most significant agreement brings together D. Serikbayev East Kazakhstan Technical University, KU Leuven and the SIM² KU Leuven Institute for Sustainable Metals and Minerals, along with Astana Hub. The partnership will enable Kazakhstani students, researchers and PhD candidates to collaborate with European scientists on critical materials science, sustainable metallurgy, industrial digitalisation and AI applications in manufacturing — a combination directly relevant to Kazakhstan’s strategic goal of developing value-added industries around its substantial critical raw material reserves rather than remaining a raw material exporter.
A separate agreement with Ghent University will establish a mirror research laboratory in Kazakhstan focused on mathematics, artificial intelligence, mathematical modelling and computational engineering. Based at the Alem.ai Foundation in Astana, the laboratory will support joint research, academic exchanges, scientific publications and international collaboration.
Meetings with the European Commission’s Directorate-General for Research and Innovation and the European Innovation Council also covered Kazakhstan’s further integration into Horizon Europe — the EU’s €93.5 billion flagship research and innovation programme — advancing the case that Science Minister Sayasat Nurbek has been making publicly for Kazakhstan to be treated as a research partner rather than simply a mineral supplier.
The agreements mark a concrete step in Kazakhstan’s broader effort to position itself as a trusted international partner in research, innovation and artificial intelligence, building institutional connections with European science alongside the diplomatic and commercial relationships being advanced through critical minerals dialogues.
The British government has announced £50 million in new funding to boost domestic critical minerals production across extraction, processing and recycling, as part of an accelerating effort to reduce dependence on concentrated global supply chains dominated by China.
The funding is structured across three pillars: £20 million for a rare earth magnet hub, £25 million for an accelerator programme to help scale projects, and up to £5 million for a platform to aggregate industry demand and unlock private investment. Industry Minister Chris McDonald launched the programme during a visit to a northeast England industrial research hub where companies are developing technologies for metal recovery and processing.
“Critical minerals are vital for our national security,” McDonald said. The announcement builds on more than £200 million already committed to the sector and is intended to secure materials used across a range of products from smartphones and electric vehicle batteries to domestic appliances.
The initiative comes as China retains dominant positions across global critical mineral supply chains, accounting for approximately 70% of rare earth mining and 90% of refining. Britain has been seeking to develop domestic capabilities while simultaneously diversifying supply through partnerships with allies including the United States and South Korea, focused on supply chain collaboration, processing capacity and investment flows.
Recent domestic progress includes the opening of Britain’s first commercial rare earth magnet plant in 25 years, operated by Mkango Resources’ HyProMag unit in Birmingham, which produces magnets for electric motors and other technologies using recycled materials — demonstrating the viability of circular economy approaches to critical mineral security.
Saudi Arabia has used the Gulf Vision 2026 Forum in Paris to showcase investment opportunities across its $2.5 trillion mineral resource base to French and European partners, as the Kingdom accelerates its push to establish mining as the third pillar of the national economy under Vision 2030.
Khalid Al-Mudaifer, Saudi Arabia’s vice minister of industry and mineral resources for mining affairs, presented the Kingdom’s economic transformation agenda and held bilateral meetings with French officials and representatives of major French mining and industrial companies. Discussions focused on strengthening cooperation in mining investment, technology transfer and joint ventures, with particular emphasis on mineral exploration, sustainable mining practices and expanding domestic mineral value chains.
Vision 2030 aims to unlock more than $2.5 trillion in mineral resources including gold, copper, zinc, phosphates, aluminium and rare earth elements, diversifying revenue sources while strengthening Saudi Arabia’s position in global supply chains. The pace of licensing is accelerating: the Kingdom issued 80 new mining licences in March 2026, more than double the 38 issued in February, reflecting the government’s intensified effort to open the sector to international investment.
Al-Mudaifer highlighted Saudi Arabia’s commitment to providing a favourable investment environment backed by modern legislation and financial incentives. He also pointed to the National Industrial Development and Logistics Programme, which integrates industry, mining, energy and logistics under a unified national strategy, as a vehicle for expanding industrial capabilities, strengthening local value chains and improving the global competitiveness of Saudi products.
The vice minister emphasised that Saudi ambitions extend beyond resource extraction toward integrated industrial value chains — a positioning consistent with the broader shift among mineral-rich nations seeking to capture processing and manufacturing value rather than exporting raw materials.
Uzbekistan’s Ministry of Mining Industry and Geology has held talks with Turkish industrial minerals company ESAN Eczacıbaşı to review ongoing cooperation and identify new investment opportunities, as Tashkent continues its drive to attract foreign capital and modernise its mining sector through regulatory reform and expanded geological exploration.
The meeting between Minister Bobir Islamov and ESAN Eczacıbaşı executives followed the fifth Tashkent International Investment Forum, where Uzbekistan showcased investment opportunities across mining, energy and infrastructure to international participants. The discussions covered Uzbekistan’s ongoing mining sector reforms, investor-friendly legislative measures introduced in recent years, and outcomes of the forum.
The parties reviewed the status of projects currently being implemented in Uzbekistan with ESAN Eczacıbaşı, discussed future development plans, and explored opportunities to deepen their strategic partnership. Both sides reaffirmed interest in expanding cooperation and advancing joint initiatives.
“Uzbekistan’s ongoing mining reforms, improved investment climate and the success of the 5th Tashkent International Investment Forum are creating new opportunities for international partnerships and long-term investment in the sector,” the ministry said.
ESAN Eczacıbaşı is one of Turkey’s leading industrial minerals and mining companies, active in the extraction, processing and international trade of minerals used in ceramics, glass, chemicals and related industries. The company has been expanding its international footprint through mining investments and strategic partnerships in recent years.
Uzbekistan’s Minister of Mining Industry and Geology Bobir Islamov has met with representatives of Japan’s Itochu Corporation to discuss expanding cooperation in mining and geological exploration, with a focus on attracting Japanese investment and advanced technologies to Uzbekistan’s growing minerals sector.
The meeting took place on the sidelines of the fifth Tashkent International Investment Forum and was attended by officials from the Ministry of Mining Industry and Geology and state-owned uranium producer Navoiyuran. The parties reviewed opportunities to advance prospective joint projects and strengthen investment flows into Uzbekistan’s mineral resources sector.
Itochu is one of Japan’s largest general trading companies, operating across metals and minerals, energy, machinery, chemicals, food and infrastructure in more than 60 countries. The corporation already has a footprint in Uzbekistan’s uranium sector through a joint uranium enterprise in Navoi involving Navoiyuran, making the meeting a natural extension of an existing commercial relationship.
The discussions reflect Uzbekistan’s broader strategy of attracting foreign capital and technological expertise to develop its substantial mineral endowment — including uranium, gold, copper and a growing portfolio of critical minerals — as the country seeks to move beyond raw material extraction toward value-added industrial production. Japan’s interest in Central Asian minerals is driven by structural necessity: the country is entirely dependent on mineral imports and has been systematically diversifying supply chains away from Chinese dominance through government-backed engagement across the region.