Website: Europe.com

  • U.S.-Russia Negotiations and Global Commodity Markets

    U.S.-Russia Negotiations and Global Commodity Markets

    As the United States and Russia engage in negotiations to resolve the ongoing conflict in Ukraine, discussions are intensifying around the reintegration of Russian commodities into the global market. Despite Western sanctions imposed following Russia’s 2022 invasion of Ukraine, Russian exports of vital resources such as oil, gas, and metals have persisted, often finding alternative pathways to international buyers.

    Recent diplomatic efforts signal a potential shift in the geopolitical landscape. In mid-February 2025, U.S. Secretary of State Marco Rubio and Russian Foreign Minister Sergey Lavrov convened in Riyadh, Saudi Arabia, to explore avenues for ending the Ukraine war and improving bilateral relations. These talks, notably excluding Ukrainian representatives, have raised concerns among European allies about the future of sanctions and the potential resurgence of Russian commodities in Western markets. Associated Press

    Russian President Vladimir Putin has proactively proposed economic collaborations, offering U.S. companies joint ventures in rare earth metals and aluminum production. This initiative aims to leverage Russia’s substantial natural resources to attract Western investment and technology, potentially reshaping global supply chains that have been disrupted by the conflict and ensuing sanctions. Reuters

    Despite sanctions, Russia has maintained its role as a key energy supplier. Reports indicate that the European Union’s expenditure on Russian oil and gas in the third year of the war exceeded its financial aid to Ukraine, underscoring the complexities of energy dependence and economic interests. The Guardian

    The Organisation of the Petroleum Exporting Countries and its allies (OPEC+) face strategic decisions regarding production levels. With ongoing negotiations and the possibility of lifting sanctions, the group must balance market stability with member interests, particularly as non-member producers, like the United States, expand their market share. Reuters

    As diplomatic dialogues progress, the global commodities market remains in a state of anticipation. The potential reintegration of Russian resources poses significant implications for energy prices, supply chains, and geopolitical alliances. Stakeholders worldwide are closely monitoring these developments, recognizing that the resolution of the Ukraine conflict could herald a new era in international trade and energy dynamics.

  • The Rare Earth Myth: Unpacking Ukraine’s Mineral Wealth and Geopolitical Hype

    The Rare Earth Myth: Unpacking Ukraine’s Mineral Wealth and Geopolitical Hype

    [vc_row type=”in_container” full_screen_row_position=”middle” column_margin=”default” column_direction=”default” column_direction_tablet=”default” column_direction_phone=”default” scene_position=”center” text_color=”dark” text_align=”left” row_border_radius=”none” row_border_radius_applies=”bg” overflow=”visible” overlay_strength=”0.3″ gradient_direction=”left_to_right” shape_divider_position=”bottom” bg_image_animation=”none”][vc_column column_padding=”no-extra-padding” column_padding_tablet=”inherit” column_padding_phone=”inherit” column_padding_position=”all” column_element_direction_desktop=”default” column_element_spacing=”default” desktop_text_alignment=”default” tablet_text_alignment=”default” phone_text_alignment=”default” background_color_opacity=”1″ background_hover_color_opacity=”1″ column_backdrop_filter=”none” column_shadow=”none” column_border_radius=”none” column_link_target=”_self” column_position=”default” gradient_direction=”left_to_right” overlay_strength=”0.3″ width=”1/1″ tablet_width_inherit=”default” animation_type=”default” bg_image_animation=”none” border_type=”simple” column_border_width=”none” column_border_style=”solid”][vc_column_text text_direction=”default”]

    In the shadow of escalating geopolitical tensions, a narrative has emerged that Ukraine—a nation battered by war and economic instability—sits atop trillions of dollars’ worth of rare earth metals (REMs). This tantalising claim has captured the attention of policymakers, investors, and media outlets alike. But as with many stories born out of crisis, the truth is far more nuanced—and far less sensational—than it appears.

    At the heart of this tale is a proposed $500 billion deal between the White House and Ukrainian President Volodymyr Zelenskyy, aimed at tapping into Ukraine’s purported mineral wealth. The problem? Ukraine doesn’t have any rare earth metals to speak of. What it does have are strategically important minerals like lithium, graphite, titanium, and copper—resources critical for modern technology but not nearly as valuable or transformative as REMs.

    This distinction matters—not just for Ukraine’s economic future but also for global supply chains, energy security, and the geopolitical balance of power. To understand why, we must delve into the science, economics, and politics behind these materials, separating fact from fiction in what could be one of the most misunderstood narratives of our time.

    What Are Rare Earth Metals, Really?

    Rare earth metals (REMs) are a group of 17 elements on the periodic table, including the 15 lanthanides plus scandium and yttrium. Despite their name, most REMs are not particularly rare in the Earth’s crust; rather, they are difficult to extract and refine economically due to their geological dispersion. These elements play an outsised role in modern technology, enabling everything from smartphones and electric vehicles to wind turbines and advanced military systems.

    Their importance lies in their unique chemical properties. When combined with other materials, REMs create alloys and compounds with extraordinary conductivity, magnetism, and durability. For example, neodymium is essential for manufacturing powerful permanent magnets used in wind turbines and electric motors, while dysprosium improves the heat resistance of those same magnets.

    But here’s the rub: despite their critical applications, the total annual value of global REM production hovers around $15 billion—less than the revenue generated by two days of global oil output. While indispensable, REMs are not the golden ticket some imagine them to be.

    Ukraine’s Real Mineral Wealth

    So if Ukraine doesn’t have REMs, what does it have? Quite a bit, actually—but none of it qualifies as “rare earth.” Instead, Ukraine boasts significant reserves of strategically important minerals that are vital for clean energy, electronics, and defense industries. Among these are:

    • Lithium: Often referred to as “white gold,” lithium is crucial for producing high-capacity batteries used in electric vehicles (EVs) and renewable energy storage. Ukraine holds Europe’s largest lithium deposits, estimated at 12–14 million tonnes of lithium carbonate equivalent. However, these resources remain largely untapped. As of 2024, Ukraine produces no lithium and exports nothing. Even if fully exploited, current reserves would be worth between $10 billion and $12.5 billion—not even close to the $500 billion figure touted by U.S. officials.
    • Graphite: Another key component in EV batteries, graphite is also used in fuel cells, lubricants, and industrial applications. Ukraine has substantial graphite reserves, though production has plummeted amid ongoing conflict. In 2024, the country exported just 2,870 tonnes of graphite, worth less than $7 million.
    • Titanium: Ukraine holds a substantial portion of the world’s titanium reserves, crucial minerals like ilmenite and rutile used in high-tech sectors like aerospace, defense, and medicine. Representing about 7% of global reserves and the largest in Europe, these deposits theoretically hold a value of $421 billion. A significant portion of these reserves is located in areas under Russian control or contested, severely hindering extraction. This disruption is reflected in a 37% year-on-year drop in Ukraine’s 2024 titanium concentrate exports, resulting in a mere $11.6 million in revenue. To truly capitalise on its resources and compete with Russia, a long-established producer of titanium sponge, Ukraine must invest in its own sponge production capabilities.
    • Uranium: With 107,200 tonnes of identified uranium reserves, Ukraine ranks among the top global producers of this nuclear fuel source. However, the country lacks refining capacity, leaving it dependent on external processors—chiefly Russia—for enrichment.
    • Cobalt and Nickel: Essential for battery production, Ukraine’s cobalt and nickel reserves are modest but noteworthy. Collectively valued at $3.6 billion, these deposits pale in comparison to those of major producers like the Democratic Republic of Congo and Indonesia.
    • Copper: A cornerstone of electrical wiring and electronics, copper adds depth to Ukraine’s mineral portfolio. Though estimates suggest Ukraine possesses the fourth-largest reserves in Europe, actual production remains nonexistent. Precise figures for Ukraine’s copper reserves are not available, but Poland’s reserves are valued at $340 billion. Ukraine’s reserves are estimated to be a fraction of that amount.

    While these resources are undoubtedly valuable, they do not approach the scale or significance of true REMs. Nor do they justify the astronomical valuations being bandied about in Washington and Brussels.

    The Origins of the Misunderstanding

    How did such a fundamental error gain traction? According to Bloomberg Opinion columnist Javier Blas, the confusion stems from a report published by the NATO Energy Security Centre of Excellence in Lithuania. Titled provocatively, the document lists minerals like titanium, lithium, and uranium alongside genuine REMs, conflating the two categories entirely.

    “What Ukraine has is scorched earth; what it doesn’t have is rare earths. Surprisingly, many people – not least, US President Donald Trump – seem convinced the country has a rich mineral endowment. It’s a folly,” Blas wrote.

    This misclassification has been compounded by political rhetoric. Senator Lindsey Graham, a vocal advocate for the minerals deal, recently claimed that Ukraine possesses $2–7 trillion worth of rare earth minerals. Such hyperbole ignores both the scientific reality and the logistical challenges of mining and processing these resources.

    Even Donald Trump, never one to shy away from grandiose claims, has jumped on the bandwagon. On 3 February 2025, he declared that Ukraine has “very valuable rare earths,” echoing Graham’s assertions without evidence.

    Geopolitics and Supply Chains

    Beyond Ukraine’s borders, the stakes are higher still. China currently dominates global REM production, controlling roughly 80% of the market. Its dominance extends beyond raw materials to include refining and processing capabilities, giving Beijing immense leverage over industries reliant on these metals.

    Russia, too, plays a pivotal role in the supply chain for certain strategic minerals, particularly uranium. By investing heavily in refining infrastructure, Moscow has positioned itself as a key player in the nuclear energy sector.

    For Western nations, this concentration of supply represents a vulnerability—one that has only grown more acute amid rising tensions with Beijing and Moscow. Efforts to diversify sources of critical minerals have thus become a priority, with Ukraine viewed as a potential alternative supplier.

    But achieving this goal will require massive investment in exploration, extraction, and processing facilities—none of which Ukraine currently possesses. Without tens of billions of dollars in funding, turning Ukraine’s mineral potential into reality remains a distant dream.

    Separating Hype from Hope

    Ukraine’s mineral wealth is real, but it is neither as vast nor as transformative as recent headlines suggest. While the country holds promising reserves of lithium, graphite, titanium, and other strategically important minerals, these resources cannot fill the void left by China’s stranglehold on REMs.

    Moreover, the path to monetising Ukraine’s mineral assets is fraught with obstacles. From securing financing to navigating geopolitical minefields, the challenges are immense. Investors willing to take the plunge may find themselves waiting years—or even decades—for returns.

    As the world grapples with the realities of resource scarcity and shifting alliances, clarity is paramount. Misunderstandings like the one surrounding Ukraine’s so-called rare earth metals risk diverting attention and resources away from more pressing issues.

    In the end, Ukraine’s mineral story is not one of untold riches waiting to be unearthed—but rather of cautious optimism tempered by hard truths. It is a reminder that in geopolitics, as in geology, appearances can be deceiving.[/vc_column_text][/vc_column][/vc_row]
  • Zelenskiy Freezes US Mineral Deal, Seeks Middle Eastern Investors

    Zelenskiy Freezes US Mineral Deal, Seeks Middle Eastern Investors

    Ukrainian President Volodymyr Zelenskiy has suspended a proposed deal to exploit Ukraine’s vast mineral resources, estimated to be worth trillions of dollars, after the US provided little in return. Zelenskiy is now seeking new investors in the Middle East.

    The agreement, reached with US Treasury Secretary Scott Bessent last week, remains unsigned as it “does not adequately protect the country’s interests,” according to Zelenskiy. US President Donald Trump demanded access to $500 billion worth of Ukrainian minerals as compensation for US support during the three-year war, but failed to offer the crucial security guarantees Zelenskiy seeks in any deal.

    Zelenskiy insists that any minerals agreement must include not only subsoil resources but also security guarantees and foreign investment in Ukraine, all legally formalized. However, it is increasingly apparent that none of Ukraine’s allies are willing to provide a genuine security deal.

    The relationship between Zelenskiy and Trump has deteriorated, particularly after the US announced Europe’s exclusion from Ukraine ceasefire talks that began in Riyadh on February 18. Retired Lieutenant General Keith Kellogg, special envoy to Ukraine, had stated Ukraine would be at the table, but no Ukrainian representatives were present when Russian Foreign Minister Sergei Lavrov started talks with US Secretary of State Marco Rubio.

    In light of these developments, Zelenskiy has turned to the Middle East for new partnerships. During a visit to the UAE, he announced the signing of a bilateral trade agreement, the first of its kind between Ukraine and a Gulf nation. The agreement opens the UAE market to almost all Ukrainian goods and is expected to boost Ukraine’s GDP growth.

    Zelenskiy was scheduled to visit Saudi Arabia but canceled his plans as President Trump began US-Russia bilateral negotiations in Riyadh aimed at stopping Russia’s war against Ukraine. Prior to this, a Ukrainian delegation had already started discussions with Saudi Arabian entrepreneurs, presenting investment opportunities worth $500 million in various sectors including energy, agriculture, and infrastructure.

    As negotiations continue, the value of Ukraine’s mineral deposits has been estimated at up to $11.5 trillion, including significant reserves of critical minerals such as lithium and titanium. The outcome of these discussions could have significant implications for Ukraine’s economic future and its relationships with global powers.

  • UK Expertise Sparks a Sustainable Mining Revolution Across Europe and Central Asia

    UK Expertise Sparks a Sustainable Mining Revolution Across Europe and Central Asia

    According to the document “UK Capabilities in Mining for Critical Minerals – Industry Case Studies” recently published by the Department for Business and Trade, UK expertise is powering a new wave of mining innovation across Europe and Central Asia, according to a recent industry case study slide pack. The document highlights how British companies are leveraging cutting‐edge technology and sustainable practices to transform mining operations on two continents.

    In Kazakhstan, Central Asia Metals (CAML) is at the forefront. At its Kounrad operation, CAML has installed a 4.77MW solar power plant that now meets up to 18% of the site’s energy demand. This renewable solution not only cuts down on emissions but also underpins the company’s long-term commitment to sustainability. Meanwhile, at its Sasa mine in North Macedonia, CAML is pioneering paste fill mining methods designed to drastically reduce reliance on surface water, marking a significant step towards more sustainable resource extraction.

    Over in Europe, the Vareš Polymetallic Project in Bosnia and Herzegovina is making headlines as the first new mine to open in the region in over a decade. Spearheaded by Adriatic Metals and supported by Wardell Armstrong International, the project showcases how integrated technical expertise—from metallurgical testing to comprehensive ESG assessments—can drive both economic growth and environmental responsibility.

    These case studies underscore the global reach of UK mining capabilities. From renewable energy integration to innovative water management and robust environmental frameworks, British-led solutions are setting a new standard for mining in Europe and Central Asia. As the demand for critical minerals continues to rise, these pioneering projects offer a blueprint for sustainable development that could well shape the future of the industry.

  • Central Asia Mining: Shifting Investment Landscape

    Central Asia Mining: Shifting Investment Landscape

    Central Asia’s mining sector—long a linchpin of the region’s resource-based economy—is at a transformative juncture. A study published on 19 February 2025 by the Eurasian Development Bank (EDB) examining mutual direct investments (MDI) across the Eurasian region from 2016 to the first half of 2024 reveals an evolving investment landscape. Traditionally dominated by investments in extractive industries, the region is now witnessing a broad diversification into sectors such as manufacturing, power, and greenfield projects. Alongside these trends, emerging regulatory frameworks—most notably new Chinese legislation concerning post-mining reconciliation and ESG (Environmental, Social, and Governance) requirements—are poised to significantly influence future investment dynamics.

    Historical Pillar: The Dominance of Extractive Industries

    For decades, mining and the broader extractive industries have formed the backbone of economic development in Central Asia. Rich deposits of minerals and metals have attracted substantial international investment, particularly from China, whose longstanding focus on extractive projects translated into investments of $36.2 billion. This capital influx has been instrumental in developing the region’s infrastructure and export capabilities, cementing mining’s role as a critical driver of economic progress.

    A Shifting Investment Landscape

    While the total MDI stock in the Eurasian region reached $90.4 billion by mid-2024, the extractive sector’s share of investment has begun to contract. Once accounting for 65.4% of the investment portfolio in 2020, its share has decreased to 55% of a $50 billion stock. This trend is less a sign of waning interest in mining and more indicative of a broader reallocation of capital as investors seek opportunities in the new and adjacent sectors.

    Diversification: From Mines to Manufacturing and Power

    The diversification of investments in Central Asia is underscored by significant growth in the manufacturing and energy sectors. Chinese investments, traditionally concentrated in extractive industries, are increasingly flowing into power and manufacturing. For example, investment in the power sector surged to $4.1 billion—a 2.1-fold increase in just a year and a half—primarily in Uzbekistan, while the manufacturing sector attracted $11.8 billion. This capital reallocation suggests that investors are now betting on a more diversified economic future that balances resource extraction with value-added industries.

    Regional Dynamics and the Role of New Partners

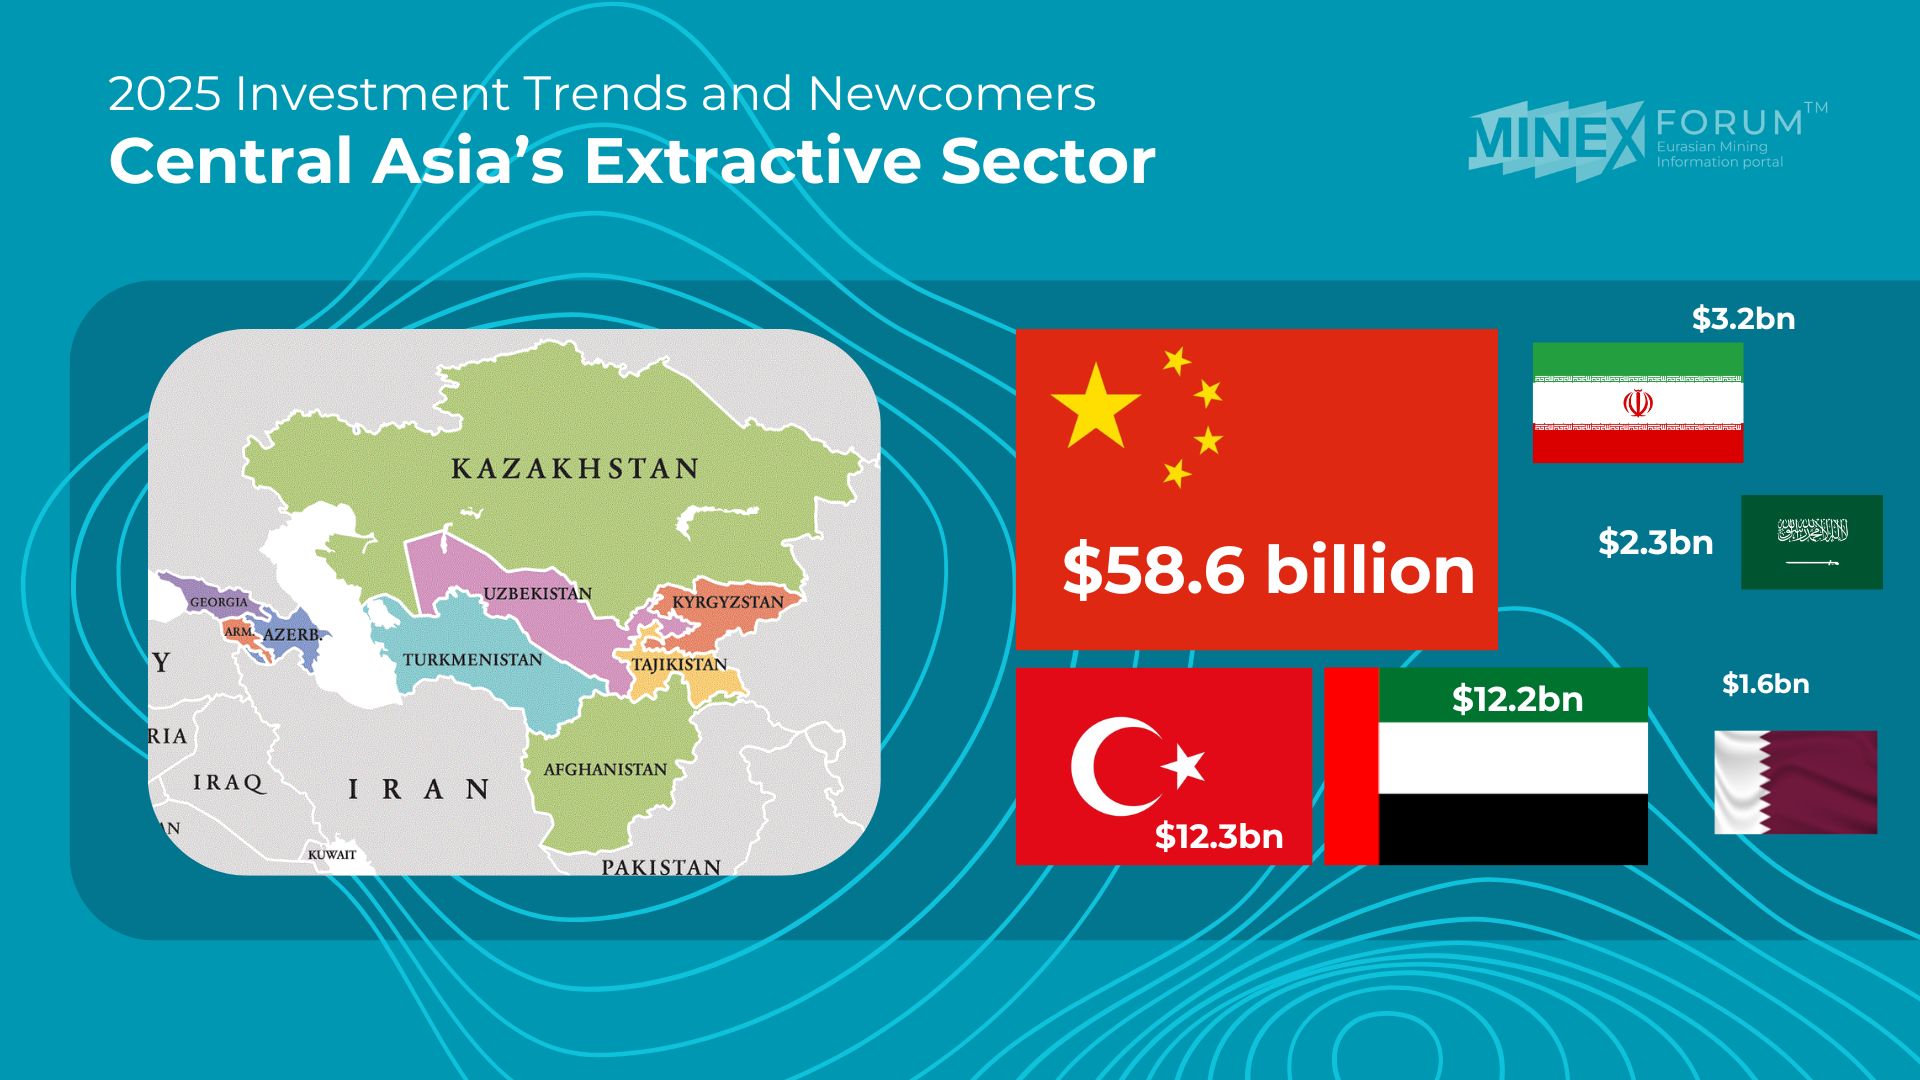
    Central Asia’s investment ecosystem is undergoing a fundamental reshaping, influenced not only by traditional players like China but also by new entrants from Türkiye, the Gulf states, and Iran. China remains the largest investor with an MDI stock of $58.6 billion, yet its strategy is evolving from a heavy reliance on extractive projects to a broader portfolio that includes energy, processing and manufacturing. Emerging investments from Saudi Arabia, UAE, Qatar, and Türkiye further illustrate the region’s expanding appeal. This diversification not only mirrors geopolitical shifts but also signals a recalibration of global investors’ risk and reward strategies in an increasingly competitive market.

    Emerging Regulatory Frameworks: China’s Revised Mineral Resources Law

    Adding a new dimension to the evolving investment landscape, recent Chinese legislative reforms are reshaping how mining investments will be planned and executed. According to a report by ICLG law firm, China has revised its Mineral Resources Law (effective from 1 July 2025) to include robust post-mining reconciliation requirements. These new provisions mandate that mining companies develop comprehensive ecological restoration plans once extraction activities cease. Such measures are designed to enforce ESG principles across the industry, ensuring that environmental sustainability and community welfare are prioritised alongside economic gains.

    While the law represents a significant step towards more sustainable mining practices, critics have noted that it lacks clear standards and robust community engagement provisions. The ambiguity surrounding enforcement may challenge the law’s effectiveness in practice. Nevertheless, as Chinese companies are pivotal players in Central Asia’s mining sector, these regulatory changes are expected to have far-reaching implications. By requiring adherence to ESG standards and post-mining reconciliation, the revised law not only elevates environmental and social accountability but also enhances the long-term viability of Chinese investments in the region.

    For Chinese investors, the new legal framework serves as both a challenge and an opportunity. On one hand, increased compliance costs and uncertainty in implementation could complicate investment decisions. On the other, the mandate for sustainable practices is likely to build greater investor confidence among international stakeholders who are increasingly attuned to environmental and social governance criteria. In effect, these reforms could catalyse further Chinese investments in Central Asia by promoting responsible mining practices that align with global trends toward sustainability.

    Greenfield Projects and the Future of Mining in Central Asia

    The momentum of greenfield projects further underscores the region’s dynamic evolution. With investments in new business and infrastructure soaring to $57 billion—almost double the levels of 2016—the emphasis is on modern, sustainable projects that integrate advanced technologies and greener practices. Even as capital shifts towards manufacturing and energy, the mining sector is adapting by incorporating sustainable practices and innovative technologies. This approach not only mitigates the historical environmental impact of mining but also positions the sector as a leader in sustainable resource management.

    Navigating the Future: Challenges and Opportunities

    Central Asia’s mining sector now stands at a crossroads. While traditional extractive investments continue to underpin the region’s economic strength, the emerging trends towards diversification and sustainability present both challenges and opportunities. Investors are increasingly weighing the volatility inherent in commodity markets against the more stable returns offered by sectors such as energy and manufacturing. Moreover, the integration of ESG principles—fuelled by legislative changes like China’s revised Mineral Resources Law among others—introduces a new layer of complexity, urging mining companies to innovate and adapt.

    Technological advancements, ranging from automation to environmentally friendly extraction techniques, hold the promise of revitalising the mining sector. These innovations, in tandem with the new regulatory environment, could help balance economic imperatives with ecological and community well-being. The successful navigation of these changes will be critical in ensuring that Central Asia’s natural resouces wealth continue to drive sustainable and long-term growth.


    Don’t miss the opportunity to explore Kazakhstan’s vast mineral wealth and connect with decision-makers shaping the future of mining in Central Asia at MINEX Kazakhstan Forum.

    MINEX Kazakhstan 2025 will feature:

    • 100+ expert speakers
    • 450+ delegates from 30+ countries
    • 50+ exhibitors showcasing cutting-edge technologies
    • Networking opportunities with key industry stakeholders

    Register here to secure your place at the Forum.

    We look forward to welcoming you in Astana!

  • Savannah Resources to Resume Drilling at Barroso Lithium Project After Suspension Lifted

    Savannah Resources to Resume Drilling at Barroso Lithium Project After Suspension Lifted

    Savannah Resources (LON: SAV) will immediately restart fieldwork and drilling at its Barroso lithium project in Portugal after the government lifted a temporary suspension order.

    The British company had paused work earlier this month following a precautionary injunction filed by landowners challenging the government’s approval for Savannah to access land it does not own. However, authorities issued a “reasoned resolution” stating that delays would be costly and harmful to the public interest, according to Savannah’s statement.

    Despite the news, Savannah’s stock fell 1.02% to £4.36 per share in London on Friday, giving the company a £95 million ($120 million) market capitalization.

    Barroso’s spodumene deposit is Europe’s largest, with recent prospecting results indicating it could exceed the previously estimated 28 million tonnes of high-grade lithium. However, the project has faced strong local opposition, including protests, legal battles, and refusals to sell land. Approximately 24% of the required land is privately owned, while 75% consists of common land (“baldios”).

    First Lithium Output in 2027

    Savannah aims to build four open-pit mines to supply lithium for 500,000 to 1 million electric vehicle batteries annually. The company is targeting first production by 2027.

    Once operational, Barroso is expected to produce 1.5 million tonnes annually over a 14-year mine life, based on a 20.5-million-tonne resource at 1.05% lithium oxide.

  • Russian Stocks Surge as Speculators Bet on Trump Easing Sanctions

    Russian Stocks Surge as Speculators Bet on Trump Easing Sanctions

    Shares of United Co. Rusal International PJSC—one of the few Russian companies still traded on major global exchanges—saw a 15-fold surge in trading activity this week, as investors speculated that Donald Trump might seek to ease sanctions on Russia.

    Trading volume in Hong Kong jumped to an average of 4.2 million shares per day, compared to just 250,000 in January, reflecting renewed interest in Russian assets. Rusal’s stock price has surged nearly 50% this month, reaching levels last seen in April 2022, shortly after Russia’s invasion of Ukraine.

    “Trump looks hell-bent on getting back in business with Russia,” said Kamil Dimmich, partner at North of South Capital. However, he noted that his firm does not invest in Russian stocks.

    Despite Rusal’s stock rally, the company still faces significant trade barriers. The US has a 200% tariff on Russian aluminum imports, while the EU is moving toward a full ban. The London Metal Exchange no longer accepts newly produced Russian metal, and even if sanctions were relaxed, Trump’s February tariff on all aluminum imports would still apply.

    Meanwhile, most Russian firms remain shut out of international markets, with some—like Ros Agro and Ozon—turning to listings in Kazakhstan, a nation Moscow considers “friendly.”

  • Putin Calls for Accelerated Lithium Mining as Russia Seeks Self-Sufficiency

    Putin Calls for Accelerated Lithium Mining as Russia Seeks Self-Sufficiency

    Russian President Vladimir Putin has urged the country to expedite the development of its domestic lithium and rare earth mineral deposits, citing the strategic importance of these resources for high-capacity battery production and advanced technologies.

    Speaking at a conference in Moscow, Putin criticized the country’s delay in mining lithium, stating, “We still do not mine lithium. And how can we develop without it? But we can do it. And we could have done it 10 or 15 years ago.”

    Russia possesses an estimated 1 million tons of lithium reserves, according to the United States Geological Survey (USGS), with Russian estimates placing lithium oxide reserves at 3.5 million tons. However, prior to the conflict in Ukraine, the country relied on lithium imports, which have been severely disrupted by Western sanctions. As a result, Moscow has intensified efforts to extract its own lithium and aims to eliminate imports of the metal and other rare earth elements by 2030.

    Additionally, Russian forces are advancing toward one of Ukraine’s largest lithium deposits, further underscoring the geopolitical significance of these critical minerals in the ongoing conflict.

  • European Industries Set for a “Made in Europe” Lithium Revolution

    European Industries Set for a “Made in Europe” Lithium Revolution

    Brussels, Belgium – In a bold call for industrial self-reliance, Guillaume Delacroix, Senior Vice President Performance Minerals EMEA & APAC at Imerys and Chairman of Imerys British Lithium, has spearheaded a push for more “Made in Europe” initiatives in the lithium and automotive sectors. Speaking during a high-level discussion in Brussels alongside Executive Vice-President Stéphane Séjourné and other leaders from the battery ecosystem, Delacroix emphasized Europe’s untapped potential in the green and mobility transitions.

    Delacroix outlined a clear three-pronged strategy for enhancing Europe’s role in global value chains:

    Financial Support for a Mining Renaissance: Advocating for increased funding to revive and modernize Europe’s mining industry, a critical step towards reducing dependency on external resources.
    Local Content and Carbon Footprint Incentives: Urging the implementation of measures that promote local sourcing and environmentally responsible practices, thereby strengthening domestic supply chains.
    Regulatory Reforms Aligned with Business Needs: Calling for regulations that not only safeguard the environment but also enable industry players to innovate and compete on the global stage.

    Central to these initiatives is Imerys’ pioneering #EMILI lithium project in France, which exemplifies the company’s commitment to driving the transition towards sustainable, home-grown industrial solutions. As the world leader in specialty minerals, Imerys is poised to leverage its expertise to serve the burgeoning demands of the automotive industry and beyond.

    Delacroix’s remarks come at a pivotal time, as European nations seek to balance economic growth with the imperatives of energy independence and environmental sustainability. By fostering a robust, locally driven supply chain, Europe is positioning itself to not only meet domestic needs but also to contribute significantly to global green transitions.

    The Brussels discussion underscored a shared vision among industry leaders: a future where European innovation, supported by strategic investments and progressive regulatory frameworks, propels the continent to the forefront of the global lithium and automotive markets.

  • Mining cannot be ‘greened’ outcry against Barosso lithium mine in Portugal

    Mining cannot be ‘greened’ outcry against Barosso lithium mine in Portugal

    Barroso, Portugal – A proposed lithium mining project in the scenic Barroso region has sparked fierce opposition from local communities and environmental advocates, who warn that the venture could inflict irreversible damage on one of Europe’s rare Globally Important Agricultural Heritage Systems (GIAHS).

    The project, led by Savannah Resources and its international partners, aims to transform an inactive feldspar and quartz concession into four expansive open-pit lithium mines, with production now projected to begin in 2027. Spanning a total concession area of 593 hectares, the mining operations threaten to disrupt a delicate agro-ecosystem that supports small-scale pastoral farming and preserves unique cultural traditions.

    Critics argue that the environmental risks far outweigh any potential economic benefits. In 2022, the Portuguese Environmental Agency (APA) rejected the initial Environmental Impact Assessment (EIA), citing “very significant and irreversible negative impacts” on the landscape, water resources, and local biodiversity. Although a revised EIA was later issued under conditional approval, local authorities and community groups have mounted legal challenges, arguing that the project endangers the region’s cherished GIAHS status and undermines Portugal’s international environmental commitments.

    Residents describe a climate of intimidation surrounding the project. Opposition groups claim that the mining company has employed aggressive tactics—including 24/7 private security patrols and the deployment of the Republican National Guard—to silence dissent and pressure locals into submission. “The community is being treated as if we were criminals, with our rights and our lands under constant threat,” said a spokesperson from Associação Unidos em Defesa de Covas do Barroso.

    Environmental experts also warn of severe ecological consequences. The project could strain local water supplies by diverting up to 600,000 m³ per year from local springs, jeopardize river habitats, and risk catastrophic failure of tailings storage facilities during extreme weather events. Moreover, the anticipated surge in greenhouse gas emissions could multiply the current carbon footprint of the municipality several times over, contradicting regional climate goals.

    Over 4,600 citizens have signed a petition opposing the mining project, and municipal bodies have passed formal resolutions condemning the plan. The controversy has also reached national parliamentary debates, highlighting broader concerns about how resource extraction projects are approved and monitored in Europe.

    As legal battles continue and protests intensify, the future of the Barroso lithium mine hangs in the balance—a stark reminder of the clash between the global demand for lithium, driven by energy transition imperatives, and the imperative to protect fragile ecosystems and traditional ways of life.