Website: Europe.com

  • Rio Tinto to Halt Serbia’s Jadar Lithium Project as Costs Rise and Progress Stalls

    Rio Tinto to Halt Serbia’s Jadar Lithium Project as Costs Rise and Progress Stalls

    Rio Tinto will suspend development of its long-delayed Jadar lithium project in Serbia, effectively mothballing what was once slated to become Europe’s largest lithium mine. The decision, first reported by Bloomberg and later confirmed by a company spokesperson, places the nearly $3-billion project into “care and maintenance” as the miner seeks to reduce spending and refocus its lithium strategy.

    The move ends Rio’s two-decade effort to unlock the massive Jadar deposit, discovered in 2004 and estimated to produce 58,000 tonnes of battery-grade lithium carbonate annually. Despite the project’s strategic importance for Europe’s battery supply chain, Jadar has repeatedly stalled amid regulatory hurdles, political uncertainty and strong community opposition. Serbia revoked Rio’s licence in 2022 over environmental concerns and only reinstated it last year, but permitting made little progress.

    In the internal memo cited by Bloomberg, Rio said it could no longer justify the level of investment given the limited advancement of the project. Earlier this year, the company raised Jadar’s cost estimate to nearly $3 billion, citing the need to meet stringent EU environmental and human rights standards.

    The suspension is part of broader cost-cutting measures under new CEO Simon Trott, who has introduced restructuring efforts and workforce reductions across the company. With Jadar shelved, Rio is expected to concentrate its lithium ambitions on South America, including Argentina’s Rincon project and joint ventures in Chile.

    Analysts say the decision underscores Rio’s pivot away from hard-rock assets inherited through its merger with Arcadium, and some expect those projects could be sold. The halt also deals a blow to EU plans to secure domestic lithium supply, as Jadar was projected to cover nearly 90% of Europe’s current demand.

  • Solvay Signs Two US Supply Deals to Boost Rare Earth Processing Capacity in France

    Solvay Signs Two US Supply Deals to Boost Rare Earth Processing Capacity in France

    Chemicals group Solvay has secured two new supply agreements with US magnet manufacturers as it accelerates efforts to scale up rare earth processing at its La Rochelle plant in France. The company, one of the few outside China capable of performing complex rare earth separation, began limited processing in April and has been seeking commercial commitments from industry and government partners to expand production.

    Solvay will supply neodymium, praseodymium, dysprosium and terbium (NdPr and DyTb) to Texas-based Noveon Magnetics under the first agreement. These elements are essential for neodymium-iron-boron (NdFeB) permanent magnets used in electric vehicles, defence systems, consumer electronics, and wind turbines. Noveon began commercial production of sintered NdFeB magnets in 2023.

    A second agreement with Permag covers the supply of samarium oxide, which will be converted into samarium metal by UK-based Less Common Metals. Samarium-based magnets can withstand extremely high temperatures and are widely used in defence and nuclear applications.

    Solvay CEO Philippe Kehren said the initial deliveries involve limited volumes but noted that the La Rochelle facility could rapidly increase output. Production of NdPr and samarium oxide will begin shortly, while DyTb output is expected to start in 2026.

    Kehren also indicated that Solvay is exploring the possibility of building a rare earths processing plant in the United States, where financial support for strategic materials is stronger than in Europe. Company executives said US customers are already willing to sign long-term contracts, while European buyers are still moving more slowly despite recognizing the need for supply chain independence.

  • Austrian Firms Eye Mining, Hydropower, and Tech Investments in Kyrgyzstan

    Austrian Firms Eye Mining, Hydropower, and Tech Investments in Kyrgyzstan

    Austrian companies are exploring new opportunities to participate in Kyrgyzstan’s mining, industrial, hydropower, winter tourism, digitalization, and security technology sectors, the Kyrgyz Ministry of Foreign Affairs announced following high-level meetings in Vienna, Trend reports.

    During the visit, Kyrgyz Deputy Foreign Minister Meder Abakirov held a series of discussions with senior Austrian officials, including Markus Hoffer, Head of the Austria–Central Asia parliamentary friendship group, and members of the Austrian Parliament. Talks centered on strengthening economic and technological cooperation between the two countries, as well as expanding dialogue within the Central Asia+ format.

    Deputy Minister Abakirov also briefed the Austrian side on preparations for Kyrgyzstan’s parliamentary elections scheduled for November 30, 2025, and invited Austria to join as election observers. Hoffer confirmed that Austrian parliamentarians plan to participate as part of an OSCE monitoring mission.


    Economic and Industrial Cooperation

    In a separate meeting with Austrian Deputy Finance Minister Andreas Reichhardt, the two sides reviewed progress on agreements reached during Kyrgyz President Sadyr Japarov’s visit to Austria in November 2024. Key focus areas included finance, natural resources development, and digital transformation initiatives.

    Both parties emphasized Austria’s technological expertise and discussed the involvement of Austrian firms in a range of Kyrgyz projects, including:

    • Mining and industrial production,

    • Hydropower development,

    • Winter tourism and skiing infrastructure,

    • Digital and security technology applications.


    Strategic Dialogue and Regional Role

    Deputy Minister Abakirov also met with experts from the Austrian Institute for European and Security Policy (AIES), where he provided updates on Kyrgyzstan’s reform agenda, current economic and political developments, and the country’s role in regional and global security.

    The discussions were also joined by members of the Kyrgyz-Austrian Friendship Society, underscoring the growing diplomatic and cultural engagement between the two nations.

  • Serbia Zijin Copper Files for Environmental Review of New Kraku Bugaresku–Cerovo Expansion

    Serbia Zijin Copper Files for Environmental Review of New Kraku Bugaresku–Cerovo Expansion

    Serbia Zijin Copper LLC Bor, a subsidiary of Zijin Mining Group, has filed a formal request with Serbia’s Ministry of Environmental Protection to prepare an Environmental Impact Assessment (EIA) for the planned exploitation of the Cementation 2 and Cementation 3 ore bodies at the Kraku Bugaresku–Cerovo Cementation deposit, near Bor.

    The new project marks a continuation of decades-long mining activity in the region, following previous open-pit operations at Cementation 1, according to eKapija. The deposit lies about 13 kilometers from Bor and 2 kilometers from Mali Krivelj, on the ridge of the Kraku Bugaresku hill.


    Project Scope and Development Phases

    The EIA request, prepared by the Faculty of Mining and Geology at the University of Belgrade, builds on earlier approvals from the Ministry of Mining and Energy dating back to 1991 and 2018.

    Mining at Cementation 2 and 3 will proceed in five phases:

    1. Initial extraction in the northern section of Cementation 2.

    2. Expansion southwest.

    3. Opening of the Cementation 3 pit.

    4. Southward expansion of both pits.

    5. Subsequent exploitation of Cementation 4 reserves in the southeast.

    The open-pit Cementation 2 is designed to produce 3.5 million tonnes of ore annually over a seven-year mine life. The project’s estimated net present value (NPV) stands at $117 million in the best-case scenario, positioning it among Serbia’s most significant mining investments in recent years.


    Waste Management and Environmental Measures

    Ore extraction will follow discontinuous mining technology, involving drilling, blasting, loading, and transport to the primary crusher, alongside drainage and auxiliary works.

    A total of 61.1 million tonnes of waste rock is expected to be generated. The existing waste rock dumps from Cementation 1 will be expanded to accommodate material from Cementation 2 and 3, increasing total dump capacity to 61.9 million tonnes.

    The project also requires hydrological modification: the Cerova River, which flows between the open pit and access roads, will be diverted and piped, with a reinforced embankment wall constructed downstream to protect infrastructure.


    Context and Outlook

    The Kraku Bugaresku–Cerovo expansion reinforces Zijin’s long-term presence in Serbia, where the company operates major copper and gold projects. It also reflects the continued development of Serbia’s Bor mining basin into a regional hub for base metals production.

    The forthcoming Environmental Impact Assessment will evaluate the project’s potential effects on water resources, biodiversity, waste management, and local communities, determining the conditions under which exploitation may proceed.

  • Ukraine’s Titanium Comeback: A Strategic Blueprint for Rebuilding Europe’s Titanium Industry

    Ukraine’s Titanium Comeback: A Strategic Blueprint for Rebuilding Europe’s Titanium Industry

    For decades, titanium has been a cornerstone of aerospace, defense, and high-tech manufacturing — prized for its strength, lightness, and resistance to corrosion. Yet behind this strategic metal lies a highly concentrated global industry, where only a handful of nations control production of titanium sponge, the raw metallic form of the element.

    Among them, Ukraine once stood as a global leader, the industrial backbone of the Soviet titanium complex and one of the few countries that mastered the Kroll process — the key technology for sponge production. Ukraine uniquely combined chemical, metallurgical, and scientific expertise, hosting its own Institute of Titanium and advanced hydrometallurgical facilities capable of extracting not only titanium but also zirconium and hafnium.

    Today, that legacy stands disrupted. The Russian invasion has fractured Ukraine’s heavy industry and halted sponge production since 2021. But it also opened a potential path forward: the chance for Ukraine to reclaim a central role in Western titanium supply chains, as the world scrambles to reduce dependence on Russia and China.


    Global Titanium Landscape

    According to the US Geological Survey, global titanium sponge capacity reached 410,000 tons in 2024, with production steady at around 320,000 tons. The market is heavily consolidated:

    • China accounts for nearly 69% of global output, producing mainly industrial-grade sponge for domestic use.

    • Japan, Saudi Arabia, and Kazakhstan supply almost all of the aerospace-grade sponge imported by the United States and the European Union.

    • Russia remains integrated in its own defense value chain, but sanctions have eroded margins and logistics competitiveness.

    • Ukraine, a former key player, has recorded zero production since 2021.

    While China dominates the midstream segment with state-backed clusters, low-cost energy, and full integration, it lacks certification pathways to access Western aerospace markets. By contrast, Japan and Saudi Arabia occupy the high-quality premium segment, selling sponge at $11,000–13,000 per ton, compared with China’s $7,000 average price.

    The United States and EU remain the largest consumers and stockpilers, offering the most stable and profitable end markets — but they are also the most supply-constrained.


    Why Ukraine Matters

    Ukraine is the only European nation with both a high-grade mineral base and the industrial legacy to re-enter titanium sponge production. Its ilmenite and rutile deposits can support chloride-route Kroll processing, the same route used for aerospace-quality sponge.

    Even a 10,000–15,000 tpa facility could anchor a new Titanium Cluster serving Western markets. The cluster could later expand into VAR smelting (Vacuum Arc Remelting) to produce ingots and billets, especially for Ti-6Al-4V alloys used in aviation and defense.

    Strategically, this would fill a critical gap in the non-Chinese, non-Russian titanium segment, providing Europe with a certified domestic source of titanium metal for the first time in decades.


    Key Enablers and Investment Model

    Rebuilding Ukraine’s titanium metallurgy requires three foundational pillars:

    1. Energy Efficiency and Security:
      Titanium sponge production is power-intensive, with electricity costs accounting for 20–30% of total cash costs. Stable, affordable power — ideally renewable or nuclear — is crucial.

    2. Integrated Clustering:
      A vertically integrated industrial cluster combining mining, sponge, smelting, and by-product recovery (zirconium, hafnium, germanium) would minimize costs and maximize value retention.

    3. Strategic Financing:
      A $400–700 million CAPEX is needed for a 10,000–15,000 tpa sponge facility, with an additional $350–400 million for smelting capacity. Financing could come through long-term offtake contracts with Western aerospace and defense OEMs, supported by instruments such as the U.S.–Ukraine Reconstruction Investment Fund.

    Advanced payments and consortium-based equity could unlock broader project financing, while ensuring certification alignment with Western standards.


    Outlook and Feasibility

    Global titanium sponge output is forecast to reach 400,000–440,000 tons by 2035, driven by:

    • Rising aerospace demand (notably from Airbus A320 and Boeing 737 MAX programs).

    • Global rearmament and stockpiling.

    • Ongoing supply diversification efforts by Western governments.

    Within this framework, Ukraine and India are viewed as the two most promising re-entry markets. Ukraine could restore 5,000–10,000 tons per year of production by 2035, scaling to 15,000 tons under favorable conditions.

    Even modest early-stage output would offer strategic returns: it would anchor a European titanium hub, reduce Western supply risk, and cement Ukraine’s industrial role in the critical minerals value chain.


    Conclusion

    Ukraine possesses the minerals, know-how, and geographic advantage to rebuild a titanium industry that serves Europe’s long-term strategic interests.

    If paired with targeted investment, certification partnerships, and energy reforms, Ukraine could re-establish itself as a core supplier of aerospace-grade titanium, bridging the gap between resource-rich producers and high-tech Western consumers.

    Far from a nostalgic revival, this would mark a new strategic chapter — positioning Ukraine not just as a raw material exporter, but as Europe’s titanium powerhouse.
  • Tungsten West Produces First Tungsten Concentrate in Hemerdon Restart Trial

    Tungsten West Produces First Tungsten Concentrate in Hemerdon Restart Trial

    Tungsten West (LON: TUN) has achieved a major milestone in its plans to restart production at the Hemerdon mine in Devon, England, after successfully producing its first tungsten concentrate during an ongoing mineral processing trial.

    The trial is part of a broader plant optimization and technical validation program, designed to test and enhance the performance of key sections of the mine’s processing facility. The company said the data collected will support the planned restart of full-scale operations, expected by late 2026.

    “This progress marks an important milestone in restarting operations at Hemerdon,” said CEO Jeff Court. “It provides confidence to our neighbours, the environment agency, investors and off-takers that we are moving towards production.”

    Court added that the company is maintaining high environmental and operational standards throughout the trial, noting Hemerdon’s growing importance as demand for diversified tungsten supply intensifies globally.


    Strategic Importance

    Hemerdon — historically known as Drakelands mine — is one of the largest tungsten deposits in the world. Located about 7 miles northeast of Plymouth, the site has a long mining history, with operations dating back to 1918 and production during both World Wars.

    After feasibility work in the 1980s, the mine was redeveloped into a modern tungsten and tin operation that ran from 2015 to 2018 under previous ownership. The project’s restart is considered strategically significant for both the UK and Europe, offering a potential secure tungsten supply outside China, which dominates global production.

    Tungsten is a relatively small market — valued at around $5 billion in 2023 — but it plays a critical role in defense and high-tech industries. Its density and hardness make it the material of choice for armour-piercing ammunition, aerospace components, and heavy-duty tools.


    Market Reaction

    Shares in Tungsten West rose 12% following the announcement, closing with a market capitalization of £21.28 million ($28 million).

    The company’s management emphasized that the successful trial demonstrates technical readiness and operational credibility, key steps toward securing financing and offtake agreements for the mine’s full-scale restart.

  • Sweden Lifts Uranium Mining Ban, Opening Path to Exploration from January

    Sweden Lifts Uranium Mining Ban, Opening Path to Exploration from January

    Sweden’s parliament, the Riksdag, has voted to repeal a 2018 moratorium on uranium mining, reopening the country to exploration and production beginning January 1. The decision restores uranium’s status under the Minerals Act, enabling companies to apply for exploration and mining concessions after a seven-year freeze.

    The move positions Sweden — which holds an estimated 27% of Europe’s known uranium resources, according to the Geological Survey of Sweden — to play a larger role in Europe’s energy transition and nuclear fuel supply security.

    “It is very positive that the Riksdag is now backing the government’s proposal,” said Maria Sunér, CEO of the Swedish Mining Association (Svemin). “There are no factual reasons for uranium to be treated differently than other metals, and it is therefore entirely reasonable that we now have the opportunity to utilize the resources found in our bedrock efficiently.”

    A municipal veto on handling small quantities of uranium was also narrowed, reducing local barriers to development.


    Policy Shift and Strategic Context

    The repeal caps a two-year legislative push led by Sweden’s Climate and Enterprise Ministry. The government formally presented the bill in August 2025, describing uranium as strategic for both nuclear energy expansion and raw-materials security.

    Sweden operates six nuclear reactors, supplying roughly one-third of the nation’s electricity. Plans are underway to build several new reactors over the next decade to meet surging power demand.

    The change also aligns with broader EU supply-chain resilience goals, as the bloc seeks to reduce its dependence on imported uranium, particularly from Russia.


    Exploration Ready to Resume

    Several companies are preparing to act immediately.

    Australian explorer Aura Energy (ASX: AEE; AIM: AURA), which controls the Häggån polymetallic deposit in Jämtland, has already submitted a 25-year exploitation permit to Sweden’s Mining Inspectorate. Häggån’s JORC resource includes roughly 800 million lb of uranium oxide (U₃O₈) within a 2.55-billion-tonne vanadium deposit.

    “This vote means that from now on uranium has the potential to be an important contributor to Sweden’s economy and energy security and to support the region’s intention to triple nuclear power,” said Aura executive chairman Phil Mitchell.

    Canada’s District Metals (TSXV: DMX) also hailed the vote as a “historic step.” The company plans fieldwork in 2026 at its Viken project, including geophysics, drilling, and economic studies. Viken hosts an indicated resource of 176 million lb U₃O₈ and an inferred resource of 1.54 billion lb U₃O₈, alongside vanadium and molybdenum.


    Market Response

    Despite the legislative breakthrough, uranium developers saw modest share pullbacks:

    • Aura Energy fell 7% to A$0.20, trimming its 12-month gain to 46% (market cap A$188 million / $122 million).

    • District Metals slipped 6% to C$1.37, giving it a valuation of C$228 million ($162 million), though its stock has quadrupled in the past year.


    Next Steps

    A separate proposal is now under consultation until December 3 to redefine uranium mining so it is no longer legally classified as a nuclear installation. If adopted, that change would take effect on July 1, 2026, further simplifying the permitting process.

  • EU Sets Up “Special Channel” with China to Secure Rare Earth Supply

    EU Sets Up “Special Channel” with China to Secure Rare Earth Supply

    The European Union has established a special communication channel with Chinese authorities to ensure the continuous flow of rare earth materials essential for European industries, EU Trade Commissioner Maros Sefcovic said on Wednesday.

    The move comes after China imposed export controls on rare earths earlier this year, triggering alarm in Europe over possible disruptions to the supply of critical materials used in electric vehicles, wind turbines, and permanent magnets — key components for clean energy and high-tech manufacturing.

    Speaking at the 2025 GCC–EU Business Forum in Kuwait, Sefcovic told Reuters that he had held multiple discussions with Chinese Commerce Minister Wang Wentao, emphasizing that bureaucratic delays in export procedures could have a “very negative impact on production and manufacturing in the EU.”


    Fast-Track Cooperation Mechanism

    Brussels and Beijing have agreed to prioritize export permit applications from European companies. Through the newly established channel, EU and Chinese officials are jointly reviewing and fast-tracking export approvals for rare earth shipments.

    According to Sefcovic, European companies have submitted about 2,000 applications since the controls were introduced, with just over half already approved. He said the EU was urging China to accelerate the remaining cases while pursuing broader supply chain diversification.

    “We continue to press for faster processing,” Sefcovic said, adding that Europe is simultaneously developing alternative rare earth sources, including new mining and magnet production projects in Estonia.


    Wider Context

    The announcement follows months of tension between Europe and Beijing after China’s export restrictions on rare earths and related technologies. Although subsequent deals with the EU and the United States helped ease the immediate supply squeeze, both regions have intensified efforts to reduce dependence on Chinese critical materials.

    On Tuesday, the European Commission confirmed that EU and Chinese officials discussed introducing general export licenses to simplify rare earth shipments — similar to arrangements reportedly secured by the United States.

  • Kazakhstan Boosts Mining and Critical Raw Materials Education with $50 Million Investment

    Kazakhstan Boosts Mining and Critical Raw Materials Education with $50 Million Investment

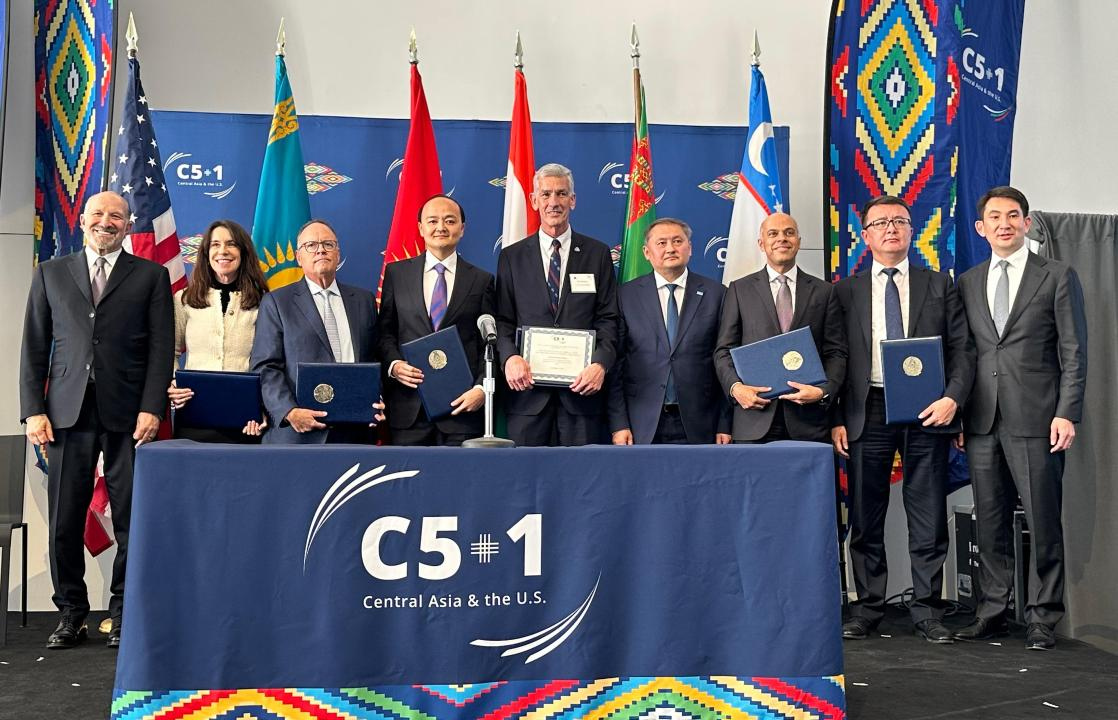
    Kazakhstan has taken a significant step forward in advancing its mining and critical raw materials sectors by signing a $50 million agreement with the prestigious Colorado School of Mines. This partnership will focus on establishing Ulytau Technical University in Zhezkazgan. The initiative aims to enhance technical education, foster innovation, and develop dual-degree programs, positioning Kazakhstan as a leader in the global mining sector.

    The  Ulytau Technical University in collaboration with the Colorado School of Mines will provide students with state-of-the-art facilities and resources, equipping them with the skills and knowledge needed to excel in the mining industry. The university will serve as a hub for research and development, addressing the critical needs of the mining sector and contributing to the sustainable development of Kazakhstan’s natural resources.

    In addition to the partnership with the Colorado School of Mines, Kazakhstan has also signed agreements with Arizona State University and Coursera, totaling $50 million. These agreements emphasize the digitalization of academic processes and the implementation of adaptive learning systems developed in partnership with the Educational Testing Service (ETS). These systems will tailor educational experiences to individual student needs, ensuring more effective and personalized learning outcomes.

    Furthermore, a memorandum signed by the Kazakh Ministry of AI and Digital Development, the Ministry of Science and Higher Education, Kazakhtelecom, Freedom Holding, and OpenAI will integrate artificial intelligence into the education sector. This collaboration will provide Kazakh educators with access to ChatGPT Edu, a specialized version of OpenAI’s AI tool designed for educational purposes. Under the agreement, 165,000 OpenAI licenses will be provided annually to Kazakh teachers over the next three years.

    Kevin Mills, Head of Education and Government Programs at OpenAI, expressed enthusiasm about the partnership, stating, “Educators worldwide are using AI to save time and focus on what matters most — student learning. Our partnership with the Government of Kazakhstan will help teachers bring AI-powered tools like ChatGPT into classrooms across the country.”

    The investments and collaborations are expected to yield significant benefits, positioning Kazakhstan as a leader in mining, critical raw materials research, and education in the region.

  • Savannah Resources Raises £9.2 Million in Oversubscribed Fundraise to Advance Barroso Lithium Project

    Savannah Resources Raises £9.2 Million in Oversubscribed Fundraise to Advance Barroso Lithium Project

    Savannah Resources Plc (AIM: SAV, FWB: SAV, SWB: SAV) announced it has successfully completed an oversubscribed £9.2 million (US$12 million) capital raise through a Placing and Subscription, with strong demand from existing and new institutional investors.

    The fundraising, managed through an accelerated bookbuild by SP Angel Corporate Finance LLP (Global Coordinator and Joint Bookrunner), alongside Canaccord Genuity Limited, Caixa-Banco de Investimento S.A., and Alantra Equities S.V. S.A., was significantly oversubscribed and scaled back as a result.

    The Company raised £5.9 million (US$7.6 million) via the Placing of 158.7 million shares and a further minimum £3.4 million (US$4.4 million) through a Subscription of at least 90.8 million shares, both at an issue price of 3.7 pence per share.

    Savannah’s Retail Offer remains open until 12:00 p.m. on 11 November 2025, after which final subscription totals will be confirmed.


    Use of Proceeds

    Net proceeds from the fundraise will strengthen Savannah’s financial position and accelerate development of the Barroso Lithium Project in northern Portugal — the largest battery-grade spodumene lithium resource in Europe and a European Commission “Strategic Project” under the Critical Raw Materials Act.

    Funds will be used to:

    • Acquire the Aldeia Mining Lease, which contains the highest-grade deposit within the Barroso Project area.

    • Advance Front-End Engineering Design (FEED) and long-lead item procurement.

    • Progress grid connection work and land control for infrastructure.

    • Cover project financing costs and provide additional working capital.


    CEO Statement

    Emanuel Proença, Chief Executive Officer, commented:

    “The strong demand from investors, which exceeded our US$12 million target, reflects growing confidence in the Barroso Lithium Project and renewed optimism in the lithium sector.

    With total cash reserves of approximately £20 million (US$26 million), Savannah is well positioned to move beyond the DFS and into pre-construction with confidence.

    The additional capital allows us to acquire the Aldeia Mining Lease and further progress critical workstreams ahead of construction.”

    Proença added that Savannah continues to expand its institutional investor base across Portugal, the UK, and Europe, with participation from both sector specialists and generalist investors. Retail investors are now able to participate through the open offer.


    Related Party Participation

    Key management and major shareholders took part in the subscription:

    Participant Subscription Shares Value (£) Resulting Shareholding
    Rick Anthon (Chairman) 550,676 £20,375 1,264,962 shares
    Emanuel Proença (CEO) 387,676 £14,352 3,124,556 shares
    Henrique Freire (CFO) 220,050 £8,135 2,520,050 shares

    Major shareholders also increased their stakes:

    • AMG Lithium B.V. subscribed for 39.1 million shares, bringing its total to 400.8 million shares.

    • Grupo Lusiaves SGPS, S.A. subscribed for 24.95 million shares (total 255.9 million).

    • Pluris Investments S.A. subscribed for 24.95 million shares (total 255.9 million).

    Their participation constitutes a related party transaction under AIM Rule 13. Independent directors Diogo da Silveira and Bruce Griffin reviewed the terms and deemed them fair and reasonable for shareholders.


    Admission and Next Steps

    Application has been made for the new shares to be admitted to trading on AIM. Dealings in the Placing and Subscription Shares are expected to commence at 8:00 a.m. on 12 November 2025.

    A separate announcement will follow for the Retail Offer results and Admission of additional shares.


    About Savannah Resources

    Savannah Resources Plc is a European lithium development company focused on the Barroso Lithium Project in northern Portugal. Once operational, the project is expected to produce around 190,000 tonnes per year of spodumene concentrate, enough lithium for approximately 500,000 electric vehicle battery packs annually.

    Through responsible development, Savannah aims to support Europe’s energy transition and contribute to the EU’s target of 10% domestic lithium supply by 2030.