Website: Asia.com

  • Kazakhmys Launches New Industrial Safety Strategy with Digital Overhaul and Risk-Based Approach

    Kazakhmys Launches New Industrial Safety Strategy with Digital Overhaul and Risk-Based Approach

    Kazakhstan’s mining giant Kazakhmys is ramping up its commitment to industrial safety with a comprehensive new strategy focused on digital transformation, increased investment, and a proactive risk management model, according to CEO Nurakhmet Nuriev, who presented the measures at a recent government meeting.

    Digital Tools Take Center Stage

    A key pillar of the safety overhaul is digitization. Since 2021, Kazakhmys has implemented real-time tracking systems for personnel and equipment in its mines, enabling quicker emergency responses. In 2022, a process monitoring system was deployed at the Balkhash enrichment plant, and in 2025, the company launched pilot versions of a barrier-based injury prevention system and the integrated Kazakhmys SuperAPP, which digitizes HR and workplace safety workflows.

    Kazakhmys is also rolling out automated PPE (personal protective equipment) tracking, digital medical screening systems, and a centralized platform for occupational safety management.

    Tangible Results: 25% Drop in Workplace Incidents

    Over the past three years, Kazakhmys has achieved a 25% reduction in workplace accidents. Although a gas explosion at the Zhomart mine in 2025 marked the first such incident since 2014, the overall safety trend remains positive. The most common risks—rockfalls and machinery collisions—are now under tighter control.

    The company has invested 24 billion tenge in labor safety since 2022, with an additional 26 billion tenge allocated for 2025. These funds support not just technical upgrades but also employee training, culture-building, and safety tech innovation.

    New Strategy Anchored on Five Key Priorities

    Kazakhmys’s updated safety framework for 2025 is built around five core principles:

    1. Fostering a culture of safety;

    2. Shifting toward proactive labor protection management;

    3. Deepening digitization;

    4. Implementing barrier-based, risk-oriented oversight;

    5. Expanding occupational health systems.

    A technical audit conducted in 2025 uncovered 2,378 safety violations, with 64 operations suspended until issues were resolved. The company now tracks 15 key production risks and has tightened internal control protocols.

    Accountability and Inclusion

    Safety KPIs are being extended to top management, while contractors, who significantly impact incident rates, are now held to strict safety standards. A violation tracking system is also in place, and serious incidents are reviewed at plant-level safety councils, with individuals held personally accountable.

    Kazakhmys’s approach signals a shift from reactive measures to a preventative, risk-aware safety culture embedded at every level of the organization.
  • Chinese Firm East Hope Group to Invest in Major Green Aluminium Project in Kazakhstan

    Chinese Firm East Hope Group to Invest in Major Green Aluminium Project in Kazakhstan

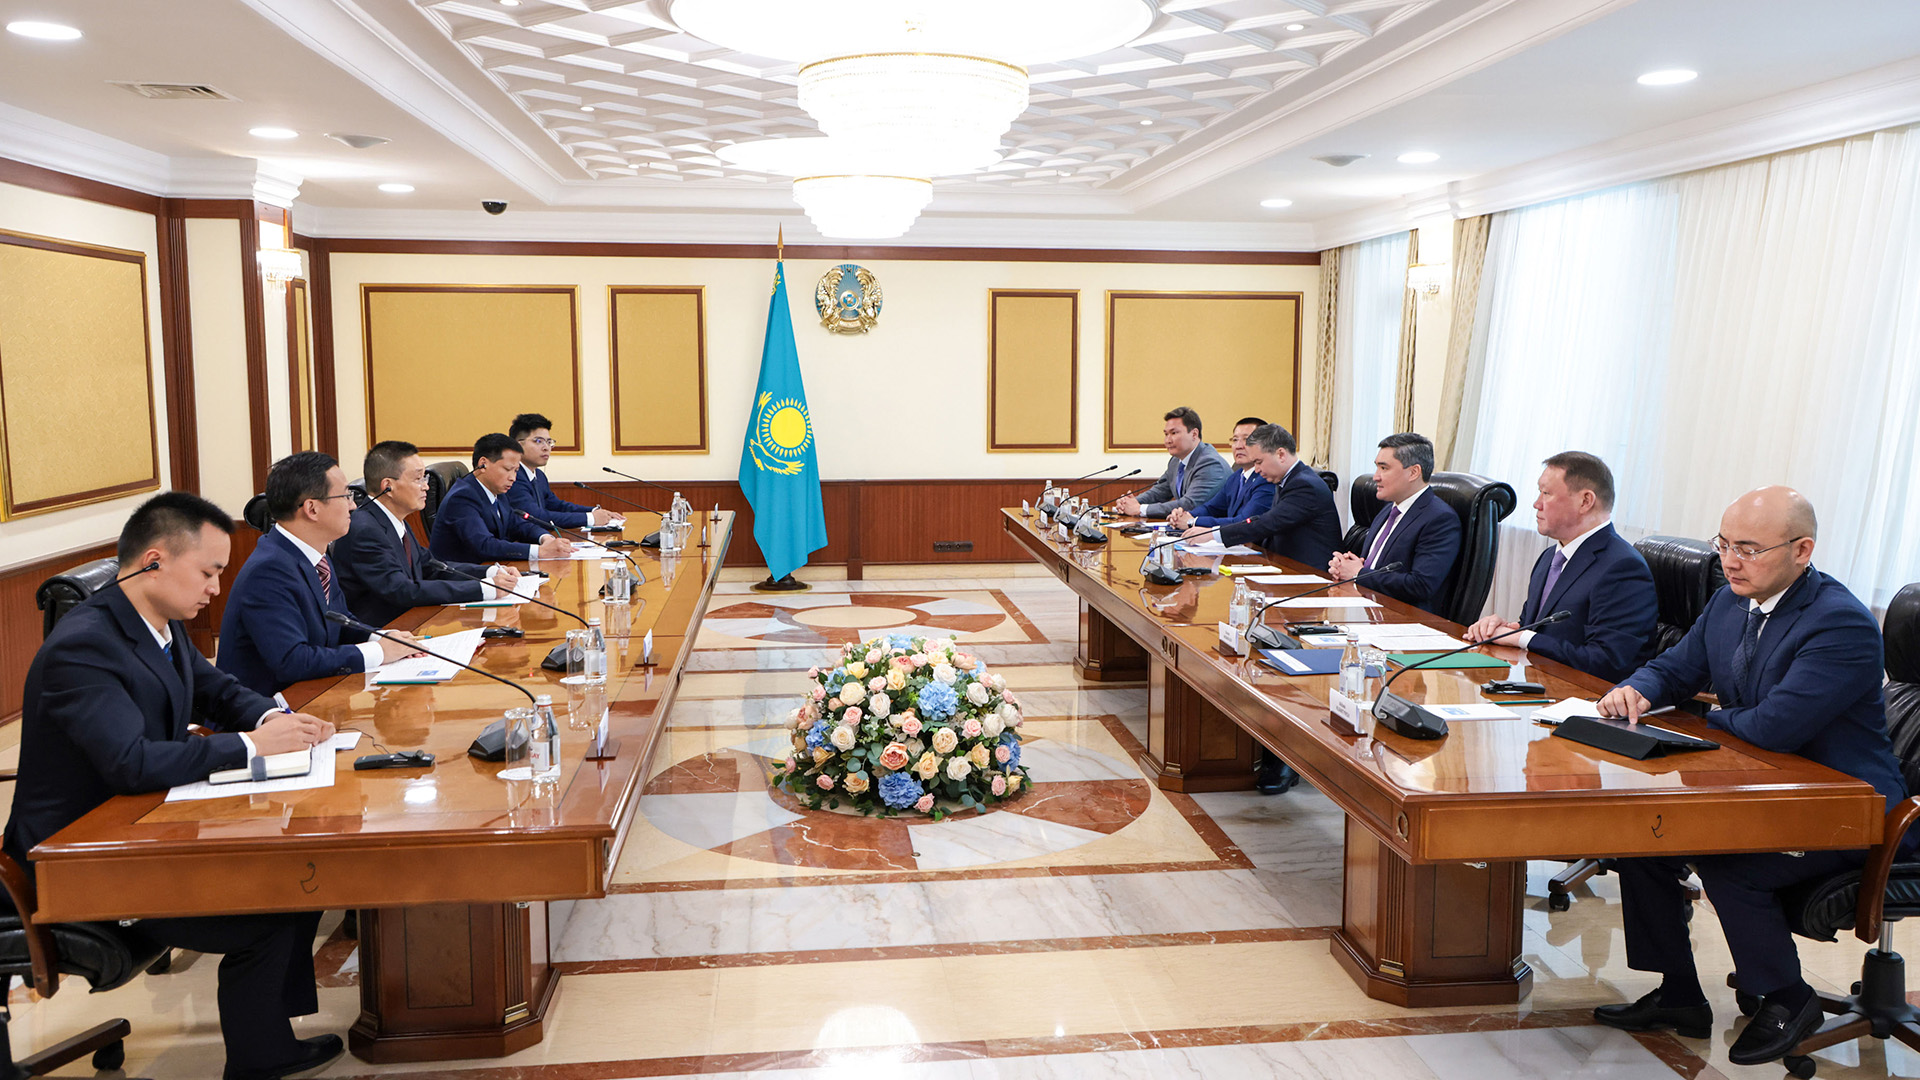
    Kazakhstan’s Prime Minister Olzhas Bektenov met with Liu Yongxing, Chairman of the Board for China’s East Hope Group, to discuss an ambitious project aimed at establishing a vertically integrated industrial park for “green” aluminium production in Kazakhstan. This initiative is designed around the principles of a circular economy, marking a significant step in the nation’s drive to diversify its economy.

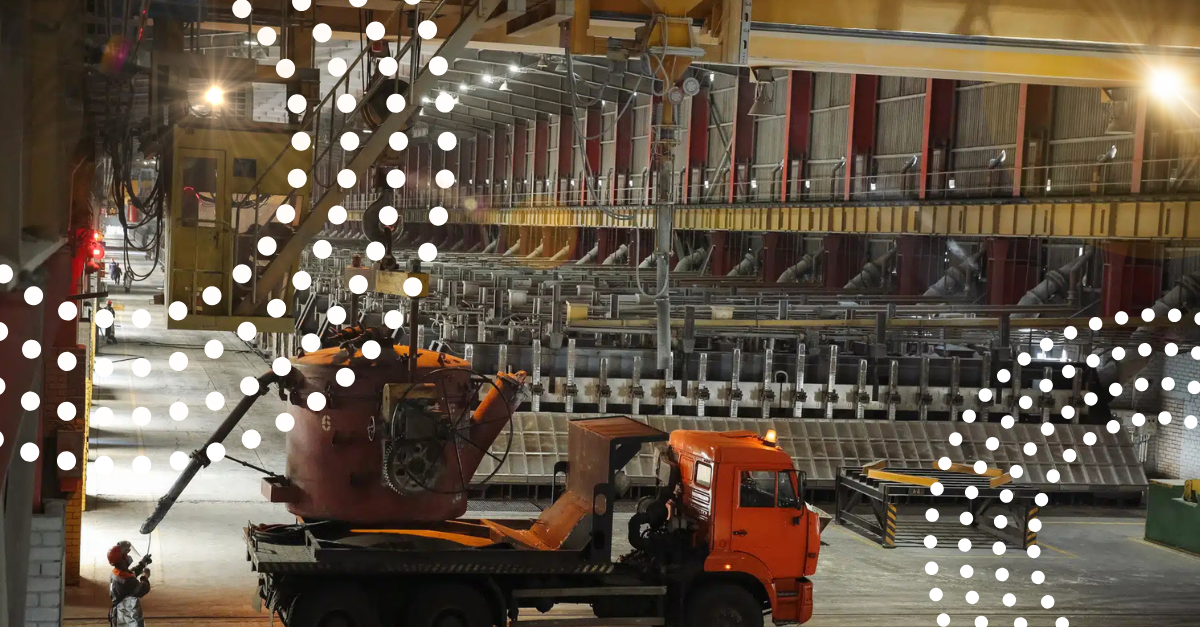
    The proposed project encompasses the entire production cycle of “green” aluminium, from raw material extraction to the deep processing of high value-added materials. The initial phase includes constructing an ore dressing plant capable of processing 2 million tonnes of alumina annually, alongside an electrolysis plant to produce 1 million tonnes of aluminium per year. Crucially, the plan integrates renewable energy sources for electricity generation. East Hope Group estimates the project will create over 10,000 permanent jobs.

    “President Kassym-Jomart Tokayev has set the task of building a more diversified and future-oriented economy,” stated Prime Minister Bektenov. “We are gradually reducing our dependence on the raw materials sector and developing high value-added production. The creation of a vertically integrated aluminium production in Kazakhstan is a unique project that will ensure the comprehensive development of this sector within our domestic industry. The Government of Kazakhstan is ready for long-term cooperation.”

    Liu Yongxing highlighted Kazakhstan’s strategic importance as a logistical hub in Eurasia, noting its unique geographical advantages and development potential within the context of the “Belt and Road” initiative. He emphasised that Kazakhstan’s rich mineral resources and ongoing industrial modernisation strategy align perfectly with East Hope Group’s global priorities in “green” aluminium, modern agriculture, and renewable energy.

    Following the meeting, relevant ministries were instructed to provide the necessary support for the project’s implementation. East Hope Group has committed to certain obligations, including the training of local personnel and a phased increase in the proportion of Kazakhstani workers.

    East Hope Group is a global leader in the aluminium industry and is also active in polysilicon, “green” energy, agribusiness, and high-tech sectors.

  • ERG Subsidiary Pays Out More in Dividends Than It Earned

    ERG Subsidiary Pays Out More in Dividends Than It Earned

    Kazakhstan’s Electrolysis Plant (KEZ), part of Eurasian Resources Group (ERG), has distributed 18.7 billion tenge in dividends for 2023—10.6% more than its net profit of 16.9 billion tenge for the period, according to data published by the Kazakhstan Stock Exchange (KASE).

    In 2024, KEZ recorded a net profit of 59 billion tenge, while its total assets as of 1 April 2025 stood at 424.3 billion tenge, with liabilities reaching 181.6 billion tenge. The first quarter of 2025 saw a slight 0.06% dip in assets, amounting to 2.8 billion tenge, while liabilities surged by 61 billion tenge—an increase of 150%.

    The company previously announced plans to raise up to $100 million on KASE through bond issuance, with a nominal value of $1,000 per bond. The bonds, carrying a three-year term and semi-annual coupon payments, attracted $51 million in investment at a 6.5% coupon rate on 30 May. Another round of subscription is scheduled for 10 June 2025 to sell the remaining bonds.

    ERG’s ownership structure includes Kazakhstan’s Ministry of Finance (40%), heirs of Alexander Mashkevich and the Ibrahimov family (20.7% each), and Patokh Shodiev (18.6%).

    For more details, check the original report here.

  • Kazakhstan Expands Uranium Exports to Bulgaria’s Nuclear Industry

    Kazakhstan Expands Uranium Exports to Bulgaria’s Nuclear Industry

    Kazakhstan is set to supply uranium to Bulgaria’s nuclear power stations, according to Nurlan Zhakupov, the head of the Samruk-Kazyna Fund, who spoke to journalists at the Akorda presidential residence.

    Bulgaria operates a nuclear power plant with two 1,2 MW units, presenting a significant opportunity for cooperation in uranium supplies, Zhakupov explained. However, details regarding the volume of supplies remain confidential.

    Zhakupov also revealed that Kazakhstan Atomic Energy Stations (KAES), currently a subsidiary of Samruk-Kazyna, will transition to the newly established Agency for Atomic Energy. KAES will focus on the construction of nuclear power plants within Kazakhstan.

    Earlier reports indicated that Kazatomprom would supply uranium concentrate to the Czech Republic. This deal aligns with Kazatomprom’s global strategy to diversify its sales channels.

    Last year, Kazatomprom produced over 23,000 tonnes of uranium. Since 2022, Kazakhstan has been supplying uranium fuel to China’s nuclear power plants and, in December, completed a uranium shipment to Canada via the Trans-Caspian International Transport Route.

    In February of this year, Kazakhstan agreed to collaborate in the uranium sector with Jordan and to supply uranium to Switzerland.

  • Rio Tinto Shifts Oyu Tolgoi Mine Plan Due to License Delays

    Rio Tinto Shifts Oyu Tolgoi Mine Plan Due to License Delays

    Rio Tinto has announced adjustments to its underground development plan at the Oyu Tolgoi copper-gold mine in Mongolia. While the company remains committed to its target of 500,000 tonnes of copper production per year from 2028 to 2036, development in the Entrée Resources joint venture (JV) area has been paused due to delays in license transfers to the mine’s operating entity.

    This decision allows Rio Tinto to prioritise development in the more accessible Panel 2 South, ensuring the project stays on track.

    However, the delay in the Entrée JV area has caused concern for Entrée Resources, which expressed disappointment over the holdup, highlighting its potential impact on the project’s timeline, cost, and their financial position.

    Despite these challenges, Rio Tinto maintains its 2025 copper production guidance and underscores the importance of Oyu Tolgoi, one of the world’s largest known copper-gold resources, for both its growth strategy and Mongolia’s economic development.

  • Kazakhstan’s Inkai Uranium JV Skews Dividend Split Despite Shareholding Structure, Raising Questions

    Kazakhstan’s Inkai Uranium JV Skews Dividend Split Despite Shareholding Structure, Raising Questions

    Kazakhstan’s leading uranium joint venture Inkai, operated by Kazatomprom and Canada’s Cameco, is distributing dividends based on production output—not shareholder equity—according to Kazatomprom’s Q1 financials. Although Kazatomprom holds a 60% stake and Cameco 40%, dividends for 2025 will be split 55.63% to Kazatomprom and 44.37% to Cameco, diverging from the nominal ownership structure.

    The adjusted payout arrangement stems from a 2024 supplemental agreement, but the formula and justification remain undisclosed. This has fueled speculation following production shortfalls in 2024 due to operational issues, including a 23-day shutdown in January and disruptions in sulfuric acid supply following the switch from Russian imports.

    For 2025, output at Inkai is expected at 8.3 million pounds (approx. 3,200 tonnes) of uranium oxide (U₃O₈), with Cameco receiving 3.7 million pounds, down from prior projections of 4.2 million. In 2024, actual production fell short at 2,992 tonnes, compared to 3,230 tonnes in 2023.

    In 2023, output was evenly split between Kazatomprom and Cameco. However, in 2024, Kazatomprom received 1,619 tonnes, 246 tonnes more than Cameco. No official explanation has been offered for the shift, though Kazatomprom states that the distribution mechanism is mutually agreed upon, with no penalties or exceptions.

    Kazatomprom emphasized it is not authorized to speak on behalf of Cameco and directed further questions to the Canadian partner, which did not respond to inquiries from inbusiness.kz.

    Historically, the production share has fluctuated. Between 2020 and 2021, Cameco’s share peaked at 59.4%, highlighting the flexible, performance-based distribution model set in the 2016 restructuring agreement. The split is expected to align with equity once Inkai reaches 4,000 tonnes/year output.

    Kazatomprom vs Cameco: A Comparative Glance

    Analysts at Teniz Capital recently questioned why Cameco’s market capitalization exceeds that of Kazatomprom. Reasons include:

    • Higher asset quality in Canada (notably McArthur River and Cigar Lake, considered “Tier 1” uranium mines).

    • Geopolitical risk and limited geographic diversification on Kazatomprom’s side.

    • Lower trading liquidity of Kazatomprom shares.

    Despite lower production costs, Kazatomprom’s average uranium sales price has been consistently below Cameco’s. In Q1 2025:

    • Kazatomprom: $54.69/lb

    • Cameco: $62.55/lb

    This pricing gap cannot be explained by logistics alone.

    Cost-wise, Kazatomprom’s ISR mining method allows for cash costs of $16.5–18/lb and AISC of $29–30.5/lb, while Cameco’s Canadian underground operations report:

    • Total production cost: C$32.69/lb (~$23.86 USD)

    • Cash cost: C$22.39/lb (~$16.34 USD)

    Cameco produced 10,400 tonnes in 2024 including its Inkai share, while Kazatomprom’s total production across all JVs reached 12,286 tonnes. The national total was 23,270 tonnes, suggesting Kazatomprom’s scale but also raising questions about labor efficiency—Kazatomprom employs ~22,000 people vs Cameco’s 6,200.

  • Kazakhstan’s Sarytogan Graphite Deposit Joins EU Strategic Project List

    Kazakhstan’s Sarytogan Graphite Deposit Joins EU Strategic Project List

    The Sarytogan graphite deposit in Kazakhstan’s Karaganda region has officially been added to the European Union’s list of strategic raw material projects, a move announced during the Astana Mining & Metallurgy (AMM) 2025 Congress in Astana.

    Preliminary assessments suggest that the Sarytogan site contains approximately 30% of the world’s known graphite reserves, making it one of the largest and cleanest surface-accessible graphite deposits globally. The project is seen as critical for securing the EU’s supply of materials vital to green technologies, particularly lithium-ion battery production.

    According to Galymzhan Torebek, Deputy Chair of the Committee for Industry under Kazakhstan’s Ministry of Industry and Construction, the graphite mining project will be developed in four stages, with capital expenditures estimated between $62 million and $344 million.

    The project’s new strategic status under the EU Critical Raw Materials Act (CRMA) means that the European Commission will now actively support the development by helping to attract investment and facilitate long-term supply agreements with European companies.

    At the AMM 2025 award ceremony, officials outlined plans for institutional and financial backing for the Sarytogan project, aiming to ensure stable offtake agreements, which would make the mine more appealing to international investors.

    The primary output from Sarytogan will include sterilized graphite, used as a stabilizer in EV batteries, and crystalline graphite, both critical components in the clean tech and high-performance electronics sectors.

  • Zijin’s Shadow: Villagers in Serbia and Tajikistan Bear Brunt of Chinese Mining Expansion

    Zijin’s Shadow: Villagers in Serbia and Tajikistan Bear Brunt of Chinese Mining Expansion

    In the hills of eastern Serbia and the valleys of western Tajikistan, villagers say they’re paying the price for China’s global mining ambitions. The Chinese-owned Zijin Mining Group, operating major copper and gold projects in both countries, stands accused of polluting the air, poisoning rivers, and displacing communities—while receiving strong political backing under the umbrella of Beijing’s Belt and Road Initiative (BRI).

    In Bor, Serbia, residents near Zijin’s Cukaru Peki copper mine complain of worsening air quality, arsenic, and fine particulate matter still lingering in the atmosphere despite the company’s reported $259 million investment in environmental improvements.

    “You used to see the smoke,” says Violeta, a Bor resident. “Now you don’t—but it still stinks.”

    In Krivelj, just outside Bor, Milos Bozic says the dust has made farming impossible. Professor Snezana Serbula of the Bor Technical Faculty confirms that PM particles and arsenic persist in the air. Meanwhile, residents like Dragoslav Stanculovic in nearby Ostrelj refuse to sell their properties. “What am I supposed to do—sell my dignity?” he asks.

    Despite environmental alarms, the Serbian government has doubled down on its support for Zijin, with Chinese companies now Serbia’s top exporters, surpassing $1 billion in trade by 2024.

    In Tajikistan, the story echoes Serbia’s. In Khumgaron and Shing, villagers say Zijin’s Zarafshon gold mine, where the company owns a 70% stake, has brought choking air and poisoned water. “Thick smoke covers the village in the morning,” says Abutolib Mukhtorov.

    Local residents in both countries report broken promises of relocation, inadequate compensation, and police intimidation of those who speak out. In Tajikistan, women who protested in Panjakent were detained. Firuza Kahorova recalls collapsing during the protest and being mocked by authorities: “They said, ‘Don’t give her water—give her dirt.’”

    Zijin claims 98% of Serbian land was acquired voluntarily and insists its projects meet environmental laws, branding Cukaru Peki as Serbia’s first “green mine.” In Tajikistan, Zijin has been fined, but continues operating with 20-year plans and strong support from the government, which highlights tax revenues and economic benefits.

    But for many residents, those benefits are illusory. “Peaches don’t grow. Cucumber flowers fall off. The river’s poisoned,” says Asadulo Rahmonov in Tajikistan. “It’s not progress. It’s survival.”

  • EU Weathers ‘Severe Market Disruption’ as China’s Antimony Controls Spark 170% Price Surge, Commission Finds

    EU Weathers ‘Severe Market Disruption’ as China’s Antimony Controls Spark 170% Price Surge, Commission Finds

    The European Union is well-positioned to weather, and potentially even benefit from, China’s new export controls on the critical raw material antimony, despite the measures causing a massive shock to global markets. A new policy brief from the European Commission’s Joint Research Centre (JRC) reveals that the EU’s strategic diversification of its supply chain has largely insulated it from the direct impact of the controls, which sent prices soaring by more than 170%.

    The report, “China’s Antimony Export Controls: Risks and Opportunities for the EU,” analyzes the fallout from China’s decision, effective September 15, 2024, to require dual-use export licenses for antimony and its products. The material is vital for defense applications—including armour-piercing rounds and night-vision equipment—as well as flame retardants, electronics, and batteries.

    The announcement immediately roiled the market, with the price of antimony metal surging from approximately 38,000 per tonne in September. The report describes this dramatic price jump as a reflection of “severe market disruptions, supply chain concerns, and potential shortages.”

    However, the JRC analysis concludes that the EU’s exposure is limited, thanks to years of proactive efforts to reduce its dependency on China.

    Key findings from the report include:

    • Diversified Supply Chains: While the EU is 100% reliant on imports for antimony ore, its primary supplier is Turkey (77%), not China. For antimony metal, the EU has dramatically shifted its sourcing, with Tajikistan now providing 52% of its imports. China’s share of the EU’s metal imports has fallen from 40% in 2020 to just 18% in 2023.

    • The US is More Exposed: The report highlights that the United States is far more vulnerable to the new regulations. China supplies 44% of US imports of antimony oxides—a refined product used in flame retardants and catalysts—compared to just 5% of EU imports.

    • An Opportunity for EU Exporters: The EU is a net exporter of high-value antimony oxides, producing 28,000 tonnes annually. The report suggests that if Chinese supply to the US and other markets is disrupted, EU producers could step in to fill the gap. “If European producers can secure stable antimony metal supplies, the EU may have an opportunity to expand exports,” the brief states.

    The report concludes that the EU’s strategic foresight in diversifying its critical mineral sources has turned a potential supply chain crisis into a manageable situation with a potential upside. While the dramatic price increase will affect all global users, the EU’s direct reliance on China is minimal, placing it in a resilient position compared to other major economies.

  • European Auto Sector Feels Strain as China’s Rare Earth Export Curbs Disrupt Supply Chains

    European Auto Sector Feels Strain as China’s Rare Earth Export Curbs Disrupt Supply Chains

    The European automotive sector is facing mounting pressure following China’s sweeping export restrictions on rare earth elements, which are critical to electric motors, high-tech components, and defense systems. Several parts suppliers have already suspended production, and major automakers like Mercedes-Benz and BMW are actively seeking ways to mitigate the risk of supply shortages.

    China’s decision in April to halt exports of a wide array of rare earths and related magnets has sent shockwaves through global industries, underlining Beijing’s dominant position—it produces about 90% of global rare earths and nearly 100% of heavy rare earths. The restrictions, introduced as part of broader trade tensions with the U.S., apply globally and have upended tightly synchronized supply chains.

    Mercedes-Benz production chief Joerg Burzer revealed that while its production remains unaffected for now, the company is working with suppliers to build “buffers” and stockpiles. Meanwhile, BMW confirmed supply disruptions within its supplier network, though its own production lines continue operating. Swedish airbag maker Autoliv and German electronics association ZVEI both confirmed the situation is under constant review, with task forces now in place.

    According to CLEPA, Europe’s auto supplier association, only 25% of export license requests from suppliers have been approved by China, with many rejected on “highly procedural grounds.” The group warned that additional factory shutdowns are likely.

    The issue is further complicating the already fragile geopolitical standoff between China and the U.S. President Donald Trump, who recently scaled back punitive tariffs following market turbulence, has accused China of violating recent truce terms. Chinese President Xi Jinping and Trump are expected to discuss the curbs in an upcoming call, with rare earths expected to top the agenda.

    With few viable alternatives to Chinese supply in the short term, auto manufacturers are scrambling to innovate. BMW has introduced magnet-free electric motors, while ZF and BorgWarner are developing low- to zero rare earth models—but commercial scalability remains years away.

    “There is no solution for the next three years except to come to an agreement with China,” said Andreas Kroll, managing director of Noble Elements, a rare earth importer.

    As rare earth supplies dwindle and diplomatic tensions escalate, Western governments are under growing pressure to accelerate diversification efforts. Brussels has already identified 13 non-EU mining projects to help reduce critical mineral dependency, and the EU’s industrial strategy chief Stephane Séjourné emphasized the urgency: “The export curbs increase our will to diversify.”